Abbott Laboratories (ABT)
- 3Q26 Revenue: US$13.013bn, +14.5% YoY reported and +7.0% comparable; approximately US$20m above consensus.
- 3Q26 EPS: Adjusted diluted EPS US$1.42, +9.2% YoY from US$1.30; beat US$1.41 consensus by US$0.01. GAAP EPS US$0.53 versus US$0.94, down 43.6%.
- 4Q26 Guidance: New Q4 adjusted EPS guidance US$1.62–1.67. The company did not provide numerical Q4 revenue guidance.
- FY26 Guidance: Adjusted EPS tightened to US$5.50–5.55 from US$5.45–5.60; midpoint unchanged at US$5.525. Comparable sales growth reduced to approximately 6.0% from 6.5–7.5%.
- Dividend/Share Buyback: Quarterly dividend US$0.63/share, payable 16 November to shareholders of record on 15 October. No new buyback programme announced in the reviewed earnings release.
- Comment: Abbott delivered a modest earnings beat, but the lower sales-growth outlook keeps our near-term view neutral. The unchanged EPS midpoint indicates that margin management can cushion softer revenue without yet establishing a stronger profit trajectory. Reported growth substantially exceeded comparable growth, so the headline increase should not be extrapolated as underlying demand. Medical devices remain central to the investment case, while the segment mix matters: nutrition and diagnostics exceeded expectations, whereas devices and established pharmaceuticals fell slightly short. Libre Duo’s approval supports the product pipeline, but commercial adoption must translate into sustained comparable growth. The gap between adjusted and GAAP earnings also deserves attention, with legal settlements and intangible amortisation among the excluded costs. These items do not erase operating progress, but they affect the economic return available to shareholders. The planned nutrition separation adds a potential portfolio catalyst alongside execution uncertainty; the investment case should rest on the remaining businesses’ earnings and cash generation rather than an assumed separation premium. At 2:54pm ET on 21 October, shares traded at US$98.99, down 3.38%; this was an intraday observation. Around 18 times the revised EPS midpoint, valuation is more reasonable, although an upgrade requires firmer device growth and confidence that the reduced sales target is achievable. 4Q26 recommended trading range: US$90–110. Neutral Outlook.
雅培 (ABT)
- 26财年第三季度营收:营收130.13亿美元,报告口径同比增14.5%,可比口径增7.0%;较市场预期高约2,000万美元。
- 26财年第三季度每股收益:经调整摊薄每股盈利1.42美元,较去年1.30美元增长9.2%;较1.41美元预期高0.01美元。GAAP每股盈利0.53美元,去年0.94美元,同比下降43.6%。
- 26财年第四季度指引:新增第四季度经调整每股盈利指引1.62–1.67美元。公司未提供第四季度收入量化指引。
- 26财年全年指引:经调整每股盈利区间由5.45–5.60美元收窄至5.50–5.55美元,中值维持5.525美元。可比收入增速由6.5–7.5%下调至约6.0%。
- 股息与回购:季度股息每股0.63美元,11月16日支付,登记日为10月15日。所审阅财报未宣布新的回购计划。
- 短评:雅培盈利小幅超预期,但收入增速指引下调,因此我们维持短期中性判断。每股盈利指引中值不变,说明利润率管理能够缓冲收入放缓,但尚未形成更强的盈利增长趋势。报告口径增速明显高于可比增速,不宜将表面增长直接视为基础需求。医疗器械仍是投资逻辑的核心,业务组合表现则值得关注:营养品及诊断业务优于预期,器械及成熟药品业务略低于预期。Libre Duo获批支持产品储备,但商业推广仍须转化为持续可比增长。调整后与GAAP盈利差距也应重视,剔除项目包括法律和解费用及无形资产摊销。这些费用不否定经营改善,却影响股东实际经济回报。拟分拆营养业务可能带来组合调整催化剂,同时增加执行不确定性;投资判断应基于剩余业务盈利及现金创造,而非预设分拆溢价。10月21日美东时间下午2时54分,股价98.99美元,跌3.38%,属于盘中观察。按修订后盈利指引中值计算,估值约18倍,已较合理,但上调展望仍需要器械增长改善,并确认降低后的收入目标能够实现。 2026年第四季度建议交易区间:90–110美元。中性前景。
Philip Morris International Inc. (PM)
- 3Q26 Revenue: Net revenue US$11.438bn, +5.5% YoY and +7.1% organically; beat US$11.28bn LSEG consensus by approximately US$158m.
- 3Q26 EPS: Adjusted diluted EPS US$2.36, +5.4% YoY and +5.8% excluding currency; beat Seeking Alpha consensus US$2.32 by US$0.04. Reported EPS US$2.12, down 4.9%.
- 4Q26 Guidance: The company did not provide standalone numerical Q4 revenue or EPS guidance. Management expects international smoke-free growth to reaccelerate, alongside higher U.S. investment and energy-related costs.
- FY26 Guidance: Adjusted EPS US$8.29–8.44 versus US$8.35–8.50 previously, a US$0.06 currency-only reduction. Ex-currency EPS US$8.11–8.26 unchanged. Organic revenue growth 5–7% and operating-income growth 7–9% retained; operating cash flow around US$13.5bn.
- Dividend/Share Buyback: Quarterly dividend increased 8.8% to US$1.60/share. FY26 forecast assumes no share repurchases; capex US$1.4–1.6bn and year-end net debt/adjusted EBITDA targeted close to 2.0x.
- Comment: Philip Morris remains a positive operating story despite the currency-related EPS reduction. Smoke-free products now contribute more than 40% of quarterly net revenue, while pricing and resilient combustible demand continue to finance the transition. Total shipments increased only modestly, so the ability to sustain pricing and improve product mix remains important to earnings growth. Organic revenue growth exceeded reported growth, and management retained its underlying EPS range; the lower dollar forecast therefore does not by itself indicate a weaker operating plan. However, investment in ZYN and higher energy and logistics costs constrain the near-term profit conversion. Management’s preference for the middle or upper half of its revenue range, but the middle or lower half of operating-income growth, makes this trade-off explicit. Our positive outlook rests on continued smoke-free adoption, cash generation and deleveraging rather than an immediate acceleration in EPS. The dividend increase adds support, although the absence of buybacks means operating delivery must carry the earnings case. Shares closed at US$197.51 on 21 October, down 1.20%. At approximately 23.6 times the adjusted EPS midpoint, the valuation already recognises the quality of the franchise. We would monitor international smoke-free reacceleration, U.S. investment returns and whether cost pressure persists beyond the fourth quarter before paying a higher multiple. 4Q26 recommended trading range: US$185–215. Positive Outlook.
菲利普莫里斯国际 (PM)
- 26财年第三季度营收:净收入114.38亿美元,同比增5.5%,有机增长7.1%;较LSEG市场预期112.8亿美元高约1.58亿美元。
- 26财年第三季度每股收益:经调整摊薄每股盈利2.36美元,同比增5.4%,剔除汇率增5.8%;较Seeking Alpha预期2.32美元高0.04美元。报告每股盈利2.12美元,同比下降4.9%。
- 26财年第四季度指引:公司未提供独立的第四季度收入或每股盈利量化指引。管理层预计国际无烟业务增长再加快,同时美国投入及能源相关成本上升。
- 26财年全年指引:经调整每股盈利由8.35–8.50美元下调至8.29–8.44美元,仅反映汇率影响0.06美元。剔除汇率区间8.11–8.26美元不变。有机收入增长5–7%、经营利润增长7–9%不变;经营现金流约135亿美元。
- 股息与回购:季度股息提高8.8%至每股1.60美元。全年预测假设不回购股份;资本开支14–16亿美元,目标年底净债务与经调整EBITDA比率接近2.0倍。
- 短评:尽管汇率导致每股盈利指引下调,菲莫的经营逻辑仍然正面。无烟产品已贡献季度净收入逾40%,定价能力及传统卷烟需求韧性继续为转型提供资金。总出货量仅温和增长,因此持续提价及改善产品组合仍是盈利增长的重要条件。有机收入增速高于报告增速,管理层维持基础盈利区间,美元指引下调本身并不代表经营计划恶化。然而,ZYN投入增加以及能源和物流成本上升,限制短期利润转化。管理层倾向收入增速落在指引中值至上半区间,而经营利润增速落在中值至下半区间,已明确体现这一权衡。我们的正面判断基于无烟产品采用、现金创造及去杠杆,并非预期盈利立即加速。股息提高提供支持,但没有回购意味着盈利逻辑更依赖经营交付。10月21日股价收报197.51美元,下跌1.20%。按经调整盈利指引中值计算约23.6倍,已反映业务质量。进一步提高估值前,应观察国际无烟增长再加快、美国投入回报,以及成本压力是否延续至第四季度之后。 2026年第四季度建议交易区间:185–215美元。正面前景。
Tesla Inc. (TSLA)
- 3Q26 Revenue: US$28.046bn, down 0.2% YoY from US$28.095bn; approximately US$294m below US$28.34bn consensus.
- 3Q26 EPS: Non-GAAP diluted EPS US$0.48, down 4.0% YoY from US$0.50; beat US$0.45 consensus by US$0.03. GAAP EPS US$0.22 versus US$0.39, down 43.6%.
- 4Q26 Guidance: The company did not provide numerical Q4 revenue or EPS guidance. Product ramps and autonomy deployment remain qualitative operating priorities.
- FY26 Guidance: The company did not provide numerical FY26 revenue or EPS guidance. Management reduced FY26 capital-spending expectations to approximately US$20bn from US$25bn on the earnings call.
- Dividend/Share Buyback: No cash dividend or share-buyback programme announced in the reviewed results. Cash and short-term investments US$45.447bn; Q3 operating cash flow US$6.263bn, capex US$4.732bn and free cash flow US$1.531bn.
- Comment: Tesla’s positive free cash flow offers relief, but the quarter does not yet establish a durable earnings recovery. Automotive gross margin excluding regulatory credits improved to approximately 18.1%, supported by the product and software mix. Yet revenue was broadly flat, and operating income fell to US$718m as research and development spending increased. Investors therefore need evidence that stronger unit economics can fund the expanding AI and robotics agenda without repeated pressure on cash. Lower capital spending contributed to the cash-flow surprise; this improves near-term funding flexibility but also raises questions about project timing. The balance sheet provides capacity to invest, although cash generation should be assessed alongside working-capital movements and future spending requirements. We regard autonomy and robotics as potential sources of value, with commercial returns still requiring validation. Possible SpaceX merger discussions add another source of volatility, without agreed transaction terms to incorporate into valuation. Shares were reported down approximately 3.2% in after-hours trading on 21 October following an initially mixed reaction. Our outlook is neutral: improved cash flow and automotive margins balance weaker operating profit and a demanding valuation. The proposed range uses revenue rather than depressed current earnings, but it still assumes a substantial premium for future businesses. Key checks are sustainable margins, recurring software revenue and the pace of cash investment. 4Q26 recommended trading range: US$350–420. Neutral Outlook.
特斯拉 (TSLA)
2026年第三季度财报更新 | 截至2026年10月22日
- 26财年第三季度营收:收入280.46亿美元,去年280.95亿美元,同比下降0.2%;较283.4亿美元预期低约2.94亿美元。
- 26财年第三季度每股收益:非GAAP摊薄每股盈利0.48美元,去年0.50美元,同比降4.0%;较0.45美元预期高0.03美元。GAAP每股盈利0.22美元,去年0.39美元,下降43.6%。
- 26财年第四季度指引:公司未提供第四季度收入或每股盈利量化指引。产品产能爬坡及自动驾驶部署仍属于定性经营重点。
- 26财年全年指引:公司未提供全年收入或每股盈利量化指引。管理层在电话会上将全年资本开支预期由250亿美元下调至约200亿美元。
- 股息与回购:所审阅业绩未宣布现金股息或股份回购计划。现金及短期投资454.47亿美元;季度经营现金流62.63亿美元、资本开支47.32亿美元、自由现金流15.31亿美元。
- 短评:自由现金流转正缓解了特斯拉的资金担忧,但本季度尚未确认持续盈利复苏。剔除监管积分的汽车毛利率改善至约18.1%,得到产品及软件组合支持。然而,收入大致持平,研发开支增加令经营利润降至7.18亿美元。投资者仍须确认单位经济性改善能否支持不断扩大的人工智能及机器人计划,并避免现金持续承压。资本开支低于预期帮助现金流超预期,改善短期融资弹性,但也引发项目进度问题。资产负债表提供投资空间,评估现金创造时仍须同时考虑营运资金变动及未来支出。我们认为自动驾驶及机器人具潜在价值,但商业回报仍需验证。与SpaceX可能合并的讨论增添波动,目前没有已议定交易条款可纳入估值。10月21日盘后股价据报道下跌约3.2%,此前初步反应反复。我们展望中性:现金流及汽车毛利率改善,与经营利润转弱及较高估值相互平衡。建议区间采用收入而非低迷的当期盈利作为参考,但仍包含对未来业务的显著溢价。应关注利润率可持续性、经常性软件收入及现金投入速度。 2026年第四季度建议交易区间:350–420美元。中性前景。
Meta Platforms Inc. (META)
- 3Q26 Revenue: US$64.601bn, +26.1% YoY; beat approximately US$63.34bn consensus by US$1.261bn.
- 3Q26 EPS: GAAP diluted EPS US$3.83 versus US$1.05, +264.8%. Excluding the Q3 litigation charge, EPS US$7.40; above the US$6.76 pre-release consensus by US$0.64 on that adjusted comparison. Prior-year GAAP EPS was depressed by a large tax charge.
- 4Q26 Guidance: New Q4 revenue guidance US$73–76bn, midpoint US$74.5bn; approximately US$850m above US$73.65bn consensus. Tax rate 15–17%. The company did not provide Q4 EPS guidance.
- FY26 Guidance: FY26 expenses US$175–179bn including the US$9.89bn legal charge. Capex narrowed to US$135–145bn from US$130–145bn. Reality Labs losses US$18–19bn. The company did not provide full-year revenue or EPS guidance.
- Dividend/Share Buyback: Q3 dividends and dividend equivalents US$1.361bn; no Class A share repurchases in Q3. Cash and marketable securities US$82.45bn. Announced nonvoting Class C common stock, effective January 2027.
- Comment: Meta’s advertising franchise remains strong, but cash demands and legal exposure keep our outlook neutral. Higher ad impressions and pricing supported revenue growth, and fourth-quarter guidance points to continued commercial momentum. The adjusted earnings figure helps assess that operating strength, while the GAAP growth rate is distorted by different large charges in the two periods. Investors should therefore avoid reading the headline EPS increase as underlying profit acceleration. AI is already supporting engagement and advertising, but incremental revenue must eventually justify the associated capital base. Quarterly operating cash flow was US$32.79bn, yet free cash flow was negative US$2.12bn after capital expenditures and finance-lease principal payments. Raising the lower end of annual capex reinforces the commitment to infrastructure and limits near-term cash returns. Separately, the US$25bn New Mexico privacy penalty announced on 21 October is distinct from the US$9.89bn quarterly litigation charge; its ultimate accounting and cash impact requires further disclosure. The proposed nonvoting share class also makes funding and governance worth monitoring. At 4:59pm ET on 21 October, shares were US$734.80, up 5.19% after hours from US$698.54. We would require evidence of improving cash conversion, controlled legal exposure and profitable AI monetisation before assigning a higher valuation despite the healthy advertising outlook. 4Q26 recommended trading range: US$650–800. Neutral Outlook.
Meta平台 (META)
- 26财年第三季度营收:营收646.01亿美元,同比增26.1%;较约633.4亿美元预期高12.61亿美元。
- 26财年第三季度每股收益:GAAP摊薄每股盈利3.83美元,去年1.05美元,增长264.8%。剔除本季诉讼费用后为7.40美元,按该调整口径较业绩前6.76美元预期高0.64美元。去年GAAP盈利受大额税项费用压低。
- 26财年第四季度指引:新增第四季度收入指引730–760亿美元,中值745亿美元,比736.5亿美元预期高约8.5亿美元;税率15–17%。公司未提供第四季度每股盈利指引。
- 26财年全年指引:全年费用1,750–1,790亿美元,包括98.9亿美元法律费用。资本开支由1,300–1,450亿美元收窄至1,350–1,450亿美元。Reality Labs亏损180–190亿美元。公司未提供全年收入或每股盈利指引。
- 股息与回购:季度股息及股息等价物13.61亿美元;季度未回购A类股份。现金及有价证券824.5亿美元。宣布设立无投票权C类普通股,2027年1月生效。
- 短评:Meta广告业务仍然强劲,但现金需求及法律风险使我们维持中性展望。广告展示量及价格上升支持收入增长,第四季度指引亦显示商业动能延续。调整后盈利有助评估经营实力,但两期不同的大额费用扭曲GAAP同比增长,因此不应将表面每股盈利增长理解为基础利润加速。人工智能已支持用户参与及广告表现,但新增收入最终须为相应资本投入提供合理回报。季度经营现金流327.9亿美元,扣除资本开支及融资租赁本金后,自由现金流为负21.2亿美元。提高全年资本开支下限进一步体现基础设施投入力度,并限制短期现金回报。另外,10月21日公布的新墨西哥州250亿美元隐私罚款,有别于本季度98.9亿美元诉讼费用;最终会计及现金影响仍待更多披露。拟设无投票权股份也使融资方式及治理值得关注。10月21日美东时间下午4时59分,盘后股价734.80美元,较收盘698.54美元上涨5.19%。尽管广告前景健康,我们仍需要现金转化改善、法律风险受控及人工智能实现盈利变现的证据,才会赋予更高估值。 2026年第四季度建议交易区间:650–800美元。中性前景。
International Business Machines Corp. (IBM)
- 3Q26 Revenue: US$17.103bn, +4.7% YoY and approximately +6% at constant currency; beat US$16.84bn consensus by US$263m.
- 3Q26 EPS: Operating non-GAAP diluted EPS US$2.95 versus US$2.65, +11.3%; beat US$2.87 consensus by US$0.08. GAAP continuing-operations EPS US$2.31 versus US$1.84, +25.5%; total EPS US$2.30.
- 4Q26 Guidance: The company did not provide standalone numerical Q4 revenue or EPS guidance in its earnings release.
- FY26 Guidance: Constant-currency revenue growth of 4–5% reaffirmed. Free cash flow now expected to increase by more than US$1bn YoY, versus approximately US$1bn previously. Currency expected neutral to full-year revenue growth. No numerical full-year EPS guidance provided.
- Dividend/Share Buyback: Quarterly dividend US$1.69/share, payable 10 December to holders of record on 10 November. Q3 dividends US$1.6bn. No new buyback authorisation announced in the release.
- Comment: IBM’s stronger software growth and higher cash-flow outlook support a positive view, although the recovery remains uneven. Revenue acceleration indicates that the weak second quarter did not become a broader deterioration. Software led the improvement, with Red Hat and data products supporting demand, while distributed infrastructure offset the mainframe-cycle decline. Consulting remained flat on a reported basis, so the quarter does not establish a broad enterprise-services rebound. Profit quality is better assessed through operating earnings than the larger GAAP increase, which benefited from the absence of a prior-year tax charge. Even on the adjusted basis, gross margin declined slightly, making operating-cost discipline important to the earnings outcome. Stronger quarterly free cash flow and the upgraded annual target provide more tangible support than the AI narrative alone. However, acquisitions and the higher debt balance mean cash allocation should remain disciplined. Our positive outlook is conditional on software momentum continuing into the seasonally important fourth quarter and on cash conversion supporting the dividend without sacrificing investment. At 4:59pm ET on 21 October, shares were US$258.75, up 2.93% after hours from US$251.38. Around 22 times annualised quarterly operating EPS, the stock allows room for recovery but already requires reliable delivery. We would monitor software deal conversion, consulting demand and the margin contribution from the changing infrastructure mix. 4Q26 recommended trading range: US$240–280. Positive Outlook.
国际商业机器公司 (IBM)
- 26财年第三季度营收:收入171.03亿美元,同比增4.7%,固定汇率增约6%;较168.4亿美元预期高2.63亿美元。
- 26财年第三季度每股收益:经营口径非GAAP摊薄每股盈利2.95美元,去年2.65美元,增11.3%;较2.87美元预期高0.08美元。GAAP持续经营每股盈利2.31美元,去年1.84美元,增25.5%;总每股盈利2.30美元。
- 26财年第四季度指引:公司在财报中未提供独立的第四季度收入或每股盈利量化指引。
- 26财年全年指引:维持固定汇率收入增长4–5%。自由现金流由此前预计同比增加约10亿美元,上调为增加超过10亿美元。汇率对全年收入增长预计中性。未提供全年每股盈利量化指引。
- 股息与回购:季度股息每股1.69美元,12月10日支付,登记日11月10日。季度派息16亿美元。财报未宣布新的回购授权。
- 短评:软件增长改善及现金流指引提高支持我们对IBM的正面判断,但复苏仍不均衡。收入增速回升,说明第二季度疲弱未演变为更广泛恶化。软件业务引领改善,Red Hat及数据产品支持需求,分布式基础设施抵消大型主机周期下滑。咨询业务报告收入持平,因此尚不足以确认企业服务全面复苏。盈利质量宜参考经营口径,而非更高的GAAP同比增幅,后者受去年税项费用不再出现所帮助。即使采用调整口径,毛利率也略降,使经营成本控制对盈利结果更重要。季度自由现金流改善及全年目标上调,为投资逻辑提供比人工智能叙事更具体的支持。但收购投入及较高债务水平要求现金配置保持纪律。我们的正面展望以软件动能延续至季节性重要的第四季度,以及现金转化在维持投资的同时支持股息为前提。10月21日美东时间下午4时59分,盘后股价258.75美元,较251.38美元收盘价上涨2.93%。按季度经营盈利年化计算约22倍,估值容许复苏空间,但亦要求稳定交付。应观察软件订单转收入、咨询需求,以及基础设施组合变化对利润率的影响。 2026年第四季度建议交易区间:240–280美元。正面前景。
Lam Research Corp. (LRCX)
- 1Q27 Revenue: FY27 Q1 revenue US$8.219bn, +54.4% YoY and +22.3% QoQ; approximately US$119m above US$8.10bn consensus.
- 1Q27 EPS: Non-GAAP diluted EPS US$2.20, +74.6% YoY from US$1.26; beat US$2.18 consensus by US$0.02. GAAP EPS US$2.19 versus US$1.24, +76.6%.
- 2Q27 Guidance: December quarter / FY27 Q2 revenue US$8.6bn ± US$400m; non-GAAP EPS US$2.33 ± US$0.15. Non-GAAP gross margin 52.5% ± 1 percentage point and operating margin 40.5% ± 1 point. New quarterly outlook.
- Full-year Guidance: The company did not provide full-year company revenue or EPS guidance. It forecasts calendar-2026 customer-support revenue growth above 30% and calendar-2027 growth above 15%; these are business-unit growth expectations, not group guidance.
- Dividend/Share Buyback: September-quarter repurchases US$1.011bn and cash dividends US$325m. Cash, cash equivalents and restricted cash US$7.451bn; quarterly capex US$258m.
- Comment: Lam delivered a strong operational quarter, but the small EPS surprise and muted market response favour a neutral near-term stance. AI-related demand and increasing device complexity support deposition and etch spending, and operating margin above 40% demonstrates substantial operating leverage. Systems revenue drove the sequential acceleration, while the customer-support business adds exposure to utilisation and the expanding installed base. That combination is attractive, although support revenue still depends on customer activity and should not be treated as immune to the semiconductor cycle. The December outlook points to further growth, but the pace is slower than the September step-up. Investors appear to have required a larger upward reset after the strong run in expectations. Management’s preliminary industry-spending view supports a multiyear opportunity, while cleanroom and component constraints can delay conversion into shipments. China represented 35% of quarterly revenue, leaving export restrictions and geographic mix material to the outlook. Cash generation and shareholder returns provide support, but they cannot remove customer-capex concentration. At 4:59pm ET on 21 October, shares traded at US$247.50, down 5.06% after hours from US$260.70. A more positive stance would require stronger order conversion and evidence that margins can hold as capacity expands, rather than relying solely on a higher industry-spending forecast. 4Q26 recommended trading range: US$225–270. Neutral Outlook.
泛林集团 (LRCX)
- 27财年第一季度营收:27财年第一季度收入82.19亿美元,同比增54.4%,环比增22.3%;较81亿美元预期高约1.19亿美元。
- 27财年第一季度每股收益:非GAAP摊薄每股盈利2.20美元,去年1.26美元,同比增74.6%;较2.18美元预期高0.02美元。GAAP每股盈利2.19美元,去年1.24美元,增长76.6%。
- 27财年第二季度指引:12月季度即27财年第二季度收入86亿美元,上下浮动4亿美元;非GAAP每股盈利2.33美元,上下浮动0.15美元。非GAAP毛利率52.5%,经营利润率40.5%,均上下浮动1个百分点。属于新增季度指引。
- 全年指引:公司未提供集团全年收入或每股盈利指引。预计2026日历年客户支持业务收入增长超过30%,2027年超过15%;这是业务部门增长预期,并非集团指引。
- 股息与回购:9月季度回购10.11亿美元,现金股息3.25亿美元。现金、现金等价物及受限现金74.51亿美元;季度资本开支2.58亿美元。
- 短评:泛林季度经营表现强劲,但每股盈利仅小幅超预期,市场反应疲弱,因此短期维持中性。人工智能需求及器件复杂程度提升支持沉积与刻蚀投入,经营利润率超过40%体现显著经营杠杆。系统业务带动环比加速,客户支持业务则受益于产能利用及装机基础扩大。这一组合具吸引力,但支持收入仍依赖客户活动,不宜视为完全不受半导体周期影响。12月季度指引显示继续增长,但增速低于9月季度的跃升。经历预期上升后,投资者似乎要求更大幅度的指引提高。管理层初步行业开支判断支持多年机会,但洁净室及零部件限制可能拖延出货兑现。中国占季度收入35%,使出口限制及地区组合仍是重要变量。现金创造及股东回报提供支持,却不能消除客户资本开支集中风险。10月21日美东时间下午4时59分,盘后股价247.50美元,较260.70美元收盘价下跌5.06%。估值采用12月季度每股盈利中值作为年化参考。更正面的判断需要订单转化加强,以及扩产时利润率能够维持的证据,而非仅依靠行业开支预测提高。 2026年第四季度建议交易区间:225–270美元。中性前景。
Texas Instruments Inc. (TXN)
- 3Q26 Revenue: US$6.055bn, +27.7% YoY and approximately +11% QoQ; beat US$5.92bn consensus by US$135m.
- 3Q26 EPS: GAAP diluted EPS US$2.62 versus US$1.48, +77.0%; beat US$2.42 consensus by US$0.20. Includes a US$0.01 reduction not in original guidance.
- 4Q26 Guidance: New Q4 revenue guidance US$5.80–6.30bn and EPS US$2.45–2.79; revenue midpoint US$6.05bn is approximately flat sequentially.
- FY26 Guidance: The company did not provide numerical full-year revenue or EPS guidance. FY26 capital spending remains US$2–3bn, with management expecting the upper end.
- Dividend/Share Buyback: Q3 dividends US$1.298bn and repurchases US$48m; total US$1.346bn. Trailing-12-month returns US$5.810bn. Cash dividends declared in Q3 US$1.42/share.
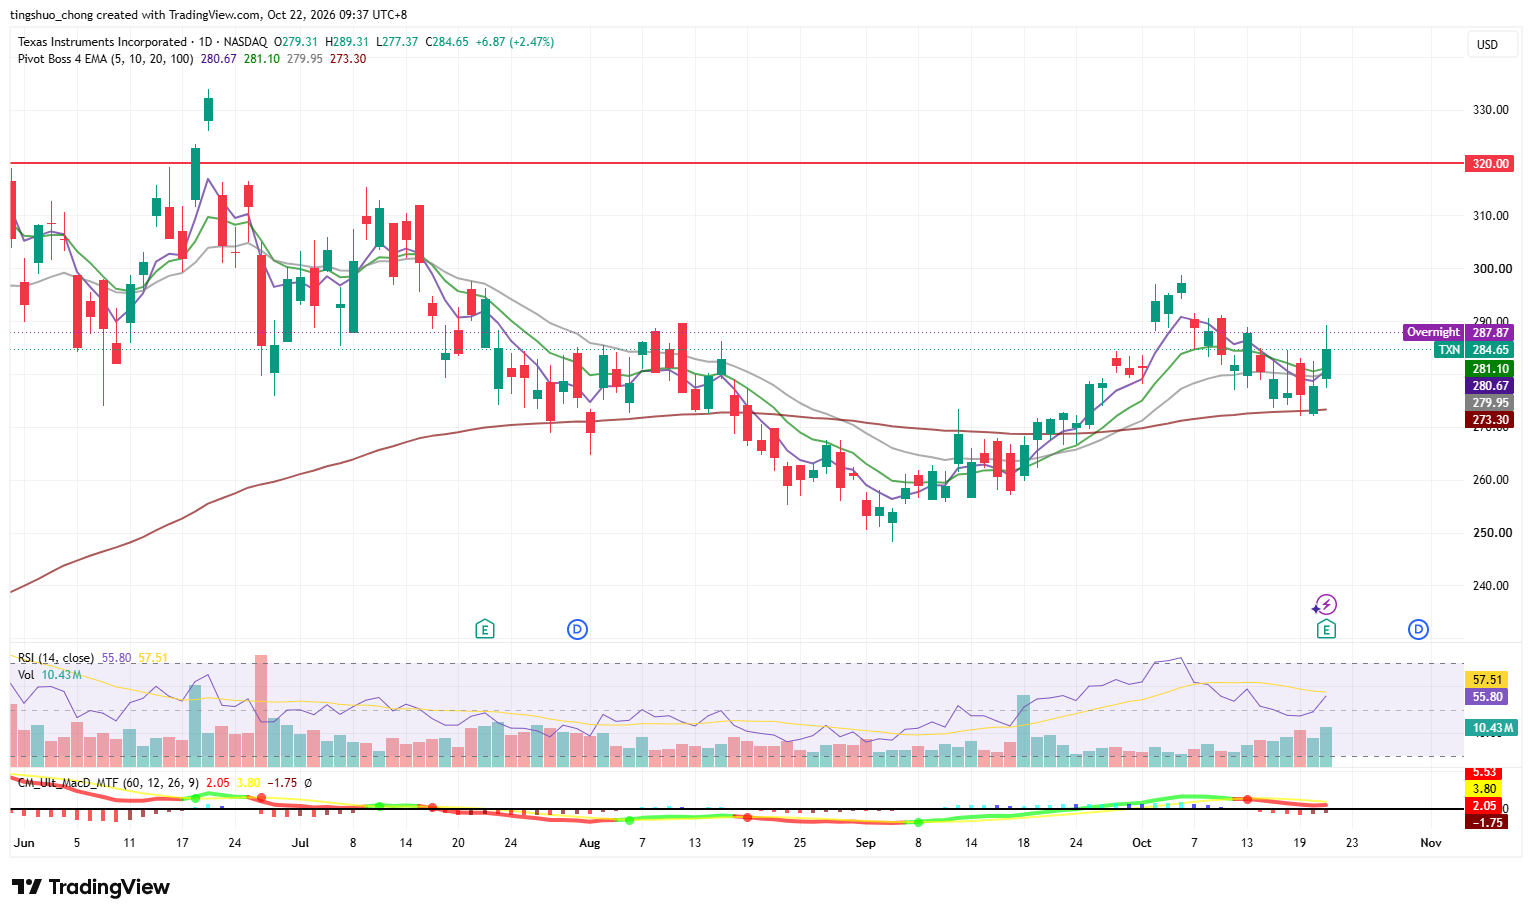
- Comment: Texas Instruments’ recovery is broadening, supporting a positive outlook despite an already demanding valuation. Industrial, automotive and data-centre demand all contributed, reducing dependence on a single end market. Higher semiconductor content adds a structural driver alongside the cyclical recovery, while stronger factory utilisation helps translate revenue into profit. The operating-profit increase was substantially faster than sales growth, consistent with that operating leverage. The key question is how much of the margin recovery can persist as production and customer inventories normalise. Fourth-quarter revenue guidance is approximately flat at the midpoint, which is constructive for a typically softer seasonal period, although it should not be described as another sequential acceleration. Cash conversion has improved materially, but the company’s free-cash-flow definition includes CHIPS Act incentive proceeds; investors should separate operating progress from government funding when assessing recurring cash generation. Lower capital intensity can increase the cash available to shareholders, while disciplined inventory management remains important as demand recovers. At 4:58pm ET on 21 October, shares were US$284.25, down 0.14% after hours from US$284.65, suggesting much of the recovery was already anticipated. Around 27 times annualised quarterly EPS, valuation requires the recovery to endure. We would monitor industrial orders, data-centre demand, utilisation and cash flow excluding incentives before extending the valuation range. 4Q26 recommended trading range: US$260–305. Positive Outlook.
德州仪器 (TXN)
- 26财年第三季度营收:营收60.55亿美元,同比增27.7%,环比约增11%;较59.2亿美元预期高1.35亿美元。
- 26财年第三季度每股收益:GAAP摊薄每股盈利2.62美元,去年1.48美元,增长77.0%;较2.42美元预期高0.20美元。包括原指引未计入的每股0.01美元负面影响。
- 26财年第四季度指引:新增第四季度收入指引58–63亿美元,每股盈利2.45–2.79美元;收入中值60.5亿美元,环比大致持平。
- 26财年全年指引:公司未提供全年收入或每股盈利量化指引。全年资本开支维持20–30亿美元,管理层预计接近上限。
- 股息与回购:季度派息12.98亿美元,回购4,800万美元,合计13.46亿美元。过去12个月股东回报58.10亿美元。第三季度宣派每股股息1.42美元。
- 短评:德州仪器复苏范围扩大,支持正面展望,尽管估值已较高。工业、汽车及数据中心需求均有贡献,降低对单一终端市场的依赖。半导体含量提升在周期复苏之外增添结构性动力,工厂利用率提高则帮助收入转化为盈利。经营利润增速明显高于销售,与经营杠杆改善一致。关键是生产及客户库存恢复正常后,利润率复苏有多少能够维持。第四季度收入指引中值环比约持平,在通常较弱的季节仍属积极,但不应描述为环比再次加速。现金转化已明显改善,不过公司自由现金流定义包含CHIPS法案激励款项;评估经常性现金创造时,应将经营改善与政府资金区分。资本密集度降低可增加股东可获现金,同时需求复苏过程中仍须谨慎管理库存。10月21日美东时间下午4时58分,盘后股价284.25美元,较284.65美元收盘价下跌0.14%,说明市场可能已预期相当部分复苏。按季度盈利年化计算约27倍,估值要求复苏持续。提高估值区间前,应关注工业订单、数据中心需求、产能利用率,以及剔除激励款项后的现金流。 2026年第四季度建议交易区间:260–305美元。正面前景。