TECHNICAL ANALYSIS

Technical Analysis: 17 September 2026

Singapore

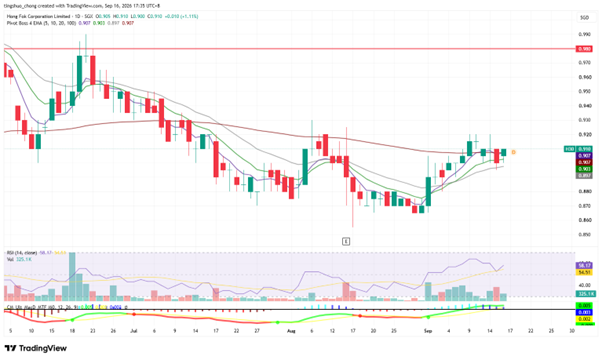
HFC SP

Hong Fok Corporation Limited.

  • Shares closed above the 5dEMA with rising volume.
  • Both RSI and MACD are constructive.
  • Buy Entry 0.90, Target 0.98, Stop 0.88

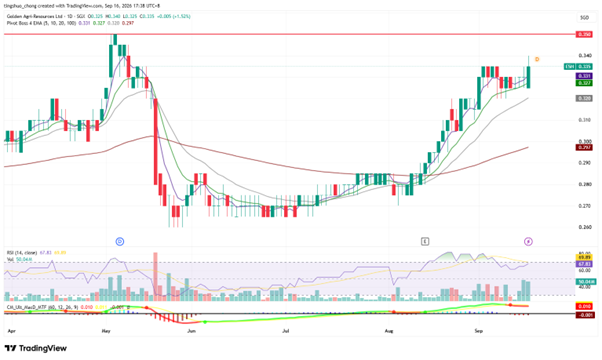
GGR SP

Golden Agri-Resources Ltd.

  • Shares closed above the 5dEMA with rising volume.
  • Both RSI and MACD are constructive.
  • Buy – Entry 0.33, Target 0.35, Stop 0.31

Hong Kong

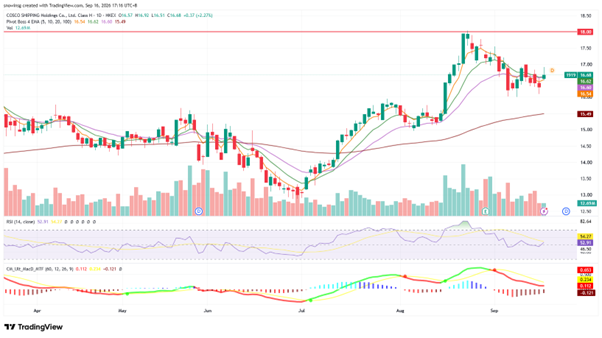
1919 HK

COSCO Shipping Holdings Co Ltd

  • Shares closed above the 10dEMA with rising volume.
  • RSI is constructive, while MACD is negative.
  • Long – Entry 16.6, Target 18.0, Stop 16.0

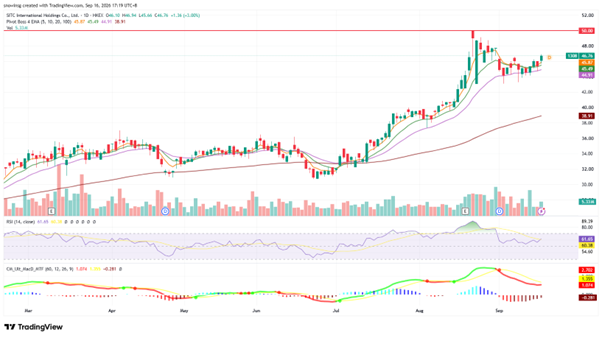
1308 HK

SITC International Holdings Co Ltd

  • Shares closed above the 5dEMA with rising volume.
  • RSI is constructive, while MACD is negative.
  • Long – Entry 46, Target 50, Stop 44

United States

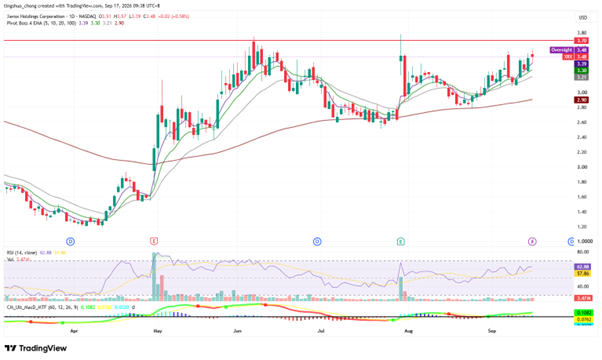
XRX US

Xerox Holdings Corporation

  • Shares closed above the 5dEMA with rising volume.
  • RSI is near overbought levels, but MACD is still constructive.
  • Long – Entry 3.30, Target 3.70, Stop 3.10

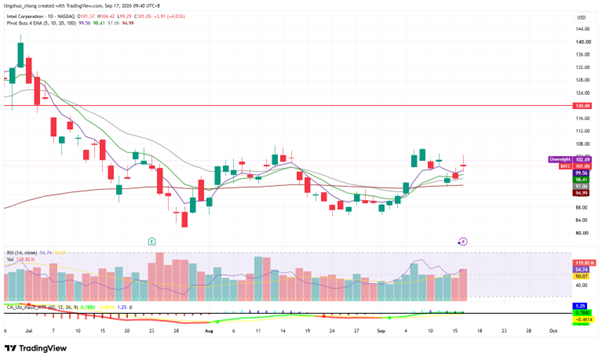
INTC US

Intel Corporation

  • Shares closed above the 5dEMA with rising volume.
  • Both RSI and MACD are constructive.
  • Long – Entry 102, Target 120, Stop 93

^ Back to Top

Earnings

Lennar Corporation (LEN)

  • 3Q26 Revenue: $8.0B, -9.2% YoY, miss estimates by $370M
  • 3Q26 Non-GAAP EPADS: $1.23, miss estimates by $0.06
  • FY26 Guidance: Cut FY26 delivery guidance to approximately 80,000–81,000 homes from 82,000–83,000 previously. For 4Q26, management expects 19,500–20,500 new orders, 22,000–23,000 deliveries, average selling price of US$370,000–380,000, gross margin of 15.5–16.0% and SG&A of 8.7–9.0%. The lower delivery target reflects weaker housing conditions and continued affordability pressure from elevated mortgage rates.
  • Dividend/ Share Buybacks: Repurchased approximately 3.0M shares for US$256M during the quarter at an average price of US$85.49/share
  • Comment: This was a weak quarter and, more importantly, the forward indicators deteriorated. Revenue and adjusted EPS both missed, FY26 deliveries were cut again, and 4Q gross-margin guidance of 15.5–16.0% suggests incentives will remain elevated. Lennar is deliberately protecting volume rather than price, with incentives running at approximately 12% of ASP. That strategy helps inventory turns and construction efficiency, but it comes at the cost of profitability. There are some positives beneath the headline weakness. Construction cost per square foot fell another 6% YoY, cycle time improved to a record 116 days, completed unsold inventory declined to 1.8 homes per community, and book value remains substantial relative to the share price. The longer-term housing undersupply thesis also remains intact. However, these operational improvements are currently being overwhelmed by affordability pressure. Mortgage rates were around 6.8% at quarter-end and moved even higher subsequently, while consumer confidence weakened. Shares closed at US$78.36 before falling to approximately US$75–76 after hours, roughly 3% lower following earnings. At that level, LEN is already trading close to its 52-week low and at roughly 13–14x trailing earnings, so valuation support is becoming more relevant. The principal variables to monitor are mortgage rates, incentives as a percentage of ASP, gross margin, new orders, cancellations, inventory turns and whether FY27 EPS estimates have finally reached a trough. 4Q26 recommended trading range: $70 to $88. Negative Outlook.
 

莱纳房屋(LEN)


  • 26财年第三季度营收:80亿美元,同比下降2%,低于预期3.7亿美元
  • 26财年第三季度非公认会计准则每股收益:23美元,低于预期0.06美元
  • 26财年全年及第四季度指引:下调全年交付指引至约0万–8.1万套(此前为8.2万–8.3万套);
  • Q4指引:预计新增订单95万–2.05万套,交付2.2万–2.3万套,平均售价(ASP)为37万–38万美元,毛利率预计为15.5%–16.0%,SG&A(销售、一般及行政费用)占比为8.7%–9.0%。下调交付目标直接反映了疲软的住房市场环境,以及高抵押贷款利率带来的持续购房负担能力(affordability)压力。
  • 股息与回购:本季度回购约300万股,耗资约56亿美元,平均回购价格约为85.49美元/股。
  • 短评:本季度表现疲软,且更具前瞻性的指标出现明显恶化。营收与调整后EPS双双不及预期,全年交付目标再次下调,且Q4毛利率指引(5%–16.0%)暗示促销激励措施(incentives)。核心战略与代价:莱纳目前采取了明确的“保量不保价”策略,当前的促销激励成本约占平均售价(ASP)的12%。这一策略有助于加快库存周转并维持施工端的规模效率,但代价是直接牺牲了短期的账面盈利能力。底层运营亮点:在表观数据的疲软之下,公司的运营效率仍在提升。每平方英尺建筑成本同比再降6%,施工周期缩短至创纪录的116天,已完工未售库存降至每个社区仅1.8套的健康水平。此外,长期的“美国住房供应短缺”逻辑依然成立,且公司每股账面价值相对于当前股价依然非常厚实,提供了较强的资产底线。核心隐忧(宏观逆风):然而,这些运营层面的改善目前正被购房负担能力危机所淹没。季度末抵押贷款利率在6.8%左右,且随后进一步走高,叠加消费者信心走弱,严重压制了实质性的购房需求。估值与市场反应:财报前股价收于78.36美元,盘后下跌约3%至75–76美元区间。在这一水位,LEN已逼近52周低点,且滚动市盈率仅约13–14倍,估值支撑(valuation support)正变得愈发重要,市场正在寻找盈利预期的底部。后续关键变量包括:(1)宏观抵押贷款利率的走势;(2)促销激励成本占ASP的比例变化;(3)毛利率的企稳情况;(4)新增订单量与订单取消率(cancellations);(5)库存周转效率;(6)市场对27财年EPS预期是否已真正触底的确认。莱纳房屋作为美国头部住宅建筑商,拥有卓越的供应链管理、成本控制能力以及极具韧性的资产负债表。但在高利率环境彻底扭转或购房负担能力实质性改善之前,短期的“以价换量”策略将持续压制其盈利表现与估值扩张,需耐心等待宏观周期的拐点。26财年第四季度建议交易区间:70美元至88美元。负面前景。

^ Back to Top