SGX SP
Singapore market revival, multi-asset growth, and post-correction valuation reset
KEY INSIGHTS #1
Singapore’s equity-market revival is translating directly into higher trading activity.
Singapore equities are experiencing their strongest participation cycle in years, helped by the Equities Market Review measures, stronger retail involvement and renewed institutional interest. August securities daily average value rose 35% YoY to around S$2.2B, while total securities turnover increased 29% to S$43.3B. The STI subsequently reached a record 5,828.5 in September, while combined STI ETF AUM exceeded S$6B for the first time. More importantly, activity is broadening beyond banks and index names, with nearly 220 stocks averaging more than S$100,000 of daily turnover in 9M26 versus fewer than 200 in 9M25. Higher market velocity directly supports SGX’s clearing, trading and market-data revenue.
KEY INSIGHTS #2
The recent 20% correction has reset valuation while capital returns remain strong.
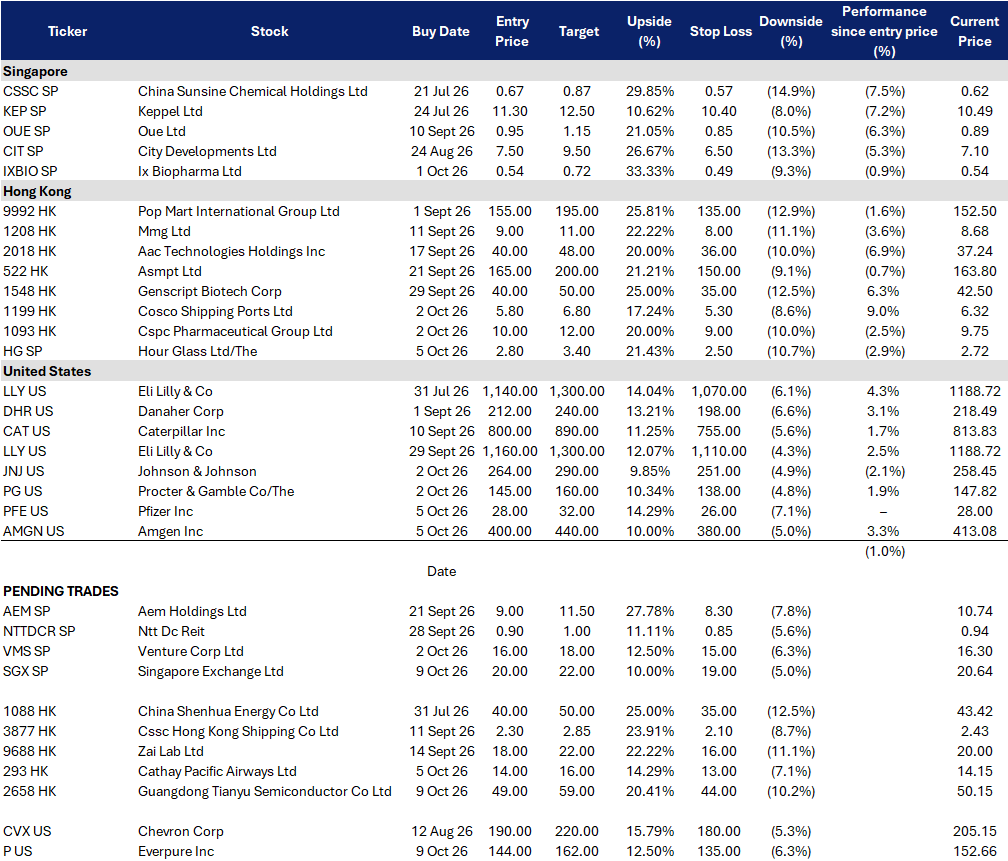
S68 has fallen from above S$25 in early September to around S$20.6 on 8 October, including a 7.2% decline on 2 October following a sharp valuation reset and a JPMorgan downgrade to S$23.00. The correction leaves the shares around 27x forward earnings versus a current analyst consensus target near S$24.2. Meanwhile, FY26 total dividends reached S$0.57 per share, including a S$0.125 one-off additional dividend, supported by record earnings. With underlying trading activity still healthy, the selloff creates a cleaner entry around S$20.50 for a recovery toward S$24.50 if FY27 earnings continue to compound.

HG SP
Scarcity-brand resilience, balance-sheet strength, and buyback support
KEY INSIGHTS #1
High-end watch demand remains resilient despite a difficult broader luxury backdrop.
The luxury-watch industry continues to face a strong Swiss franc, elevated precious-metal prices and softer discretionary spending, but demand remains increasingly polarised toward scarce brands with strong collector ecosystems. The Hour Glass is positioned at the favourable end of this divide through long-standing allocations from Rolex, Patek Philippe and leading independents. FY26 revenue grew 15.1% YoY to a record S$1.34B despite these industry headwinds, while profit after tax increased 32% to S$179.5M. This suggests its brand mix, geographical diversification and allocation relationships are allowing it to outperform the broader luxury-watch cycle.
KEY INSIGHTS #2
Inventory and a debt-free balance sheet provide strategic flexibility rather than financial risk.
Inventories increased to S$362.2M at end-FY26 from S$328.3M a year earlier, but for The Hour Glass a portion of this inventory represents access to scarce high-value watches rather than conventional excess retail stock. More importantly, the group ended FY26 with S$157.5M of cash and bank balances and, for the first time in its history, no borrowings. Net asset value reached S$1.07B, or approximately S$1.67 per share. This allows management to continue investing in flagship boutiques and inventory while remaining insulated from higher financing costs and giving the group substantial flexibility to return capital.
2658 HK
8-inch SiC ramp, margin normalization, and aggressive buyback support
KEY INSIGHTS #1
The transition to 8-inch SiC creates a structural growth opportunity despite near-term industry price pressure.
SiC adoption continues to broaden across EV powertrains, charging infrastructure, renewable energy and high-efficiency power conversion, while the industry is progressively shifting from 6-inch toward more cost-efficient 8-inch wafers. Tianyu is one of the few Chinese suppliers already capable of mass-producing 8-inch SiC epitaxial wafers. In 1H26, 8-inch revenue increased 40.5% YoY to RMB147.1M and overtook 6-inch revenue of RMB146.8M, helping group revenue rise 4.3% to RMB347.9M despite aggressive industry pricing. The improving product mix gives Tianyu substantial operating leverage if 8-inch demand continues scaling.
KEY INSIGHTS #2
Management is actively buying shares after the post-results collapse.
Tianyu announced an H-share repurchase programme in September covering up to 5.90M shares, equivalent to 10% of the H shares outstanding at the time, explicitly citing confidence in the company’s development prospects and valuation. Repurchases have continued repeatedly through early October, with 386,950 shares already accumulated by 6 October, including purchases at an average HK$52.15 that day. The shares have rebounded from HK$32.80 on 14 September to HK$52.00 on 7 October, so chasing the move offers less attractive risk-reward. An entry nearer HK$49.50 provides a cleaner setup for a recovery toward the HK$58 IPO price and ultimately the previous HK$63.50 high if 8-inch margins begin stabilising.
293 HK
Premium travel resilience, cargo strength, and capacity-driven earnings upside
KEY INSIGHTS #1
Passenger and cargo demand remain stronger than the broader airline-cycle slowdown suggests.
Cathay Pacific carried 15% more passengers YoY in the first eight months of 2026, while August passenger volumes increased another 5% despite only 3% ASK growth. Cathay Pacific and HK Express together carried a record 3.6M passengers in August, while Cathay Cargo tonnage rose 9% YoY to more than 150,000 tonnes. Premium travel demand remains resilient and cargo continues to benefit from semiconductor, pharmaceutical and time-sensitive shipments, helping offset industry-wide concerns around capacity normalisation and weaker yields.
KEY INSIGHTS #2
Capacity expansion and stronger shareholder returns provide the next rerating catalysts.
Cathay has committed around HK$150B to fleet, cabin, lounge and digital investments and targets 150 new aircraft and a 150-destination network over the next decade, creating a multi-year capacity-growth runway as Hong Kong’s three-runway system scales. Nearer term, stronger cash generation has already translated into a HK$0.26 interim dividend, +30% YoY, while DBS forecasts FY26 DPS of HK$0.90, implying roughly a 6% yield around current levels. With 0293 HK trading near HK$14.35 versus DBS’s HK$18.00 target, a pullback toward HK$14.30 offers attractive risk-reward if passenger demand remains firm and jet-fuel prices moderate.
P US
AI-era storage and data-management platform leveraged to hyperscale infrastructure growth
KEY INSIGHTS #1
Hyperscale wins and data-management expansion are widening the growth opportunity.
Everpure is expanding beyond traditional enterprise storage into hyperscale infrastructure, Scale AI and modern data-management software, giving it several incremental growth engines. The company has now secured design wins with two top-five hyperscalers, with its DirectFlash architecture designed to reduce storage power, cooling and rack-space requirements, while the acquisition of 1touch and new data-management capabilities extend the platform into data discovery, governance and AI-ready data orchestration. This momentum is already visible financially, with 2Q27 revenue rising 38% YoY to US$1.2bn, subscription ARR increasing 20% to US$2.1bn, and RPO growing 44% to US$4.1bn.
KEY INSIGHTS #2
AI data-centre buildout increases the value of efficient storage and data management.
The AI infrastructure boom is driving a sharp increase in data-centre capacity, but power, cooling and physical space are increasingly becoming constraints, raising the importance of storage architectures that can deliver more capacity with lower energy and rack requirements. Everpure estimates that its DirectFlash technology can reduce storage space, power and cooling requirements by 80-90%, while enterprises moving AI workloads from pilots into production are also creating greater demand for governed, accessible and AI-ready data; this positions Everpure to benefit from both the physical expansion of AI data centres and the shift toward more sophisticated enterprise data management. Global AI-related infrastructure spending remains substantial, with projections for cumulative data-centre investment of more than US$30tn by 2050.
AMGN US
Diversified biopharma growth platform with obesity and oncology optionality
KEY INSIGHTS #1
Multiple growth franchises are offsetting legacy-product erosion.
Amgen’s growth is increasingly diversified, with 2Q26 revenue up 10% YoY to US$10.1bn and its six key growth drivers increasing 26%, representing nearly 70% of product sales. Repatha and EVENITY grew 37% and 38% YoY, respectively, while small-cell lung cancer therapy IMDELLTRA surged 115% to US$288mn; ongoing development of extended and subcutaneous dosing could further improve convenience and broaden adoption, helping offset biosimilar pressure on mature products such as Prolia and XGEVA.
KEY INSIGHTS #2
Expanding obesity treatment market creates a major new growth opportunity.
More than 1bn people globally live with obesity, while the obesity-drug market is expected to exceed US$100bn annually over the coming decade as treatment penetration expands and next-generation therapies compete on efficacy and dosing convenience. Amgen’s MariTide is already in multiple Phase III programmes, including obesity, diabetes, cardiovascular outcomes and sleep apnoea, with its long-acting design supporting monthly or potentially less-frequent dosing and giving Amgen differentiated exposure to one of the fastest-growing pharmaceutical markets.
STOCKS
STOCKS
–
STOCKS