VMS SP
AI infrastructure recovery, product-cycle inflection, and margin resilience
KEY INSIGHTS #1
AI infrastructure is pulling Venture back into growth after three years of contraction.
he recovery accelerated in 2Q26, with revenue rising 12.5% YoY and net profit increasing 10.3%. Portfolio B, which includes Test & Measurement, Networking & Communications and Semiconductor Related Equipment, grew 25.7% YoY as AI infrastructure spending drove stronger customer demand. For 1H26, Portfolio B revenue increased 18.6% to S$916M, more than offsetting weakness in consumer-facing businesses. Venture therefore offers a differentiated way to participate in AI capex through test, networking and semiconductor equipment without relying on a single chip architecture or customer.
KEY INSIGHTS #2
S$1.1B net cash provides downside protection while preserving upside from new programmes.
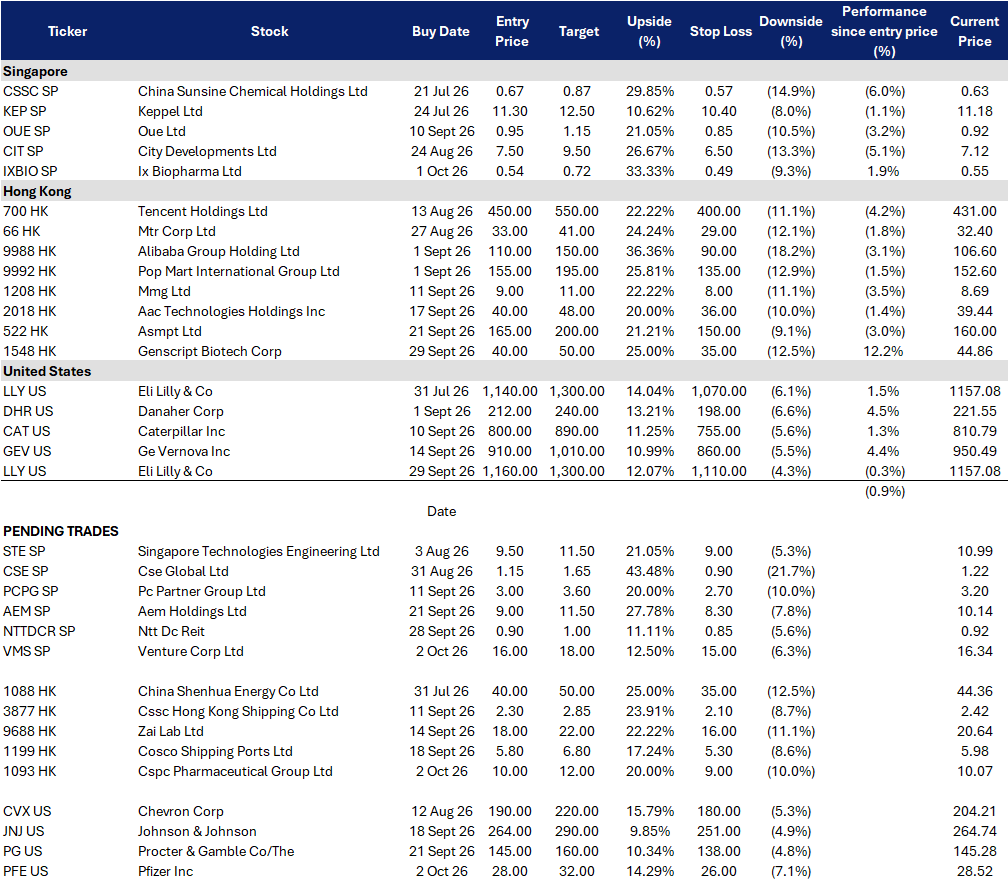
Venture ended June with around S$1.11B of net cash, equivalent to roughly 24% of its market capitalisation at the time, while maintaining an earnings model built around high-value engineering rather than commoditised manufacturing. This balance sheet gives management flexibility to invest in new programmes while supporting dividends through the recovery. With V03 closing at S$16.23 on 30 September versus DBS’s recently raised S$22.90 target, an entry around S$16.30 offers a cleaner risk-reward if AI-related demand remains strong and the 4Q26 consumer-product ramp provides the next earnings catalyst.
NTTDCR SP
AI data-centre demand, leasing uplift, and sponsor-backed acquisition growth
KEY INSIGHTS #1
AI and cloud demand continue to tighten high-quality data-centre capacity.
Data-centre leasing remains structurally supported by hyperscaler AI capex and cloud infrastructure expansion, particularly in established markets where power availability and permitting constrain new supply. NTT DC REIT’s committed portfolio occupancy reached 99.2% in 1QFY27 versus physical occupancy of 95.9%, with most newly committed leases expected to begin contributing from 3QFY27. Rental reversions were also strong at +13.4%, including a 23% uplift on the SG1 NTT master-services agreement renewal, providing visible organic revenue growth without requiring acquisitions.
KEY INSIGHTS #2
NTT’s acquisition pipeline can more than double the portfolio over time.
The sponsor ROFR pipeline includes roughly 130MW of identified near-term acquisition opportunities versus the current portfolio of about 91MW, with management targeting deployment over the next three to five years. NTT DC REIT also joined the FTSE EPRA Nareit Global Developed Index on 21 September, which should broaden institutional ownership and improve liquidity. With units closing at US$0.92 on 24 September versus UOB’s US$1.31 target, the current price offers an attractive setup if committed leasing converts into revenue and the first sponsor-backed acquisition is executed without excessive equity dilution.
1093 HK
Licensing monetisation, ADC pipeline acceleration, and metabolic optionality
KEY INSIGHTS #1
China biotech licensing momentum is becoming a material earnings driver.
CSPC’s 1H26 revenue surged 40.1% YoY to RMB18.59B, while underlying attributable profit rose 165.8% to RMB6.16B, largely reflecting the monetisation of its innovative pipeline. The standout transaction was the AstraZeneca strategic collaboration covering eight long-acting peptide programmes, which included a US$1.2B upfront payment and up to US$17.3B of potential milestones. CSPC also received another US$30M upfront payment from AstraZeneca in August for a separate siRNA collaboration. These deals validate the external value of CSPC’s R&D platforms and create a funding source that can support development without relying solely on domestic drug sales.
KEY INSIGHTS #2
The pipeline is moving from early-stage optionality toward registrational assets.
CSPC has multiple late-stage programmes capable of reducing dependence on legacy products. On 24 September, the Phase III trial of JMT101 plus osimertinib in first-line EGFR exon 20 insertion NSCLC delivered positive topline results, while SYS6010 has received multiple breakthrough-therapy designations in China across lung and oesophageal cancers. The company is also advancing albumin-bound docetaxel into Phase III breast-cancer studies and continues to broaden its ADC portfolio. The key rerating question is therefore whether these programmes can transition CSPC from a mature pharma franchise into a higher-growth innovative-drug platform.
1548 HK
AI drug-discovery infrastructure, operating leverage, and ProBio value unlock
KEY INSIGHTS #1
Eli Lilly partnership validates GenScript as infrastructure for AI-driven drug discovery.
GenScript’s strongest new catalyst is its 16 September collaboration with Lilly TuneLab, Eli Lilly’s AI/ML drug-discovery platform. GenScript will provide wet-lab services that convert AI-generated drug predictions into experimentally validated biological data, positioning the company at the critical bridge between computational discovery and physical testing. This follows 1H26 AI-enabled drug-discovery revenue roughly doubling YoY for a third consecutive half. The market reacted strongly, with 1548 HK rising 14.3% on 17 September and another 5.7% the following day, suggesting investors are beginning to value GenScript as an AI-biotech infrastructure play rather than a conventional life-science reagent supplier.
KEY INSIGHTS #2
ProBio spin-off and fresh AI investment provide another valuation catalyst.
GenScript has received HKEX clearance to proceed with the proposed separate listing of ProBio while retaining control, creating an opportunity to crystallise the value of its fast-growing biologics and advanced-therapy CDMO franchise. Separately, the September share placement raised approximately HK$2.33B net, with around 70% earmarked for expanding AI-drug-discovery production capacity and infrastructure and another 20% for AIDD-related R&D, digital integration and global expansion. The stock has already rerated sharply to HK$39.74 from around HK$30 earlier in September, so chasing above HK$40 carries higher risk. A pullback toward HK$37.50 provides a cleaner entry while preserving upside from ProBio monetisation, continued AI-discovery growth and further operating leverage.
PFE US
Oncology-led earnings recovery supported by pipeline catalysts and cost discipline
KEY INSIGHTS #1
ADCEV growth and ESMO catalysts strengthen the post-COVID portfolio.
Pfizer’s underlying business is improving as newer products offset declining COVID revenues, with 2Q26 revenue excluding Comirnaty and Paxlovid up 5% operationally and launched/acquired products growing 18%. PADCEV was a key contributor, with revenue increasing 23% operationally, while its July FDA label expansion into perioperative muscle-invasive bladder cancer regardless of cisplatin eligibility broadens the addressable market; at ESMO 2026 on 23–27 October, Pfizer will present 45 oncology abstracts, including 11 oral presentations, spanning PADCEV and late-stage candidates such as atirmociclib and tivunatamig, providing several near-term pipeline catalysts.
KEY INSIGHTS #2
Sustained oncology innovation supports demand for next-generation cancer therapies.
Oncology remains the largest pharmaceutical therapeutic market, reaching approximately US$291bn in 2025, with IQVIA forecasting around 10% CAGR from 2026–30 as new treatment modalities increasingly reshape cancer care. Antibody-drug conjugates and bispecific antibodies are expected to become larger contributors to oncology spending, supporting Pfizer’s strategy following the Seagen acquisition and its focus on assets such as PADCEV and other next-generation oncology therapies.

LLY US
Extending its growth runway through weekly insulin and pipeline expansion
KEY INSIGHTS #1
Onswik strengthens the diabetes franchise while external partnerships expand pipeline optionality.
The FDA approval of Onswik, Lilly’s once-weekly basal insulin for adults with type 2 diabetes, adds a differentiated treatment to an already broad cardiometabolic portfolio spanning insulin, incretins and other therapies. Onswik met its primary endpoint across the QWINT Phase III programme involving more than 3,400 patients and could reduce basal insulin injections from roughly 365 to 52 per year; alongside this, Lilly’s new InnoCare partnership targets up to five new drug programmes, with up to US$3.25bn of potential development and commercial milestones, broadening its longer-term discovery pipeline.
KEY INSIGHTS #2
Rising diabetes prevalence supports demand for simpler chronic-disease treatments.
Diabetes remains a structurally growing healthcare burden, with around 40.1mn Americans, roughly one in eight, living with the disease, while globally 589mn adults had diabetes in 2024 and this is projected to reach 853mn by 2050. As type 2 diabetes accounts for most cases, therapies that reduce treatment burden and improve convenience should become increasingly important, supporting long-term demand for differentiated products such as once-weekly insulin alongside Lilly’s broader cardiometabolic franchise.
STOCKS
STOCKS
STOCKS