DBS SP
Wealth-management compounding, NIM resilience, and post-selloff reset
KEY INSIGHTS #1
The sharp Singapore-bank selloff creates a better entry while the macro backdrop remains supportive.
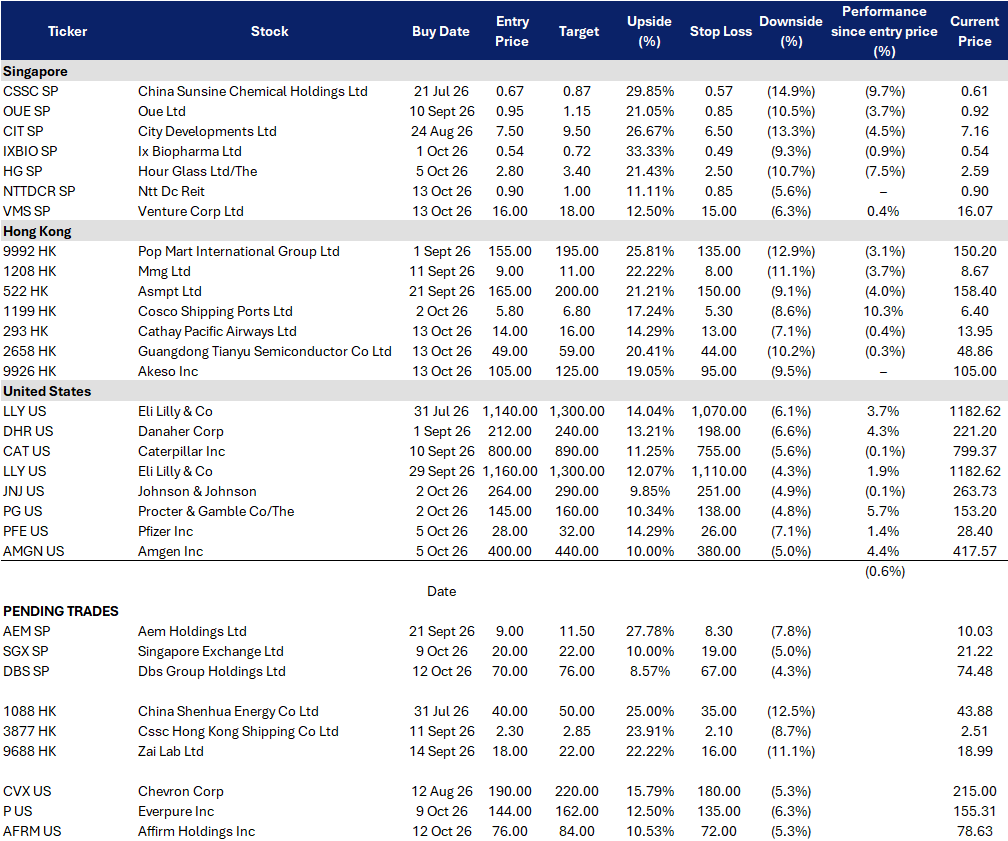
DBS fell 4.7% on 8 October and traded around S$73 on 9 October after a sector-wide selloff triggered by profit-taking, elevated valuations, rising global bond yields and concerns over bank funding costs. The move looks more like a valuation reset than a deterioration in DBS’s fundamentals. Singapore’s economy remains strong, while renewed global inflation and higher-rate expectations reduce the downside risk to bank margins from aggressive monetary easing. DBS also enters this environment with the strongest profitability among the local banks, making the current correction a more attractive entry after the stock fell from its S$79.05 52-week high.
KEY INSIGHTS #2
Wealth management is increasingly offsetting pressure from lower net interest margins.
2Q26 net profit rose 9% YoY to a record S$3.08B despite NIM falling 18bps to 1.87%. The key driver was non-interest income: net fees increased 25% to S$1.46B, with wealth-management fees surging 42% to a record S$919M, while wealth AUM reached S$516B, +16% in constant-currency terms. Loans also grew 8% YoY and deposits 11%, helping offset rate compression. This matters because DBS is gradually becoming less dependent on the traditional NIM cycle, with wealth, treasury customer sales and markets income providing a larger structural earnings contribution.
SGX SP
Singapore market revival, multi-asset growth, and post-correction valuation reset
KEY INSIGHTS #1
Singapore’s equity-market revival is translating directly into higher trading activity.
Singapore equities are experiencing their strongest participation cycle in years, helped by the Equities Market Review measures, stronger retail involvement and renewed institutional interest. August securities daily average value rose 35% YoY to around S$2.2B, while total securities turnover increased 29% to S$43.3B. The STI subsequently reached a record 5,828.5 in September, while combined STI ETF AUM exceeded S$6B for the first time. More importantly, activity is broadening beyond banks and index names, with nearly 220 stocks averaging more than S$100,000 of daily turnover in 9M26 versus fewer than 200 in 9M25. Higher market velocity directly supports SGX’s clearing, trading and market-data revenue.
KEY INSIGHTS #2
The recent 20% correction has reset valuation while capital returns remain strong.
S68 has fallen from above S$25 in early September to around S$20.6 on 8 October, including a 7.2% decline on 2 October following a sharp valuation reset and a JPMorgan downgrade to S$23.00. The correction leaves the shares around 27x forward earnings versus a current analyst consensus target near S$24.2. Meanwhile, FY26 total dividends reached S$0.57 per share, including a S$0.125 one-off additional dividend, supported by record earnings. With underlying trading activity still healthy, the selloff creates a cleaner entry around S$20.50 for a recovery toward S$24.50 if FY27 earnings continue to compound.
9926 HK
Ivonescimab validation, commercial acceleration, and near-term global catalysts
KEY INSIGHTS #1
Ivonescimab is increasingly demonstrating superiority over established checkpoint inhibitors.
The HARMONi-2 Phase III trial materially strengthened the case for ivonescimab as a next-generation immunotherapy standard. In first-line PD-L1-positive NSCLC, ivonescimab reduced the risk of death by 27% versus Merck’s pembrolizumab, with median overall survival of 30.8 months versus 22.6 months and an OS hazard ratio of 0.73. The benefit was even stronger in PD-L1-high patients, with an HR of 0.58. Combined with the earlier PFS advantage and multiple Chinese approvals, the data suggest PD-1/VEGF bispecific therapy can potentially take share from conventional PD-1 monotherapy across large lung-cancer indications.
KEY INSIGHTS #2
ESMO and the US FDA decision create two major catalysts within five weeks.
The Phase III HARMONi-GI1 biliary-tract cancer trial has already met its primary OS endpoint versus durvalumab plus chemotherapy, with detailed data scheduled for the ESMO Presidential Symposium on 25 October. A strong magnitude of benefit could materially broaden ivonescimab’s perceived value beyond lung cancer. This is followed by Summit Therapeutics’ US FDA PDUFA date for ivonescimab on 14 November 2026, which represents the most important validation yet of the asset outside China. With 9926 HK around HK$105 versus Nomura’s HK$138.29 target, an entry around HK$103 offers a more attractive risk-reward ahead of this dense catalyst window.
2658 HK
8-inch SiC ramp, margin normalization, and aggressive buyback support
KEY INSIGHTS #1
The transition to 8-inch SiC creates a structural growth opportunity despite near-term industry price pressure.
SiC adoption continues to broaden across EV powertrains, charging infrastructure, renewable energy and high-efficiency power conversion, while the industry is progressively shifting from 6-inch toward more cost-efficient 8-inch wafers. Tianyu is one of the few Chinese suppliers already capable of mass-producing 8-inch SiC epitaxial wafers. In 1H26, 8-inch revenue increased 40.5% YoY to RMB147.1M and overtook 6-inch revenue of RMB146.8M, helping group revenue rise 4.3% to RMB347.9M despite aggressive industry pricing. The improving product mix gives Tianyu substantial operating leverage if 8-inch demand continues scaling.
KEY INSIGHTS #2
Management is actively buying shares after the post-results collapse.
Tianyu announced an H-share repurchase programme in September covering up to 5.90M shares, equivalent to 10% of the H shares outstanding at the time, explicitly citing confidence in the company’s development prospects and valuation. Repurchases have continued repeatedly through early October, with 386,950 shares already accumulated by 6 October, including purchases at an average HK$52.15 that day. The shares have rebounded from HK$32.80 on 14 September to HK$52.00 on 7 October, so chasing the move offers less attractive risk-reward. An entry nearer HK$49.50 provides a cleaner setup for a recovery toward the HK$58 IPO price and ultimately the previous HK$63.50 high if 8-inch margins begin stabilising.
AFRM US
BNPL platform leveraged to resilient holiday spending and rising demand for payment flexibility
KEY INSIGHTS #1
Pressured consumers are preserving holiday spending through greater payment flexibility.
U.S. consumers are entering the holiday season under greater financial pressure, but spending intentions remain relatively resilient. PayPal’s September survey found 58% of Americans are more financially concerned heading into the holidays, yet 64% still expect to spend the same or more than last year; importantly, 55% have used or considered BNPL, and among that group 75% plan to use or are considering BNPL for holiday purchases. PayPal Newsroom With University of Michigan consumer sentiment also remaining depressed, the setup is less about strong consumer confidence and more about shoppers seeking ways to preserve holiday consumption while managing cash flow, which should support demand for Affirm’s instalment products.
KEY INSIGHTS #2
Expanding network and better underwriting are driving profitable scale.
Affirm continues to gain scale across consumers, merchants and payment channels, with FY26 GMV increasing 37% YoY to US$50.2bn and active consumers rising 21% to 27.8mn; in 4Q26 alone, GMV grew 36% YoY to US$14.1bn, while revenue less transaction costs reached US$589mn. SEC Its newly launched transformer-based underwriting model can approve additional eligible consumers at comparable risk levels, while recent partnerships with Antom and Crate & Barrel further expand merchant distribution ahead of the holiday season, strengthening the network effect between consumer adoption, merchant acceptance and transaction growth.
P US
AI-era storage and data-management platform leveraged to hyperscale infrastructure growth
KEY INSIGHTS #1
Hyperscale wins and data-management expansion are widening the growth opportunity.
Everpure is expanding beyond traditional enterprise storage into hyperscale infrastructure, Scale AI and modern data-management software, giving it several incremental growth engines. The company has now secured design wins with two top-five hyperscalers, with its DirectFlash architecture designed to reduce storage power, cooling and rack-space requirements, while the acquisition of 1touch and new data-management capabilities extend the platform into data discovery, governance and AI-ready data orchestration. This momentum is already visible financially, with 2Q27 revenue rising 38% YoY to US$1.2bn, subscription ARR increasing 20% to US$2.1bn, and RPO growing 44% to US$4.1bn.
KEY INSIGHTS #2
AI data-centre buildout increases the value of efficient storage and data management.
The AI infrastructure boom is driving a sharp increase in data-centre capacity, but power, cooling and physical space are increasingly becoming constraints, raising the importance of storage architectures that can deliver more capacity with lower energy and rack requirements. Everpure estimates that its DirectFlash technology can reduce storage space, power and cooling requirements by 80-90%, while enterprises moving AI workloads from pilots into production are also creating greater demand for governed, accessible and AI-ready data; this positions Everpure to benefit from both the physical expansion of AI data centres and the shift toward more sophisticated enterprise data management. Global AI-related infrastructure spending remains substantial, with projections for cumulative data-centre investment of more than US$30tn by 2050.
STOCKS
–
STOCKS
STOCKS