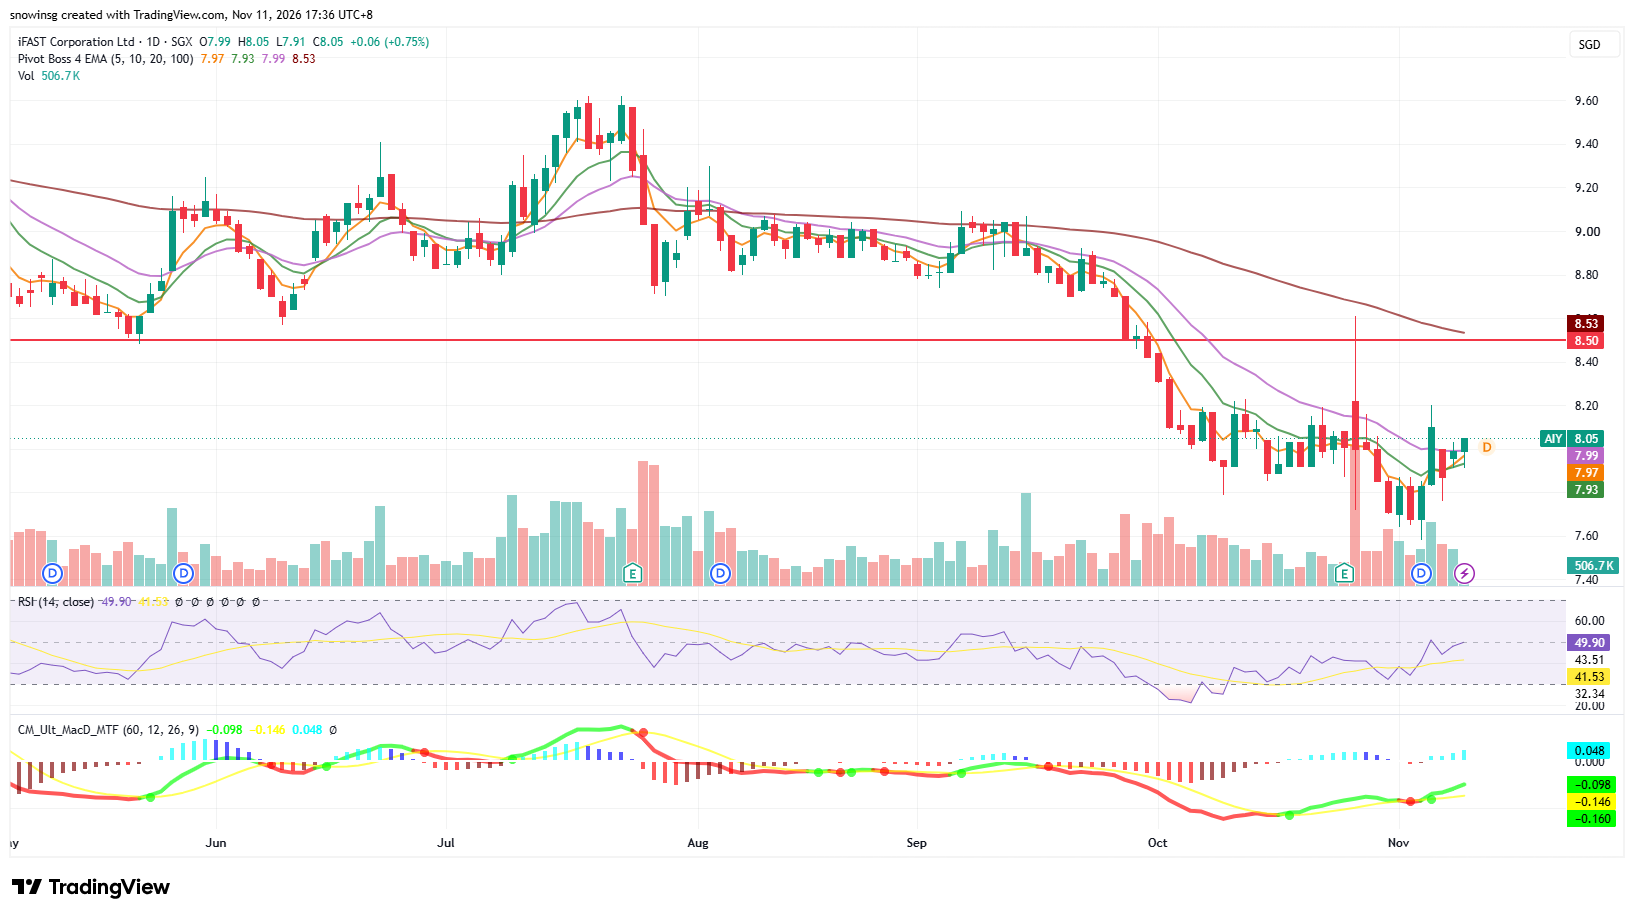
IFAST SP
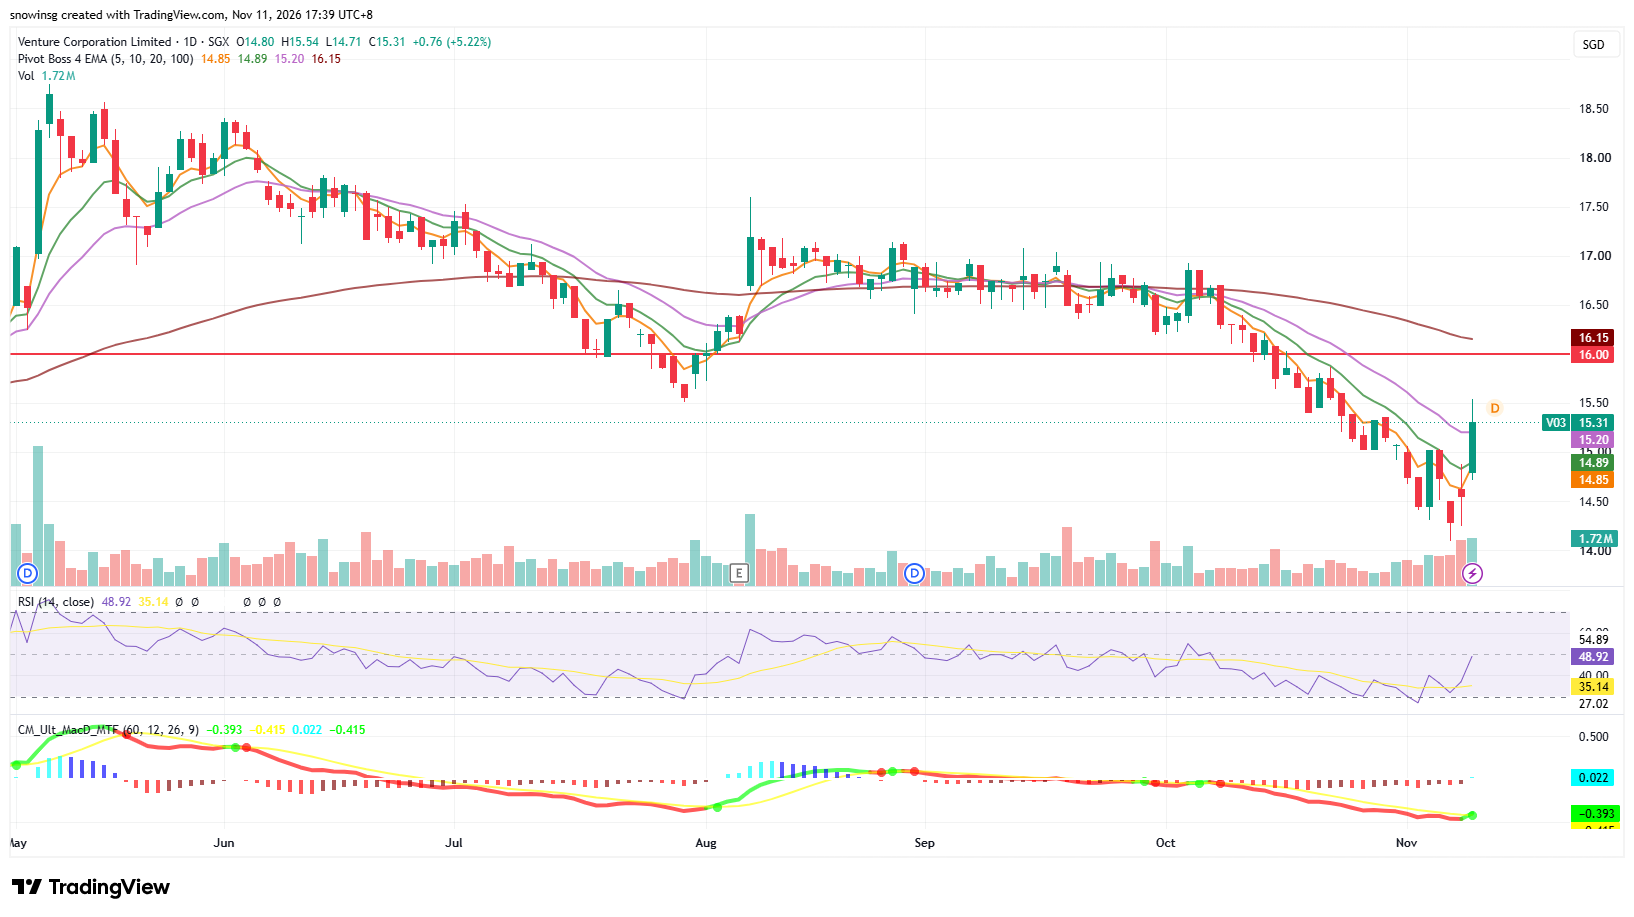
VMS SP
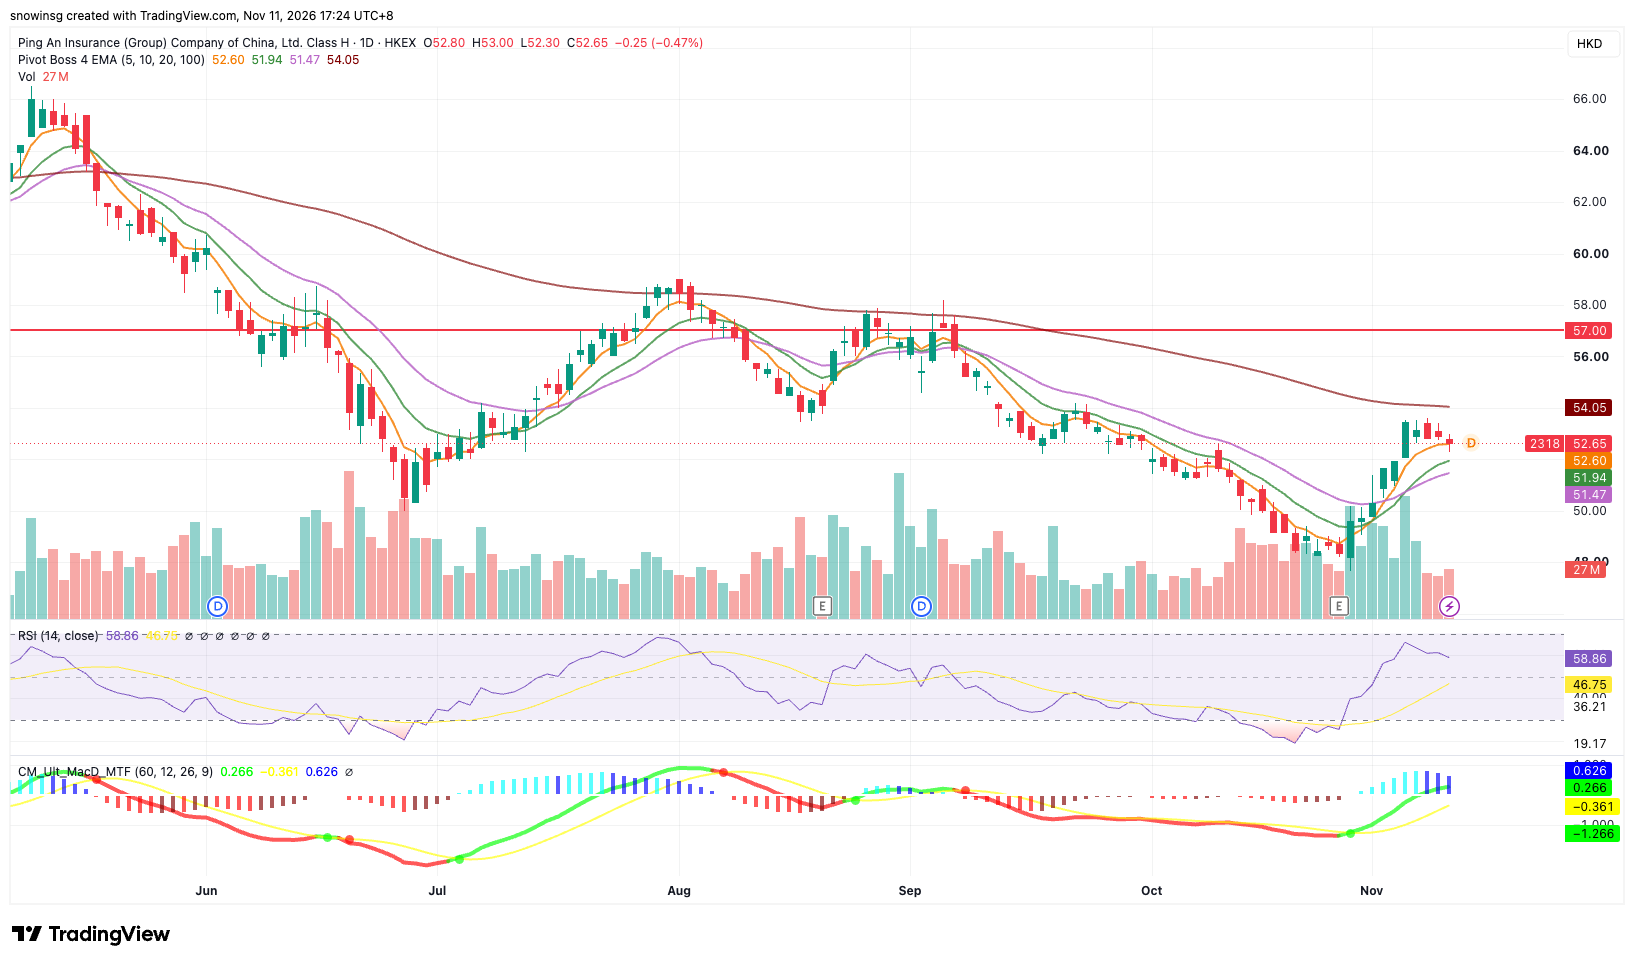
2318 HK
1299 HK
GE US
TSLA US
On Holding AG (ONON)
● 3Q26 Revenue: CHF 931.4m versus CHF 794.4m, up 17.2% YoY and 17.8% in constant currency. Revenue beat CHF 929.82m consensus by CHF 1.58m. Direct-to-consumer sales rose 25.0% to CHF 393.3m, while apparel sales grew 38.7%.
● 3Q26 EPS: Adjusted diluted EPS of CHF 0.54 versus CHF 0.43, up 25.6% YoY and CHF 0.16 above CHF 0.38 consensus. IFRS diluted EPS increased to CHF 0.48 from CHF 0.36. A CHF 52.6m U.S. tariff refund benefited profit. Gross margin was 72.6%, or 66.9% excluding the refund.
● 4Q26 Guidance: No standalone quarterly revenue or EPS guidance provided.
● FY26 Guidance: Constant-currency sales growth in the low-20% range reaffirmed, implying CHF 3.47–3.56bn at current exchange rates. Including tariff refunds, gross margin is expected around 67.5% and adjusted EBITDA margin at 21.0–21.5%. Excluding refunds, gross margin guidance increased to around 66% from at least 65%, while adjusted EBITDA margin remains 19.5–20.0%. No EPS guidance provided.
● Dividend/Share Buyback: No dividend announced. The board approved a US$1.0bn buyback programme in September, running through December 2029. No programme repurchases were made in the first nine months. Cash and cash equivalents totalled CHF 1.339bn at September-end.
● Comment: On delivered record sales and a better underlying gross margin, although the tariff refund makes the reported profit improvement look stronger than the recurring business alone. Direct-to-consumer growth of 25% and apparel growth of almost 39% show the brand is expanding beyond its original running-shoe base while increasing sales through its own channels. Full-price selling in a promotional market is encouraging, and the 66.9% gross margin excluding refunds supports management’s premium positioning. The qualification is that quarterly revenue only slightly exceeded consensus, while the comparable full-year adjusted EBITDA margin outlook stayed unchanged. The higher headline margin guide therefore provides less evidence of a lasting profit upgrade than it first appears. Investment in stores, technology, product development and new sports will need to generate repeat purchases as the business grows. Shares closed at US$34.70 on 10 November, down 7.54%, and traded at US$34.75 post-market. The selloff suggests investors expected a stronger improvement in the underlying outlook. Watch holiday sell-through, wholesale reorders, growth in apparel and Asia-Pacific, and whether higher direct sales continue to support margins after tariff refunds cease contributing. The large buyback authorisation and cash balance provide flexibility, but actual repurchases and sustained operating performance will matter more than the authorisation alone. Strong full-price demand with improved underlying profitability would support a more positive view. 4Q26 recommended trading range of US$30–42. Neutral Outlook.
昂跑控股公司(ONON)
• 2026年第三季度营收:9.314亿瑞士法郎,上年同期为7.944亿瑞士法郎,同比增长17.2%,按固定汇率计算增长17.8%。较9.2982亿瑞士法郎的市场共识高158万瑞士法郎。直营销售增长25.0%至3.933亿瑞士法郎,服装销售增长38.7%。
• 2026年第三季度每股收益:调整后摊薄每股收益为0.54瑞士法郎,上年同期为0.43瑞士法郎,同比增长25.6%,较0.38瑞士法郎的市场共识高0.16瑞士法郎。按国际财务报告准则(IFRS)计算的摊薄每股收益由0.36升至0.48瑞士法郎。5260万瑞士法郎的美国关税退款提振盈利。毛利率为72.6%,剔除退款后为66.9%。
• 2026年第四季度指引:公司未单独提供季度营收或每股收益指引。
• 2026年全年指引:重申按固定汇率计算销售增长为20%出头,按当前汇率折算,对应营收34.7亿至35.6亿瑞士法郎。包含关税退款的毛利率预计约67.5%,调整后EBITDA利润率为21.0%至21.5%。剔除退款后,毛利率指引由至少65%上调至约66%,调整后EBITDA利润率维持19.5%至20.0%。未提供每股收益指引。
• 股息与回购:未宣布股息。董事会于9月批准10亿美元回购计划,有效期至2029年12月底。前九个月未依据该计划回购股份。9月底现金及现金等价物为13.39亿瑞士法郎。
• 短评:昂跑录得创纪录销售,剔除关税退款后的毛利率也有所改善,但关税退款放大了本季度盈利增长。直营销售增长25%,服装销售增长近39%,反映品牌正从最初的跑鞋业务向外延伸,同时提高自有渠道的销售占比。在促销活动频繁的市场环境下,公司维持全价销售,表现令人鼓舞,剔除退款后66.9%的毛利率也支持其高端定位。不过,季度营收仅略高于市场共识,按可比口径计算的全年调整后EBITDA利润率指引仍未上调,因此表面上的利润率指引提升,对持续盈利改善的证明作用有限。随着业务扩大,门店、技术、产品开发及新运动品类的投入需要转化为客户持续复购。11月10日股价收于34.70美元,下跌7.54%,盘后报34.75美元。股价下跌表明市场原本期待公司更明显上调基础业务的盈利展望。后续应关注节日期间的终端销售、批发商补单、服装及亚太地区增长,以及关税退款不再贡献利润后,直营占比提升能否继续支撑毛利率。大额回购授权及现金余额提供了财务空间,但实际回购和持续的经营表现比授权本身更重要。若能维持全价销售需求并改善基础盈利能力,将支持更正面的判断。2026年第四季度建议交易区间为30至42美元。中性前景。
D-Wave Quantum Inc. (QBTS)
● 3Q26 Revenue: US$4.513m versus US$3.739m, up 20.7% YoY and approximately US$0.17m above US$4.34m consensus. Quarterly bookings fell 19% to US$1.9m, while nine-month bookings rose 611% to US$37.4m. Remaining performance obligations reached US$38.3m.
● 3Q26 EPS: GAAP loss of US$0.13/share versus US$0.41, missing US$0.12 consensus by US$0.01. Net loss narrowed to US$48.2m from US$140.0m, mainly because prior-year warrant remeasurement charges fell away. Adjusted EBITDA loss widened 83% to US$37.7m from US$20.7m.
● 4Q26 Guidance: No numerical quarterly revenue or EPS guidance provided. Management emphasised that system sales and bookings depend on the timing of large transactions.
● FY26 Guidance: No numerical full-year revenue or EPS guidance provided. Management expects system sales, quantum computing as a service, professional services and partner sales to grow in 2027, without issuing a revenue target.
● Dividend/Share Buyback: No dividend or buyback announced. Cash and marketable investment securities totalled US$503.4m at September-end. The company secured access to up to US$100m of CHIPS Act funding, subject to specified milestones.
● Comment: The small revenue beat provides limited reassurance when operating expenses are rising much faster than sales. Services and cloud access contributed growth, but the mix shifted toward lower-margin professional work, reducing GAAP gross margin to 52.9% from 71.4%. Operating expenses increased 84% to US$55.9m, and the wider adjusted EBITDA loss shows that the narrower GAAP loss mainly reflects the change in warrant accounting charges. The sharp rise in nine-month bookings and remaining performance obligations gives D-Wave a stronger commercial pipeline than a year ago. However, Q3 bookings declined, illustrating how a few large system orders can dominate reported growth. Approximately 59% of remaining performance obligations is expected to become revenue over the next twelve months, so conversion speed remains central to the earnings outlook. The cash and investments balance provides time to develop both annealing and gate-model systems, while milestone-based government funding can support development. Spending on two platforms also raises the burden on future commercial adoption. Shares closed at US$10.48 on 10 November, down 8.63%, and traded at US$10.50 post-market. Watch system acceptance, repeat cloud usage, the margin mix and the pace of operating expenditure. Larger recurring contracts accompanied by slower cash consumption would improve the case. Continued spending growth without faster revenue recognition would keep the shares dependent on technical announcements and sector sentiment. 4Q26 recommended trading range of US$8–14. Negative Outlook.
D-Wave量子公司(QBTS)
• 2026年第三季度营收:451.3万美元,上年同期为373.9万美元,同比增长20.7%,较434万美元的市场共识高约17万美元。季度新增订单金额下降19%至190万美元,前九个月累计增长611%至3740万美元。剩余履约义务金额达3830万美元。
• 2026年第三季度每股收益:GAAP每股亏损为0.13美元,上年同期亏损0.41美元,较市场预期的0.12美元亏损多0.01美元。净亏损由1.400亿美元收窄至4820万美元,主要由于上年认股权证重估费用减少。调整后EBITDA亏损由2070万美元扩大83%至3770万美元。
• 2026年第四季度指引:未提供具体的季度营收或每股收益指引。管理层强调,系统销售及新增订单金额取决于大额交易的确认时间。
• 2026年全年指引:未提供具体的全年营收或每股收益指引。管理层预计2027年系统销售、量子计算即服务、专业服务及合作伙伴销售均将增长,但未公布营收目标。
• 股息与回购:未宣布股息或回购。9月底现金及可交易投资证券合计5.034亿美元。公司获得最多1亿美元的《芯片法案》资金支持,款项取决于指定里程碑的完成情况。
• 短评:营收小幅超预期的积极作用有限,经营费用的增长速度远高于销售。专业服务及云端使用带来增长,但业务组合转向利润率较低的专业服务,令GAAP毛利率由71.4%降至52.9%。经营费用增长84%至5590万美元,调整后EBITDA亏损扩大,表明GAAP净亏损收窄主要反映认股权证会计费用的变化。前九个月新增订单及剩余履约义务大幅增长,说明公司的商业订单基础较一年前增强。不过,第三季度新增订单下降,也反映少数大型系统订单足以主导季度增长。公司预计约59%的剩余履约义务将在未来十二个月转化为收入,兑现速度仍是盈利前景的核心。现金及投资余额为退火和门模型系统的开发提供了时间,按里程碑发放的政府资金也可支持研发。同时投入两条技术路线,意味着未来商业应用需要承担更高的成本。11月10日股价收于10.48美元,下跌8.63%,盘后报10.50美元。后续应关注系统验收、云端服务的重复使用、收入组合对毛利率的影响,以及经营支出增长速度。若能签下规模更大的持续性合同,并降低现金消耗,投资前景将改善。若支出继续增长而收入确认未加快,股价仍将较依赖技术公告及板块情绪。2026年第四季度建议交易区间为8至14美元。负面前景。
Sea Limited (SE)
● 3Q26 Revenue: US$8.582bn versus US$5.986bn, up 43.4% YoY and approximately US$500m above US$8.08bn consensus. Shopee revenue grew 41.3% to US$6.1bn, Monee revenue grew 63.9% to US$1.6bn, and Garena revenue grew 28.6% to US$840.1m.
● 3Q26 EPS: GAAP diluted EPS of US$0.78 versus US$0.59, up 32.2% YoY and US$0.01 below US$0.79 consensus cited by Seeking Alpha. Net income rose 34.0% to US$502.5m. Group adjusted EBITDA increased 28.9% to US$931.3m.
● 4Q26 Guidance: No standalone group revenue or EPS guidance provided.
● FY26 Guidance: Management reiterated approximately 25% Shopee gross merchandise value growth and around US$1.0bn of Shopee adjusted EBITDA. These are Shopee targets. No full-year consolidated revenue or EPS guidance provided.
● Dividend/Share Buyback: No dividend announced. Sea repurchased 11.1m shares for US$997.2m under its existing US$1.0bn programme as of 10 November. The board approved an additional US$1.0bn buyback authorisation on 9 November, without an expiry date.
● Comment: Sea’s three businesses continue to grow, but the revenue beat is stronger than the improvement in group profitability. Shopee’s core marketplace revenue rose 51%, supported by transaction fees and advertising, and adjusted EBITDA increased 45% to US$269m. This supports the view that the platform can improve monetisation while investing in fulfilment, membership and content. Monee adds another growth engine, although its consumer and SME loan portfolio grew 60% to US$12.6bn. Credit-loss provisions increased 82.3% to US$681.5m, and the ratio of loans more than ninety days overdue rose to 1.3% from 1.1%. Those figures warrant close attention as lending expands beyond Shopee users. Garena remains profitable, but quarterly bookings grew only 6%, slower than recognised revenue, making bookings and paying-user trends important for subsequent quarters. At group level, adjusted EBITDA grew more slowly than revenue, so investors still need evidence that expansion will produce stronger margins after credit costs and investment. Shares closed at US$76.80 on 10 November, down 1.49%, after trading as high as US$85.16, and were US$76.66 post-market. The reversal suggests the sales beat and renewed buyback were insufficient to settle concerns about profit conversion. Watch Shopee’s holiday-season economics, advertising growth, loan vintages and provision coverage, alongside Garena bookings. Better lending returns with stable credit quality and stronger marketplace margins would support an upgrade. 4Q26 recommended trading range of US$68–95. Neutral Outlook.
冬海集团(SE)
• 2026年第三季度营收:85.82亿美元,上年同期为59.86亿美元,同比增长43.4%,较80.8亿美元的市场共识高约5亿美元。Shopee营收增长41.3%至61亿美元,Monee营收增长63.9%至16亿美元,Garena营收增长28.6%至8.401亿美元。
• 2026年第三季度每股收益:GAAP摊薄每股收益为0.78美元,上年同期为0.59美元,同比增长32.2%,较Seeking Alpha引用的0.79美元共识低0.01美元。净利润增长34.0%至5.025亿美元,集团调整后EBITDA增长28.9%至9.313亿美元。
• 2026年第四季度指引:未单独提供集团季度营收或每股收益指引。
• 2026年全年指引:管理层重申Shopee商品交易总额预计增长约25%,Shopee调整后EBITDA约10亿美元。上述目标适用于Shopee业务。未提供集团全年合并营收或每股收益指引。
• 股息与回购:未宣布股息。截至11月10日,公司依据原有10亿美元回购计划已购回1110万股,耗资9.972亿美元。董事会于11月9日追加10亿美元回购授权,无到期日。
• 短评:冬海三大业务持续增长,但营收超预期的幅度明显强于集团盈利改善。Shopee核心平台营收增长51%,受益于交易收费及广告业务,调整后EBITDA增长45%至2.69亿美元,支持平台在投资履约、会员及内容业务的同时提高变现能力。Monee提供了另一项增长来源,但其消费者及中小企业贷款余额增长60%至126亿美元。信贷损失拨备增长82.3%至6.815亿美元,逾期超过九十天的贷款比例由1.1%升至1.3%。随着贷款业务扩展至Shopee以外的用户,这些指标需要持续关注。Garena仍有较强盈利能力,但季度预订额仅增长6%,低于已确认营收的增幅,因此预订额和付费用户趋势将影响后续季度表现。集团调整后EBITDA增速低于营收,投资者仍需看到扣除信贷成本及扩张投入后,增长能够带来更强的利润率。11月10日股价一度升至85.16美元,最终收于76.80美元,下跌1.49%,盘后报76.66美元。冲高回落表明营收超预期及追加回购仍不足以消除市场对利润转化的担忧。后续应关注Shopee节日期间的盈利表现、广告增长、不同放款批次的信贷质量及拨备覆盖情况,以及Garena预订额。如果贷款收益改善、信贷质量稳定,且平台利润率提升,将支持上调前景。2026年第四季度建议交易区间为68至95美元。中性前景。
Rigetti Computing, Inc. (RGTI)
● 3Q26 Revenue: US$1.411m versus US$1.947m, down 27.5% YoY and approximately US$2.29m below US$3.70m consensus. Nine-month revenue increased to US$10.949m from US$5.220m.
● 3Q26 EPS: Non-GAAP diluted loss of US$0.06/share versus US$0.03, missing the US$0.05 consensus loss by US$0.01. GAAP diluted loss narrowed to US$0.08 from US$0.62. GAAP net loss of US$3.1m benefited from a US$25.3m warrant valuation gain, while non-GAAP net loss widened to US$20.5m from US$10.7m.
● 4Q26 Guidance: No standalone quarterly revenue or EPS range provided. Management expects C-DAC customer acceptance and the associated revenue recognition during Q4.
● FY26 Guidance: Revenue expected to be approximately US$20m, below US$22.9m consensus, conditional on Q4 C-DAC acceptance. No EPS guidance provided. The next major technology target is a system with more than 300 qubits and approximately 99.7% median two-qubit gate fidelity by mid-2028.
● Dividend/Share Buyback: No dividend or buyback announced. Cash, cash equivalents and available-for-sale investments totalled US$497.1m, with no debt. Nine-month operating cash outflow was US$49.1m and purchases of property and equipment were US$42.6m. A CHIPS Act award of up to US$100m is tied to research programmes and includes a minority government equity stake.
● Comment: Rigetti made a measurable technical advance, but commercial revenue remains small and uneven. Achieving 99.5% median two-qubit fidelity on the 108-qubit system supports the chiplet architecture and provides a firmer base for the next stage of development. It still leaves substantial work before the company can demonstrate a scalable, economically useful advantage for customers. The revenue miss and below-consensus annual outlook put immediate focus on C-DAC acceptance. With only US$10.9m recorded in the first nine months, reaching approximately US$20m for the year requires a pronounced Q4 increase, exposing the result to a single customer milestone. The narrow GAAP loss gives an incomplete picture of underlying spending because it includes a large warrant valuation gain. The wider non-GAAP loss and US$33.2m operating loss show that development costs remain far above current sales. Cash and investments of US$497.1m and the absence of debt reduce near-term financing pressure. Government research funding can assist the roadmap, while its conditions and equity component also matter to shareholders. Shares closed at US$12.15 on 10 November, down 6.39%, and traded at US$11.35 post-market. Watch customer acceptance, paid system deployments, gate fidelity across larger systems and capital spending. Meeting the next hardware targets alongside repeat commercial orders would improve confidence. Further revenue delays would reinforce the gap between technical progress and shareholder earnings. 4Q26 recommended trading range of US$8–15. Negative Outlook.
Rigetti量子计算公司(RGTI)
• 2026年第三季度营收:141.1万美元,上年同期为194.7万美元,同比下降27.5%,较370万美元的市场共识低约229万美元。前九个月营收由522.0万美元增至1094.9万美元。
• 2026年第三季度每股收益:非GAAP摊薄每股亏损为0.06美元,上年同期亏损0.03美元,较市场预期的0.05美元亏损多0.01美元。GAAP摊薄每股亏损由0.62美元收窄至0.08美元。GAAP净亏损为310万美元,受益于2530万美元的认股权证估值收益,非GAAP净亏损则由1070万美元扩大至2050万美元。
• 2026年第四季度指引:未单独提供季度营收或每股收益区间。管理层预计C-DAC客户验收及相关收入确认将在第四季度完成。
• 2026年全年指引:营收预计约2000万美元,低于2290万美元的市场共识,前提是C-DAC在第四季度完成验收。未提供每股收益指引。下一项主要技术目标是在2028年中前推出超过300量子比特、双量子比特门中位保真度约99.7%的系统。
• 股息与回购:未宣布股息或回购。现金、现金等价物及可供出售投资合计4.971亿美元,无债务。前九个月经营现金净流出4910万美元,购置物业及设备支出4260万美元。最多1亿美元的《芯片法案》资助与研发项目挂钩,政府同时取得少数股权。
• 短评:Rigetti取得了可量化的技术进展,但商业收入规模仍小,季度波动也较大。108量子比特系统达到99.5%的双量子比特门中位保真度,支持其芯粒架构,并为下一阶段开发提供更扎实的基础。不过,公司距离证明能够大规模运行并为客户创造经济价值的量子优势,仍有大量工作需要完成。营收不及预期及低于市场共识的全年展望,使短期焦点集中在C-DAC验收。前九个月仅确认1090万美元收入,要达到全年约2000万美元,第四季度必须显著增长,因此业绩对单个客户里程碑较为敏感。GAAP净亏损较小,部分源于大额认股权证估值收益,未完整反映基础支出压力。非GAAP亏损扩大及3320万美元的经营亏损,表明研发成本仍远高于当前销售额。4.971亿美元现金及投资和无债务状态缓解了近期融资压力。政府研发资金可协助推进技术路线,但资助条件及股权安排也影响股东利益。11月10日股价收于12.15美元,下跌6.39%,盘后报11.35美元。后续应关注客户验收、付费系统部署、更大系统的门保真度及资本支出。硬件目标达成并获得重复商业订单,将增强信心。若收入继续延迟,则会扩大技术进步与股东盈利之间的距离。2026年第四季度建议交易区间为8至15美元。负面前景。
CoreWeave, Inc. (CRWV)
● 3Q26 Revenue: US$3.661bn versus US$1.365bn, up 168.2% YoY and approximately US$101m above US$3.56bn Bloomberg consensus. Revenue increased US$1.086bn sequentially. Revenue backlog reached US$132.5bn.
● 3Q26 EPS: GAAP diluted loss of US$1.27/share versus US$0.22, US$0.19 narrower than the US$1.46 loss expected in Bloomberg consensus. GAAP net loss widened to US$709m from US$110m. Adjusted operating income increased to US$379m from US$217m, while quarterly net interest expense rose to US$846m from US$310m.
● 4Q26 Guidance: No standalone quarterly revenue or EPS range provided. Interest expense expected at US$1.05–1.15bn. Management expects approximately US$9bn in customer prepayments and deposits over the next three months.
● FY26 Guidance: Revenue raised to US$13.0–13.3bn from US$12.4–13.2bn. Adjusted operating income raised to US$1.275–1.375bn, a 26% midpoint increase. Capital expenditure guidance increased to US$37–39bn from US$35–39bn. Year-end annualised revenue run rate raised to US$20–21bn, with active power still expected to exceed 1.85 GW.
● Dividend/Share Buyback: No dividend or buyback announced. The company established an at-the-market programme to issue up to 35m shares and raised approximately US$4.2bn through convertible notes. Quarterly operating cash flow was US$1.975bn, while cash purchases of property and equipment, including capitalised software, were US$9.441bn. Cash and cash equivalents totalled US$4.122bn.
● Comment: CoreWeave delivered a substantial sequential revenue increase and reached a double-digit adjusted operating margin earlier than planned. This supports management’s case that contracted demand can translate into better operating performance as new capacity becomes active. The US$132.5bn backlog gives long-term visibility, although revenue recognition remains conditional on infrastructure delivery and service availability. Funding the build-out remains the main constraint on shareholder returns. Quarterly net interest expense was more than twice adjusted operating income, and the Q4 interest guide signals a further increase. Operating cash flow was positive but included substantial growth in deferred revenue, while cash equipment purchases were much larger. Customer prepayments help finance deployment and also commit the company to delivering future service. The higher capital spending guide can bring revenue forward if projects arrive on time, but delays, higher financing costs or lower utilisation could weaken returns on that investment. Shares closed at US$48.73 on 10 November, down 0.51%, then rose to US$52.58 post-market, up 7.90% from the close. The market welcomed the stronger outlook, while the equity programme and convertible funding leave dilution relevant. Watch capacity activation, customer concentration, pricing on renewed contracts, prepayment receipts and interest coverage. Sustained operating improvements with a narrowing funding gap would support a more positive view, while reliance on repeated financing keeps the outlook balanced. 4Q26 recommended trading range of US$42–68. Neutral Outlook.
CoreWeave公司(CRWV)
• 2026年第三季度营收:36.61亿美元,上年同期为13.65亿美元,同比增长168.2%,较彭博35.6亿美元的市场共识高约1.01亿美元。营收环比增加10.86亿美元,收入积压订单达1325亿美元。
• 2026年第三季度每股收益:GAAP摊薄每股亏损为1.27美元,上年同期亏损0.22美元,较彭博市场共识的1.46美元亏损少0.19美元。GAAP净亏损由1.10亿美元扩大至7.09亿美元。调整后经营利润由2.17亿美元增至3.79亿美元,季度净利息费用由3.10亿美元升至8.46亿美元。
• 2026年第四季度指引:未单独提供季度营收或每股收益区间。利息费用预计为10.5至11.5亿美元。管理层预计未来三个月将收到约90亿美元的客户预付款及保证金。
• 2026年全年指引:营收由124至132亿美元上调至130至133亿美元。调整后经营利润上调至12.75至13.75亿美元,中值提高26%。资本支出指引由350至390亿美元提高至370至390亿美元。年底年化营收运行水平上调至200至210亿美元,投入运行的电力容量仍预计超过1.85吉瓦。
• 股息与回购:未宣布股息或回购。公司设立最多发行3500万股的市价发行计划,并通过可转换票据融资约42亿美元。季度经营现金流为19.75亿美元,购置物业及设备(含资本化软件)的现金支出为94.41亿美元。现金及现金等价物为41.22亿美元。
• 短评:CoreWeave营收环比大幅增长,并提前实现两位数的调整后经营利润率,支持管理层关于新增容量投入运行后,已签约需求能转化为更好经营表现的判断。1325亿美元的收入积压订单提供了长期可见性,但收入确认仍取决于基础设施交付和服务可用性。为扩建提供资金仍是股东回报面临的主要约束。季度净利息费用超过调整后经营利润的两倍,第四季度利息指引意味着负担将进一步上升。经营现金流为正,但包含递延收入的大幅增加,而设备现金支出明显更高。客户预付款有助于支持部署,同时也要求公司履行未来服务承诺。如果项目按时落地,提高资本支出可加快收入兑现。但交付延迟、融资成本上升或利用率下降,都可能削弱投资回报。11月10日股价收于48.73美元,下跌0.51%,盘后升至52.58美元,较收盘上涨7.90%。市场欢迎更强的业绩展望,但增发计划及可转债融资意味着股份摊薄仍需关注。后续应观察容量投入运行、客户集中度、续约定价、客户预付款到账及利息覆盖能力。若经营持续改善且融资缺口收窄,将支持更正面的判断。对持续融资的依赖使当前前景保持中性。2026年第四季度建议交易区间为42至68美元。中性前景。