SGX SP
Defensive capital rotation and rising equity inflows support trading activity and earnings growth
KEY INSIGHTS #1
Singapore’s relative stability attracts capital amid global market uncertainty.
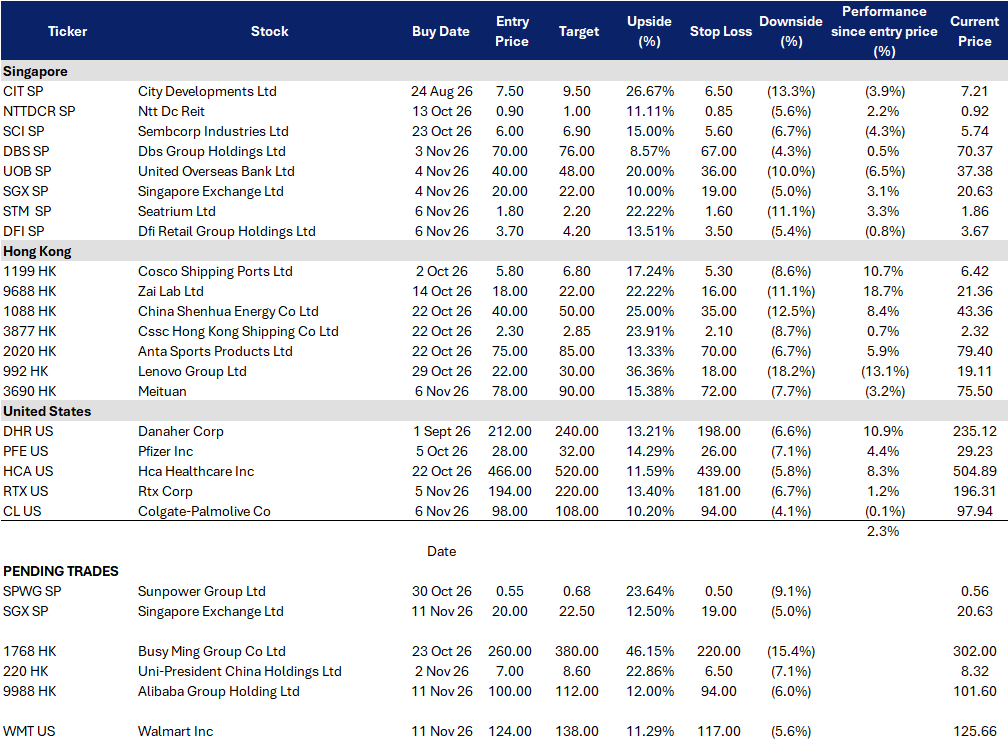
Amid heightened geopolitical tensions, concerns over elevated AI valuations and persistent global market volatility, investors may increasingly seek diversification into relatively stable and established financial markets such as Singapore. This trend is supported by record S$2.2bn inflows into Singapore equity funds in 3Q26, more than double the previous quarter, while STI ETFs recorded S$293mn in net inflows in September. Singapore’s reputation as a stable financial hub, alongside its relatively defensive equity market composition, could continue attracting regional and international capital, supporting market liquidity and trading activity on SGX.
KEY INSIGHTS #2
Rising trading volumes, market reforms and new gold trading opportunities support earnings growth.
SGX is well-positioned to benefit from sustained capital inflows and increased market participation, with 3Q26 securities turnover rising 31% YoY to S$132bn, while securities daily average value increased 33% YoY to S$2.0bn. Furthermore, MAS’ S$6.5bn Equity Market Development Programme (EQDP) aims to deepen market liquidity and attract institutional investment into Singapore equities, supporting transaction and clearing revenues. Separately, MAS’ recent launch of a 500-tonne gold custody facility for foreign central banks, alongside SGX’s planned OTC gold-clearing services in Q1 2027 and physically deliverable Gold Kilobar Futures in Q2 2027, further reinforces Singapore’s ambitions as a regional gold trading hub. These initiatives could unlock additional commodities trading and clearing opportunities for SGX, supporting longer-term revenue diversification.
DFI SP
Asian retail recovery play
KEY INSIGHTS #1
Improving Singapore retail spending supports health & beauty demand.
Singapore retail sales accelerated to +1.7% YoY in September 2026, from +0.8% in August, while sales excluding motor vehicles rose a stronger 2.5%. Importantly for DFI, cosmetics, toiletries and medical goods sales increased 6.0% YoY, providing a supportive backdrop for Guardian, while total online penetration rose to 17.7% of retail sales. Interestingly, Singapore mini-mart and convenience-store sales declined 5.6% YoY, yet DFI’s Singapore Convenience business delivered 11% LFL growth in 3Q26, suggesting DFI is gaining share through higher traffic and differentiated categories rather than relying purely on market growth.
KEY INSIGHTS #2
Stronger profit growth, digital scaling and Starbucks reshape the earnings profile.
DFI’s execution strengthened further in 3Q26, with underlying subsidiary sales from continuing operations rising 4% YoY and underlying profit increasing 17%, driven by stronger Health & Beauty and Home Furnishings profitability and lower administrative costs. Health & Beauty sales rose 7%, digital profitability nearly tripled YoY, and DFI raised FY26 underlying profit guidance to US$295–305mn; the acquisition of Starbucks operations across seven Asian markets adds another potential growth pillar, while the FY27 dividend payout ratio will rise to 80% from 70% in FY26.
9988 HK
Singles’ Day provides near-term catalyst while AI and cloud growth drive medium-term upside
KEY INSIGHTS #1
Singles’ Day supports selective consumption despite subdued Chinese retail demand.
China’s consumption environment remains subdued, with retail sales growing just 1.1% YoY in September 2026, reflecting cautious household spending. Nevertheless, the ongoing Singles’ Day shopping festival, which has attracted over one million participating brands on Alibaba’s Tmall platform, could provide a near-term boost to e-commerce activity through promotional spending and higher transaction volumes. While the festival’s impact has moderated amid increasingly price-conscious consumers, early sales trends indicate selective strength in technology-related products, with AI laptop sales on Taobao and Tmall surging over 300% YoY during the initial promotional period. This could support Alibaba’s e-commerce activity and advertising monetisation, although intense promotional competition may constrain profitability.
KEY INSIGHTS #2
Accelerating cloud revenue and AI monetisation support earnings diversification.
Alibaba’s AI and cloud businesses continue to demonstrate strong growth, with AI Cloud and Compute Services revenue rising 45% YoY to RMB48.4bn in the June 2026 quarter, while AI-related product revenue achieved triple-digit growth for the 12th consecutive quarter. Cloud adjusted EBITA also increased 133% YoY, with margins expanding to approximately 12%, demonstrating improving AI monetisation and operating leverage. Supported by its Qwen AI models, proprietary semiconductor capabilities and established cloud infrastructure, Alibaba could benefit from sustained enterprise AI demand, partially offsetting weakness in its domestic e-commerce business and supporting a potential valuation re-rating.
3690 HK
Local-commerce leader combining resilient service consumption with AI-driven efficiency
KEY INSIGHTS #1
Service consumption remains more resilient than headline retail growth.
China’s overall consumption environment remains subdued, but services continue to outperform goods, providing a more favourable backdrop for Meituan. In 9M26, service retail sales rose 5.0% YoY and online service sales increased 5.3%, compared with much weaker headline retail growth, supporting continued demand across food delivery, in-store services, travel and instant retail as consumption increasingly shifts toward experiences and digitally enabled services.
KEY INSIGHTS #2
AI investment can deepen merchant monetisation and improve platform efficiency.
Meituan is increasingly using AI as an operating tool rather than simply pursuing standalone model development. Its newly launched LongCat-2.5, a 1.6tn-parameter multimodal model trained entirely on domestic chips, is designed for long-horizon agentic tasks and can help merchants analyse channel profitability, identify growth bottlenecks and recommend resource allocation, potentially improving merchant ROI and strengthening Meituan’s value proposition across its local-commerce ecosystem. This builds on Meituan’s already significant AI investment and provides another lever for improving recommendations, merchant operations and platform efficiency as competition becomes more rational.
WMT US
Defensive capital rotation and resilient grocery demand complemented by year-end holiday spending
KEY INSIGHTS #1
Defensive sector rotation and resilient essential spending amid market uncertainty.
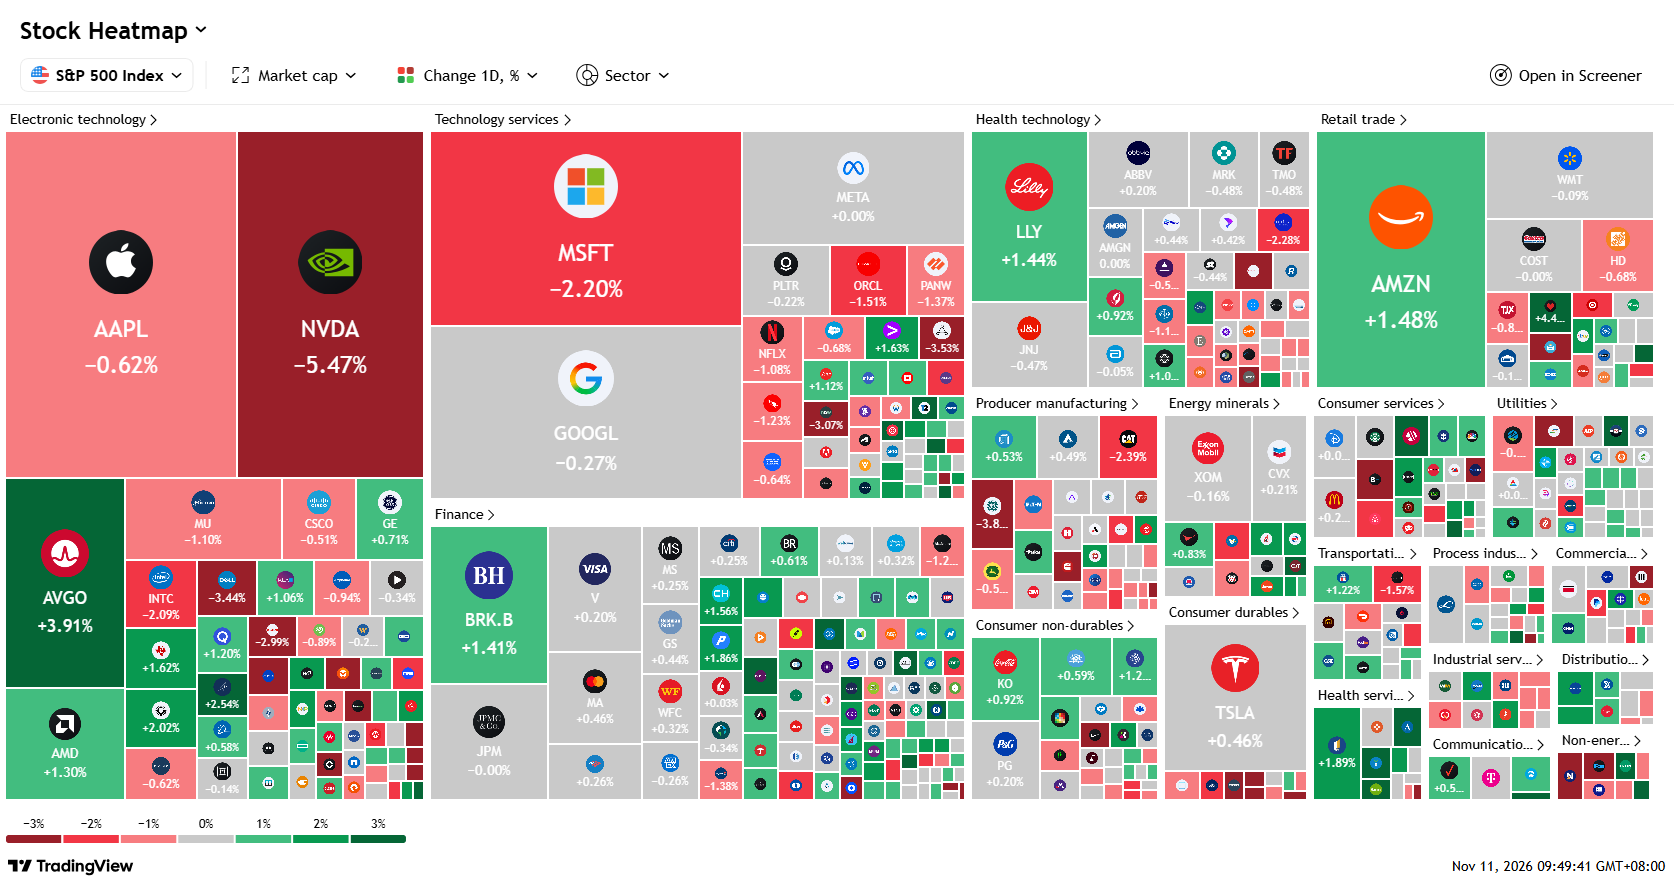
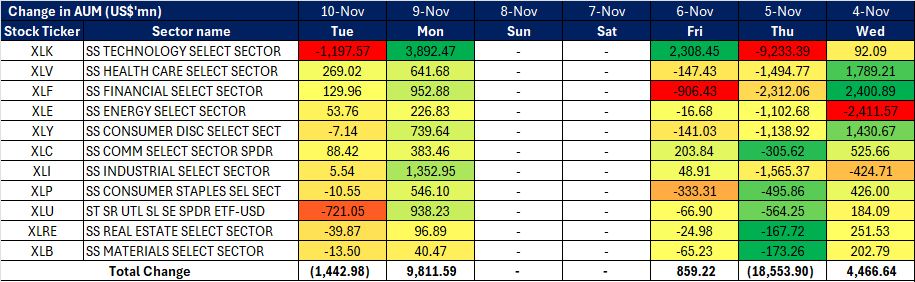
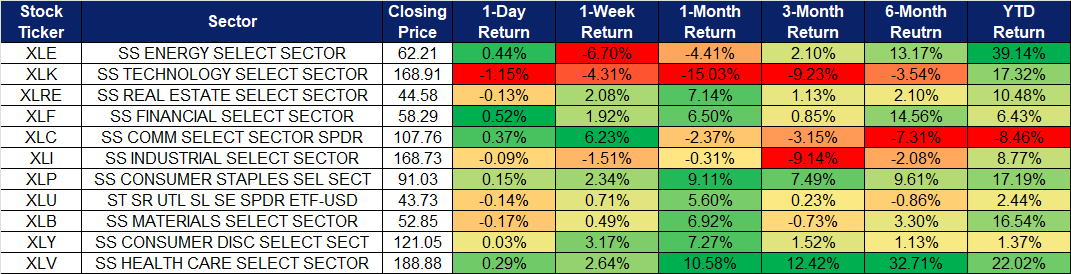
Amid heightened market volatility and concerns over elevated AI valuations, investors are increasingly rotating towards defensive sectors offering greater earnings visibility and resilient consumer demand. Global consumer staples equities gained 10.6% in October 2026, their strongest monthly performance since 1998, reflecting growing demand for defensive exposure. Walmart is well-positioned to benefit from this shift, supported by its extensive grocery business and value-oriented positioning. As consumers become increasingly price-conscious, Walmart’s competitive pricing and essential product offerings could support sustained customer traffic and market-share gains, providing relatively resilient earnings amid economic uncertainty.
KEY INSIGHTS #2
Grocery leadership and holiday shopping catalysts support near-term sales growth.
Walmart’s extensive distribution network, economies of scale and omnichannel capabilities position it to capture additional spending during the upcoming Thanksgiving and Black Friday shopping season. With US$285.5bn in US grocery sales in FY2026, the company benefits from recurring demand for food and household essentials. Furthermore, Walmart has announced three major promotional events running from 12 November to 2 December, encompassing early Black Friday deals, the main Black Friday shopping period and Cyber Monday. These promotions could attract value-conscious shoppers across groceries, electronics and household merchandise, supporting sales volumes, e-commerce growth and market-share gains heading into the year-end holiday season.
CL US
Defensive consumer-staples compounder anchored by global oral-care leadership
KEY INSIGHTS #1
Essential household categories offer resilience as consumer purchasing power weakens.
U.S. consumers remain under pressure, with the University of Michigan Consumer Sentiment Index at 48.0 in October, down 10% YoY, while one-year inflation expectations rose to 4.7% and purchasing power remained a key concern. Against this backdrop, everyday necessities such as toothpaste, personal care and pet nutrition should remain comparatively resilient because purchase frequency is less discretionary, supporting Colgate’s defensive earnings profile even as households become more selective elsewhere.
KEY INSIGHTS #2
Oral-care leadership, margin recovery and consistent dividends support defensive returns.
Colgate continues to combine category leadership with improving operating leverage: 3Q26 net sales rose 4.6% YoY, organic sales increased 3.6%, Base Business EPS grew 7%, and gross margin expanded 90bps to 60.3%. Its global toothpaste and manual-toothbrush shares remain dominant at 41.4% and 33.1%, respectively, while management continues to invest behind premium, science-based innovation and advertising; alongside this, Colgate has increased its dividend for 63 consecutive years, reinforcing the consistency of shareholder returns and its defensive investment profile.
STOCKS
STOCKS
STOCKS