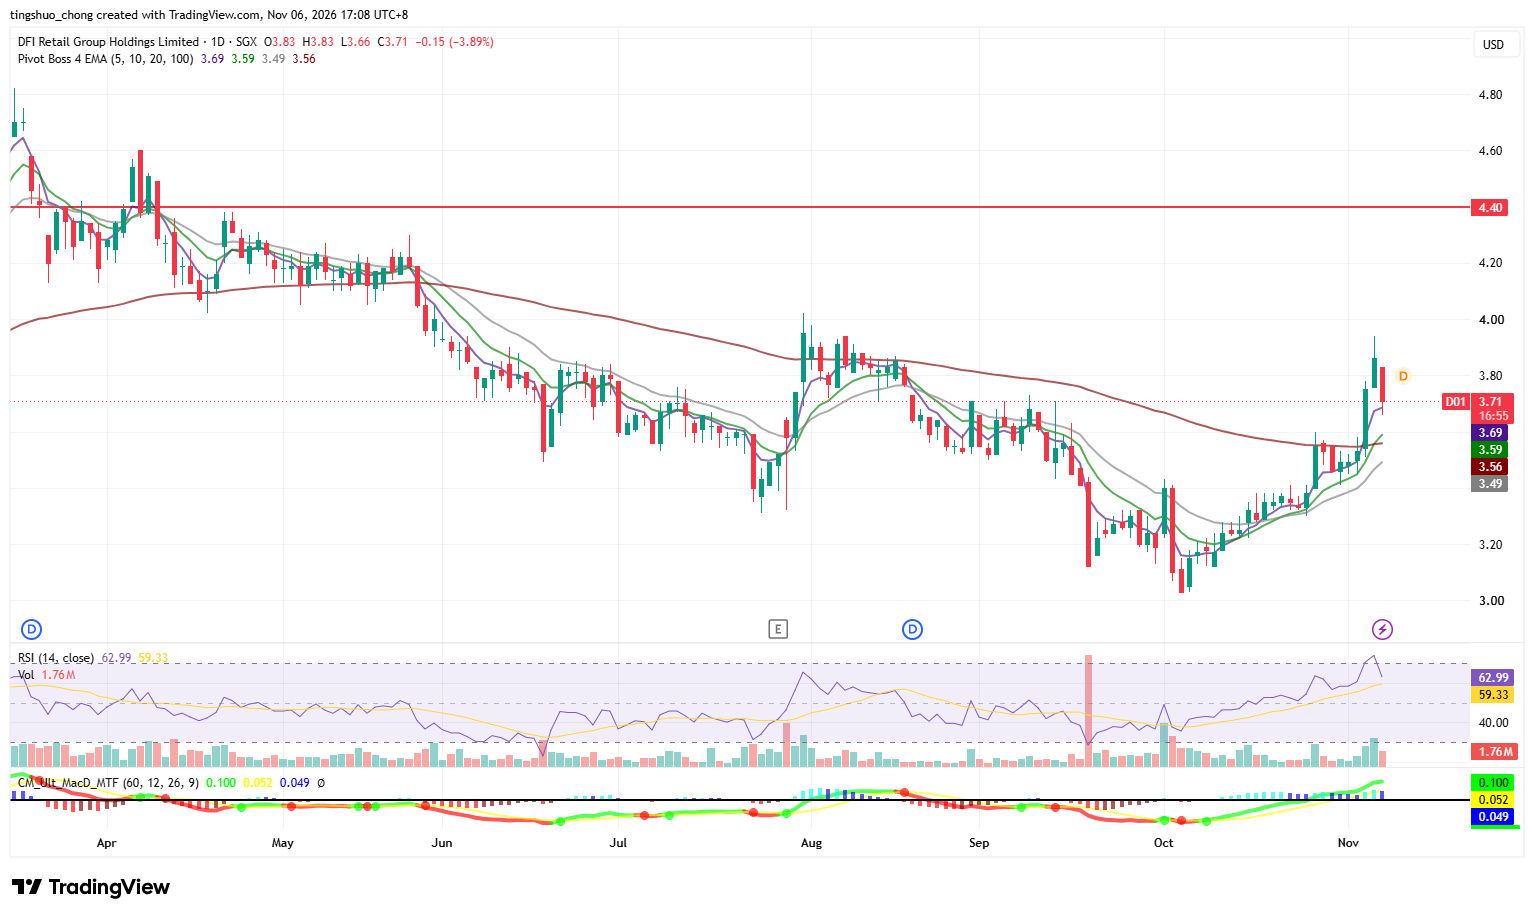
DFI SP
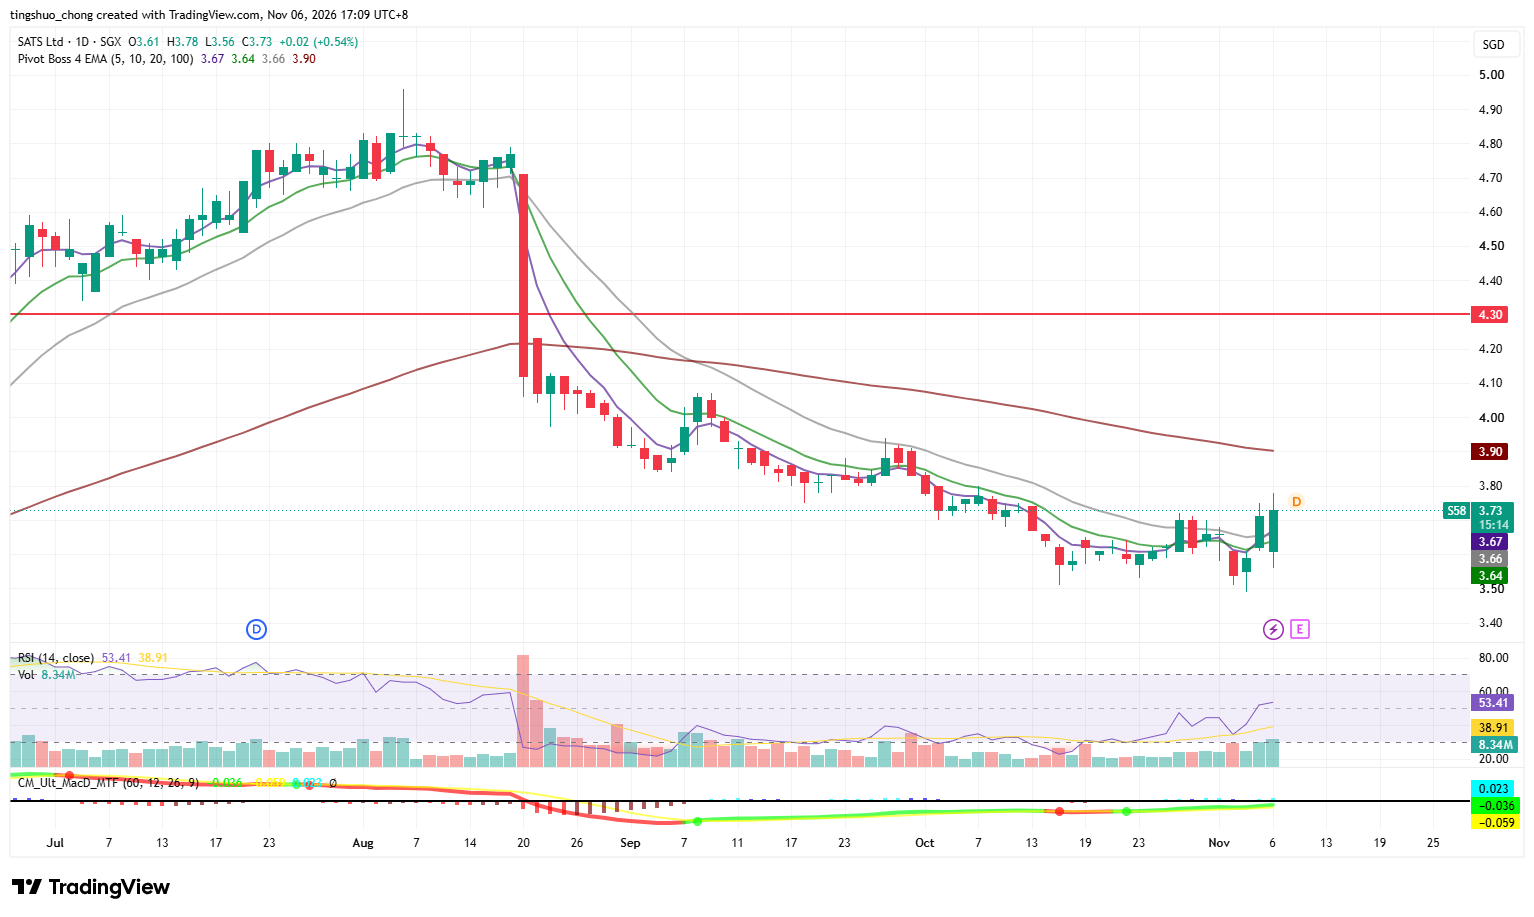
SATS SP
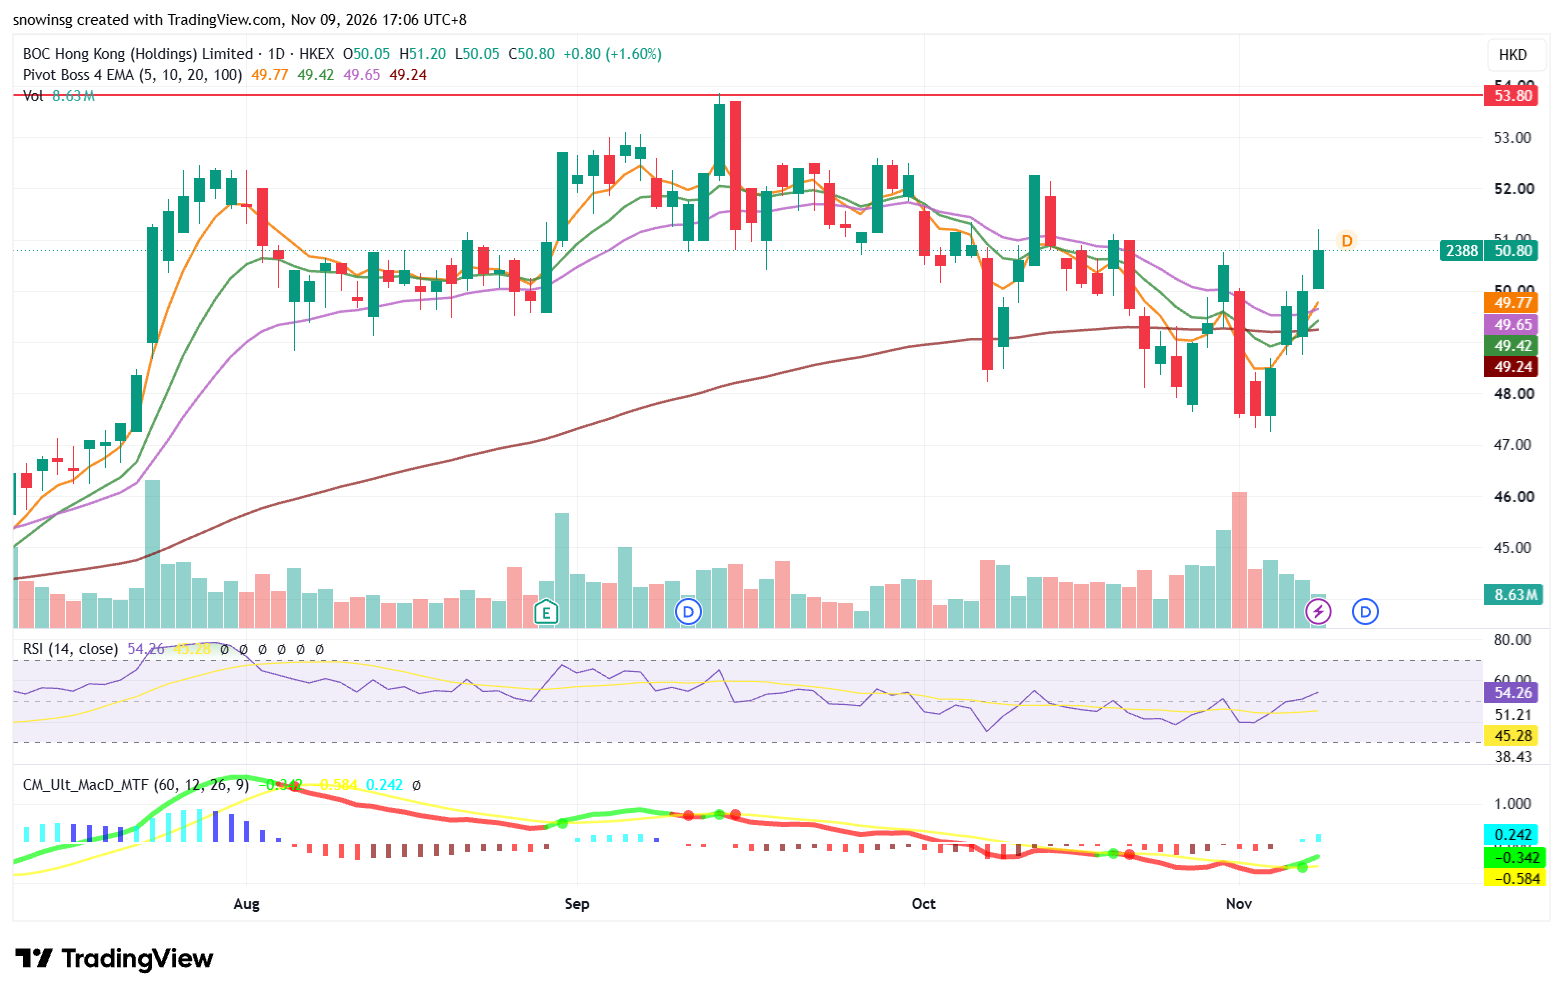
2388 HK
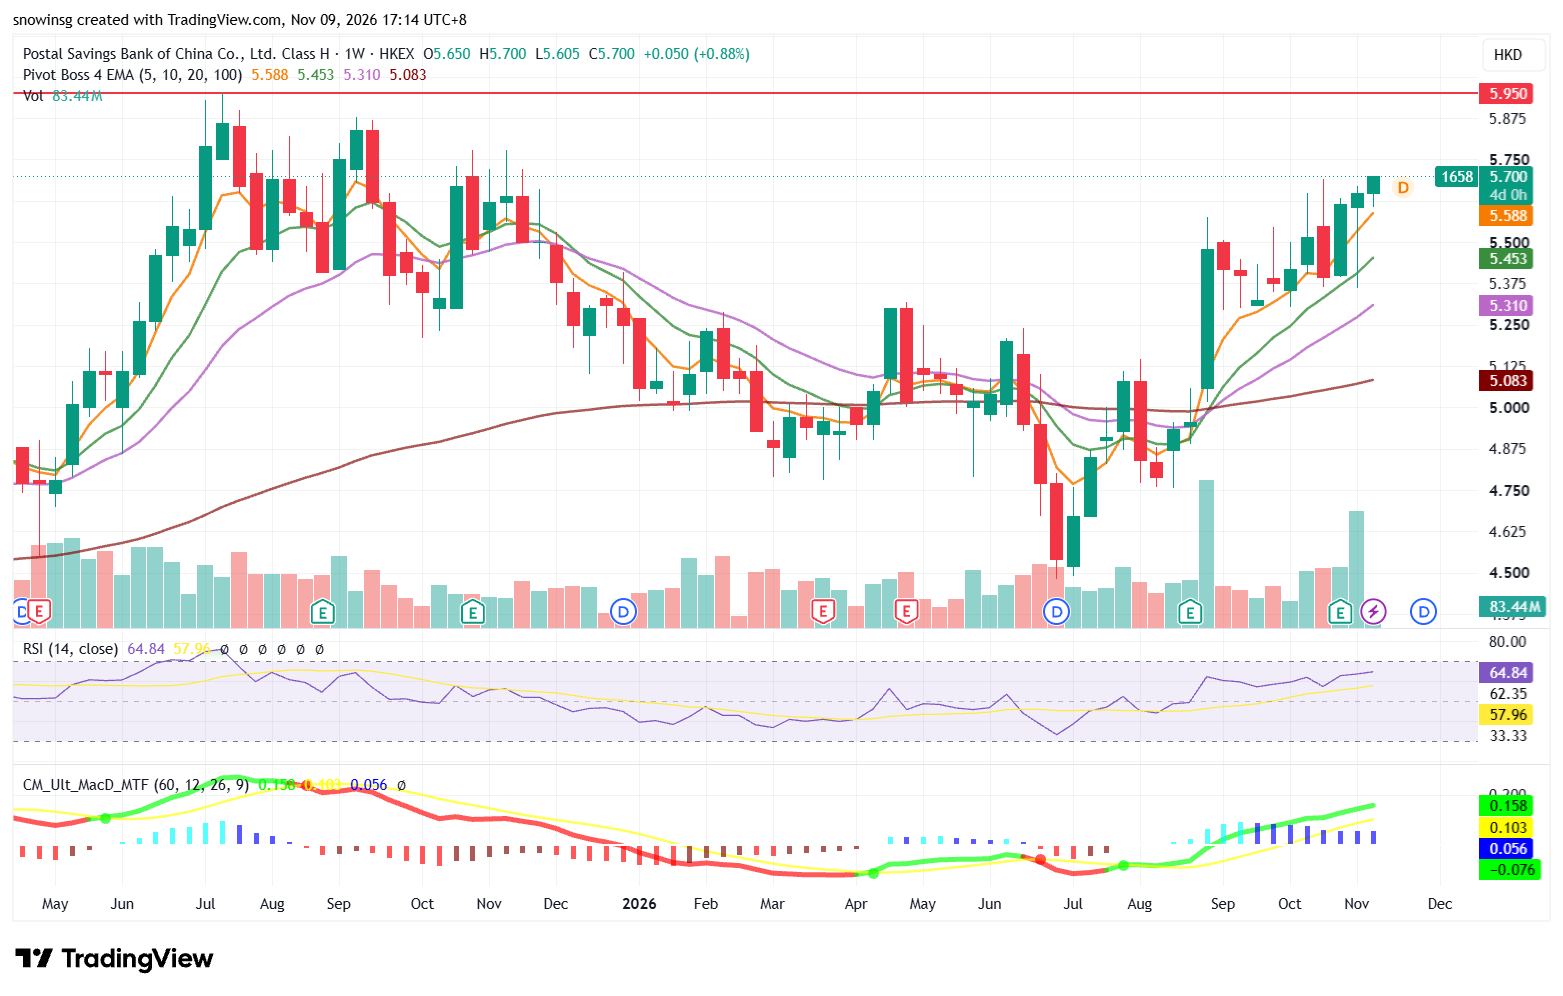
1658 HK
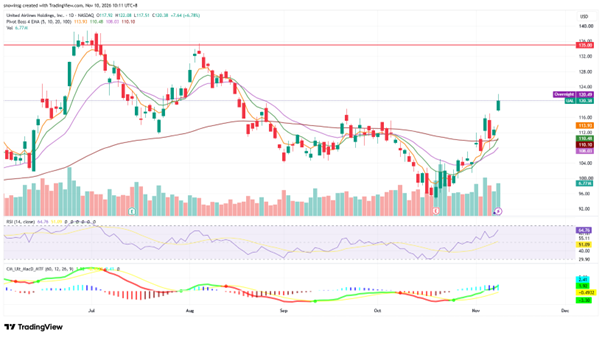
UAL US
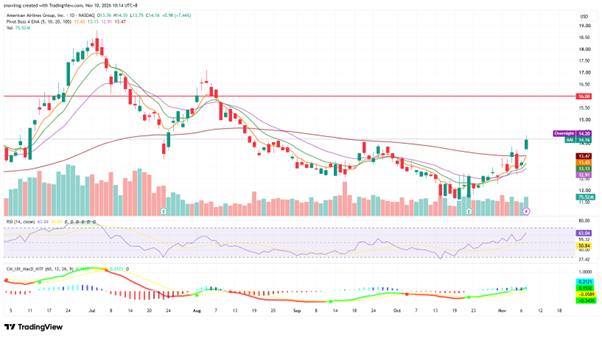
AAL US
Constellation Energy Corporation (CEG)
● 3Q26 Revenue: US$9.550bn versus US$6.570bn, up 45.4% YoY and approximately US$201m above US$9.35bn consensus. The quarter included Calpine, acquired in January.
● 3Q26 EPS: Adjusted operating EPS of US$5.06 versus US$3.04, up 66.4% YoY and US$1.17 above US$3.89 consensus. GAAP diluted EPS rose to US$5.19 from US$2.97.
● 4Q26 Guidance: No standalone quarterly revenue or EPS guidance provided.
● FY26 Guidance: Adjusted operating EPS raised and narrowed to US$12.50–12.80 from US$11.50–12.50. The midpoint increased to US$12.65 from US$12.00.
● Dividend/Share Buyback: Quarterly dividend of US$0.4265/share, payable 4 December to holders of record on 16 November. About US$1.0bn of shares repurchased in Q3 and US$3.0bn in the first nine months, with about US$2.0bn remaining authorised.
● Comment: This was a strong quarter on both current earnings and the outlook for contracted power sales. Calpine was the largest contributor to the YoY earnings increase, and the combined commercial portfolio benefited from higher PJM capacity prices and favourable market conditions. Summer is typically a strong period for Calpine, so Q3 is a demanding benchmark for the December quarter. The more durable development is the ability to sign long-term agreements with customers willing to support new generating capacity. Amazon’s 690 MW agreement supports investment at Calvert Cliffs, while Google’s agreement supports about 890 MW of additional nuclear capacity across existing plants. Those contracts improve visibility, but the earnings and cash benefits depend on project completion, and the Department of Energy’s loan commitment remains conditional. Shares closed at US$276.09 on 9 November, up 10.46%, and traded at US$275.00 post-market. After that move, I would focus on whether the next annual outlook confirms sustained earnings growth once the initial Calpine contribution is in the comparison base. Final financing, the Crane restart schedule and the balance between project spending and buybacks are the next tests. Further long-term contracts on favourable terms would strengthen the outlook, while delays or cost overruns could defer the cash flow investors are looking for. 4Q26 recommended trading range of US$245–310. Positive Outlook.
星座能源公司(CEG)
• 2026年第三季度营收:95.50亿美元,上年同期为65.70亿美元,同比增长45.4%,较93.5亿美元的市场共识高约2.01亿美元。本季度业绩包含1月收购的Calpine。
• 2026年第三季度每股收益:调整后每股经营收益为5.06美元,上年同期为3.04美元,同比增长66.4%,较3.89美元的市场共识高1.17美元。按美国通用会计准则(GAAP)计算的摊薄每股收益由2.97美元升至5.19美元。
• 2026年第四季度指引:公司未单独提供季度营收或每股收益指引。
• 2026年全年指引:调整后每股经营收益指引由11.50至12.50美元上调并收窄至12.50至12.80美元,中值由12.00美元升至12.65美元。
• 股息与回购:季度股息为每股0.4265美元,股权登记日为11月16日,派息日为12月4日。第三季度回购约10亿美元,前九个月累计回购约30亿美元,剩余回购授权约20亿美元。
• 短评:本季度盈利表现强劲,长期售电前景也有所改善。Calpine是盈利同比增长的最大贡献来源,合并后的电力业务还受益于PJM电力市场容量价格上涨及有利的市场环境。夏季通常是Calpine的盈利旺季,第三季度的强劲表现给第四季度设下了较高的比较基准。更具持续性的变化在于,公司能够与愿意支持新增发电容量的客户签订长期合约。亚马逊的690兆瓦协议支持卡尔弗特悬崖核电站的投资,谷歌的协议则支持现有核电站增加约890兆瓦容量。这些合约提高了收入的可见性,但盈利和现金流仍取决于项目能否按期落地,美国能源部的贷款承诺也附带条件。11月9日股价收于276.09美元,上涨10.46%,盘后报275.00美元。经历这轮上涨后,下一份年度指引能否证明在Calpine并表效应进入比较基数后仍可保持盈利增长,值得重点关注。后续还需观察融资能否落实、克兰核电站重启进度,以及项目支出与回购之间的平衡。若能以有利条款签下更多长期合约,前景将进一步改善。若项目延期或超支,市场期待的现金流可能推迟兑现。2026年第四季度建议交易区间为245至310美元。正面前景。
Take-Two Interactive Software, Inc. (TTWO)
● 2Q27 Revenue: GAAP net revenue of US$1.497bn versus US$1.774bn, down 15.6% YoY and about US$83m below US$1.58bn consensus. Net bookings fell 18% to US$1.60bn, about US$70m below LSEG consensus.
● 2Q27 EPS: GAAP diluted loss narrowed to US$0.29/share from US$0.73. Adjusted EPS of US$1.00 beat Zacks’ US$0.90 consensus by US$0.10.
● 3Q27 Guidance: GAAP revenue of US$3.27–3.42bn and diluted EPS of US$1.30–1.44. Net bookings of US$3.35–3.50bn versus US$3.51bn LSEG consensus.
● FY27 Guidance: Net bookings reaffirmed at US$8.0–8.2bn. GAAP revenue raised to US$7.98–8.18bn from US$7.90–8.10bn, and diluted EPS revised to US$0.57–0.75 from US$0.55–0.75. Operating cash flow remains above US$1.0bn.
● Dividend/Share Buyback: No dividend or programme repurchases in the quarter. About 10.0m shares remain available for repurchase.
● Comment: Take-Two enters the Grand Theft Auto VI launch with strong pre-orders and a softer quarter across the rest of the portfolio. Bookings came in below the company’s own guidance, with management citing weaker-than-expected performance from NBA 2K27. Recurrent consumer bookings fell 9% and still accounted for 81% of total bookings, so the health of in-game spending matters well beyond the release of a single title. The narrower GAAP loss shows the benefit of lower costs, but the bookings miss leaves the business more reliant on the holiday release slate. Management reiterated the 19 November launch and said pre-orders exceeded its initial expectations. The December-quarter bookings guide nevertheless fell below consensus at the midpoint, leaving limited room for slower conversion of pre-orders into sales or weaker spending elsewhere. Shares closed at US$207.40 on 9 November, down 3.48%, then traded at US$216.43 post-market, up 4.35% from the close. The rebound suggests the confirmed launch and pre-order commentary carried weight despite the guidance gap. The next indicators are first-month sales, spending after launch, the recovery in NBA 2K engagement and whether bookings translate into the guided operating cash flow. A strong launch would support the year, while sustained recurrent spending would give investors more confidence in earnings beyond it. 3Q27 recommended trading range of US$190–240. Neutral Outlook.
Take-Two互动软件公司(TTWO)
• 2027财年第二季度营收:GAAP净营收为14.97亿美元,上年同期为17.74亿美元,同比下降15.6%,较15.8亿美元的市场共识低约8300万美元。净预订额下降18%至16.0亿美元,较LSEG市场共识低约7000万美元。
• 2027财年第二季度每股收益:GAAP摊薄每股亏损由0.73美元收窄至0.29美元。调整后每股收益为1.00美元,较Zacks的0.90美元共识高0.10美元。
• 2027财年第三季度指引:GAAP营收预计为32.7至34.2亿美元,摊薄每股收益为1.30至1.44美元。净预订额预计为33.5至35.0亿美元,低于LSEG的35.1亿美元共识。
• 2027财年全年指引:重申80至82亿美元的净预订额指引。GAAP营收指引由79.0至81.0亿美元上调至79.8至81.8亿美元,摊薄每股收益指引由0.55至0.75美元调整至0.57至0.75美元。经营现金流仍预计超过10亿美元。
• 股息与回购:本季度未派息,也未依据回购计划购回股份。尚可回购约1000万股。
• 短评:《侠盗猎车手VI》上市在即,预购表现强劲,而其他游戏业务本季度整体偏弱。净预订额低于公司自身指引,管理层指出《NBA 2K27》的表现逊于预期。经常性玩家消费对应的净预订额同比下降9%,但仍占总净预订额的81%,可见游戏内消费的韧性关系到新作上市之后的盈利。GAAP亏损收窄体现了成本下降的作用,不过预订额不及预期,使公司更依赖年末推出的新作。管理层重申《侠盗猎车手VI》将于11月19日上市,并表示预购超出最初预期。尽管如此,12月季度净预订额指引中值仍低于市场共识。如果预购转化为实际销量的速度放慢,或其他游戏消费进一步走弱,业绩可缓冲的空间有限。11月9日股价收于207.40美元,下跌3.48%,盘后回升至216.43美元,较收盘上涨4.35%。这表明确认上市日期及预购表现可能缓解了市场对指引的担忧。接下来应关注新作首月销量、上市后的玩家消费、《NBA 2K》参与度能否恢复,以及预订额能否转化为指引所预期的经营现金流。首发畅销有助于完成全年目标,持续的游戏内消费则更能增强投资者对后续盈利的信心。2027财年第三季度建议交易区间为190至240美元。中性前景。
AST SpaceMobile, Inc. (ASTS)
● 3Q26 Revenue: US$42.32m versus US$14.74m, up 187.1% YoY and US$3.68m below US$46.0m consensus. Gateway deliveries and U.S. government milestones drove sales.
● 3Q26 EPS: GAAP diluted loss of US$0.44/share versus US$0.45 a year earlier, US$0.03 wider than the consensus loss of US$0.41. The loss attributable to common shareholders widened to US$132.4m.
● 4Q26 Guidance: No standalone revenue or EPS range provided. Management expects revenue to accelerate and targets intermittent service in the U.S. and other key markets before year-end.
● FY26 Guidance: Revenue reaffirmed at US$150–200m, with management citing potential upside from recently signed contracts. No EPS guidance provided.
● Dividend/Share Buyback: No common dividend or buyback announced. Cash, cash equivalents and restricted cash totalled about US$3.2bn. Nine-month operating cash outflow was US$314.5m, and purchases of property and equipment were US$1.15bn.
● Comment: AST SpaceMobile is beginning to turn its commercial and government relationships into revenue, but satellite deployment remains the main determinant of the investment case. Gateway deliveries and government milestones can move sales materially between quarters. The full-year guide requires a substantial step-up from Q3, which puts the timing of those milestones in focus. Intermittent service before year-end would demonstrate progress with carrier partners. Continuous coverage across key markets requires more satellites in operation, and the target for roughly 45 BlueBirds in orbit has shifted from early to mid-2027. The US$3.2bn cash balance, including restricted cash, gives AST room to invest, while operating cash burn and satellite spending show how capital-intensive the rollout remains. The Blacklift rocket could give AST greater control over launch timing in the longer term. It also adds a development programme while the company is still scaling its satellite factories and relying on third-party launch providers for the near-term schedule. Shares closed at US$36.89 on 9 November, up 14.10% before the report, then traded at US$36.62 post-market, down 0.74% from the close. Confirmed launch dates, successful in-orbit deployments and paying carrier traffic would strengthen the outlook. Further schedule slippage would extend the period of heavy spending before service revenue can scale. 4Q26 recommended trading range of US$28–48. Neutral Outlook.
AST太空移动公司(ASTS)
• 2026年第三季度营收:4232万美元,上年同期为1474万美元,同比增长187.1%,较4600万美元的市场共识低368万美元。地面网关设备交付和美国政府项目达成里程碑带动了营收。
• 2026年第三季度每股收益:GAAP摊薄每股亏损为0.44美元,上年同期亏损0.45美元,较市场预期的0.41美元亏损多0.03美元。归属于普通股股东的净亏损扩大至1.324亿美元。
• 2026年第四季度指引:公司未单独提供营收或每股收益区间。管理层预计营收增长将加快,并计划在年底前于美国及其他重点市场开通间歇性服务。
• 2026年全年指引:重申1.50至2.00亿美元的营收指引。管理层表示近期签订的合同可能带来额外收入。未提供每股收益指引。
• 股息与回购:未宣布普通股股息或股份回购。现金、现金等价物及受限现金合计约32亿美元。前九个月经营现金净流出3.145亿美元,购置物业及设备支出11.5亿美元。
• 短评:AST太空移动已开始将商业与政府合作转化为收入,但卫星部署进度仍是决定投资前景的主要因素。地面网关交付和政府项目的里程碑可导致季度营收明显波动。要达到全年指引,第四季度营收需要较第三季度显著增长,因此相关里程碑能否及时完成尤为重要。若能在年底前开通间歇性服务,将体现公司与运营商合作的进展。重点市场实现连续覆盖仍需更多卫星投入运行,而约45颗BlueBird卫星在轨的目标已由2027年初推迟至年中。约32亿美元的现金余额(含受限现金)为后续投资提供了空间,但经营现金消耗及卫星支出也反映出部署仍高度依赖资本投入。Blacklift火箭长远来看或能提高公司对发射时间的掌控力,但在卫星工厂仍处于扩产阶段、近期发射仍依赖第三方的情况下,自研火箭也增加了执行难度。11月9日股价在财报公布前上涨14.10%,收于36.89美元,盘后报36.62美元,较收盘下跌0.74%。发射日期敲定、卫星顺利在轨部署以及运营商付费流量的出现,都将改善前景。若进度再度延后,公司在服务收入形成规模前将面临更长的高支出期。2026年第四季度建议交易区间为28至48美元。中性前景。
Quantum Corporation (QMCO)
● 2Q27 Revenue: US$89.62m versus US$62.7m, up 42.9% YoY and US$7.32m above US$82.30m consensus. Gross margin rose to 41.0% from 37.6%, and order backlog reached nearly US$100m.
● 2Q27 EPS: Adjusted EPS of US$0.25 versus a US$0.54 loss, beating US$0.13 consensus by US$0.12. GAAP loss narrowed to US$1.14/share from US$3.49 and included a US$51.6m non-cash warrant revaluation charge. Adjusted EBITDA rose to US$11.1m from US$0.5m.
● 3Q27 Guidance: Revenue of US$89–93m, with the US$91m midpoint above US$85.53m consensus. Adjusted basic EPS of US$0.10–0.30 and adjusted EBITDA of US$8.1–10.1m.
● FY27 Guidance: No full-year revenue or EPS guidance provided.
● Dividend/Share Buyback: No dividend or buyback announced. Quarter-end cash, cash equivalents and restricted cash totalled US$67.5m, with no outstanding debt. First-half operating cash flow improved to US$14.3m from a US$32.5m outflow.
● Comment: Quantum’s turnaround has more substance this quarter because the sales beat came with better gross margins and positive first-half operating cash flow. The large Scalar i7 Raptor deployment and record ActiveScale order show customers committing to tape and cold storage as their data volumes grow. A nearly US$100m backlog improves shipment visibility, though individual orders are large relative to quarterly sales, and component supply can still affect delivery dates. The main point of tension is the next-quarter outlook. The revenue midpoint is above both Q2 actuals and consensus, yet adjusted EBITDA is expected to decline even at the top of the range. That makes gross margin and operating expenses more important to watch than the revenue headline. The debt-free balance sheet also removes a source of interest expense. Warrant revaluations can still make GAAP earnings volatile, so cash flow and gross profit help show how much of the operational improvement is carrying through. Shares closed at US$16.99 on 9 November, up 17.42%, then traded at US$19.74 post-market, up another 16.19% from the close. After that move, timely backlog conversion, continued cash generation and repeat orders from a broader customer base would do more to support the stock than another large order on its own. 3Q27 recommended trading range of US$14–24. Neutral Outlook.
昆腾公司(QMCO)
• 2027财年第二季度营收:8962万美元,上年同期为6270万美元,同比增长42.9%,较8230万美元的市场共识高732万美元。毛利率由37.6%升至41.0%,未交付订单接近1亿美元。
• 2027财年第二季度每股收益:调整后每股收益为0.25美元,上年同期亏损0.54美元,较0.13美元的市场共识高0.12美元。GAAP每股亏损由3.49美元收窄至1.14美元,其中包括5160万美元的非现金认股权证重估费用。调整后EBITDA由50万美元升至1110万美元。
• 2027财年第三季度指引:营收预计为8900万至9300万美元,中值9100万美元高于8553万美元的市场共识。调整后基本每股收益预计为0.10至0.30美元,调整后EBITDA为810万至1010万美元。
• 2027财年全年指引:公司未提供全年营收或每股收益指引。
• 股息与回购:未宣布股息或回购。季末现金、现金等价物及受限现金合计6750万美元,无未偿债务。上半财年经营现金流由净流出3250万美元转为净流入1430万美元。
• 短评:昆腾本季度的经营改善更有说服力,营收超预期的同时,毛利率上升,上半财年经营现金流也转为正值。大型Scalar i7 Raptor部署及创纪录的ActiveScale订单表明,随着数据量增长,客户正加大对磁带和冷存储的投入。接近1亿美元的未交付订单提高了未来出货的可见性。不过,单笔大额订单相对于季度营收占比较高,零部件供应也可能影响交货时间。下季度指引的分化值得关注。营收中值高于第二季度实际值和市场共识,但即使达到调整后EBITDA指引上限,该指标仍将环比下降。因此,毛利率和经营费用比营收数字更能反映增长的质量。无债务降低了利息负担,认股权证重估仍可能令GAAP盈利波动,现金流和毛利更能说明经营改善能否转化为实际回报。11月9日股价上涨17.42%,收于16.99美元,盘后报19.74美元,较收盘再涨16.19%。经历这轮上涨后,未交付订单能否按期转化为收入、现金流能否持续改善,以及更广泛的客户群能否带来重复订单,比再获得一笔大单更能支撑股价。2027财年第三季度建议交易区间为14至24美元。中性前景。
Hims & Hers Health, Inc. (HIMS)
● 3Q26 Revenue: US$890.37m versus US$598.98m, up 48.6% YoY and US$2.51m below US$892.88m consensus. U.S. revenue grew 21%, international revenue rose 321%, and subscribers increased 13% to 2.79m.
● 3Q26 EPS: GAAP diluted loss of US$0.14/share versus EPS of US$0.06, US$0.20 below US$0.06 consensus. Adjusted EBITDA rose to US$82.4m from US$78.4m, while gross margin fell to 57% from 74%.
● 4Q26 Guidance: Revenue of US$875–895m versus US$955.1m consensus. Adjusted EBITDA of US$70–90m, equivalent to an 8–10% margin. No EPS guidance provided.
● FY26 Guidance: Revenue narrowed to US$3.13–3.15bn from US$3.10–3.30bn, lowering the midpoint. Adjusted EBITDA cut to US$257–277m from US$275–325m.
● Dividend/Share Buyback: No dividend or repurchases in the first nine months. US$225m remains authorised. Quarterly free cash flow fell to US$26.0m from US$79.4m.
● Comment: Hims & Hers grew revenue by nearly half, but gross margin fell 17 percentage points and free cash flow fell by roughly two-thirds. The U.S. business showed genuine demand, with weight loss and dermatology contributing to 21% growth. International sales more than quadrupled, helped by Eucalyptus and other acquisitions. The weakness is in the economics of that growth. Some weight-loss offerings carry higher product, packaging and shipping costs, and adjusted EBITDA increased only modestly despite the much larger revenue base. The Q4 revenue midpoint is slightly below Q3 actuals and materially below consensus. Management also expects weight-loss pricing changes and heavier marketing in markets including the UK and Germany, which puts more near-term pressure on profitability. The test is whether lower prices and increased marketing bring in customers who stay long enough to recover those costs. Shares closed at US$22.94 on 9 November, down 11.77%, then traded at US$22.16 post-market, down another 3.40% from the close. I would look for stabilising gross margins, subscriber retention across the expanded weight-loss offering and evidence that international growth is beginning to contribute cash. Revenue growth alone offers limited support while earnings expectations and cash conversion are moving lower. 4Q26 recommended trading range of US$18–27. Negative Outlook.
Hims & Hers健康公司(HIMS)
• 2026年第三季度营收:8.9037亿美元,上年同期为5.9898亿美元,同比增长48.6%,较8.9288亿美元的市场共识低251万美元。美国营收增长21%,国际营收增长321%,订阅用户增长13%至279万。
• 2026年第三季度每股收益:GAAP摊薄每股亏损为0.14美元,上年同期每股盈利0.06美元,较市场预期的每股盈利0.06美元低0.20美元。调整后EBITDA由7840万美元升至8240万美元,毛利率由74%降至57%。
• 2026年第四季度指引:营收预计为8.75至8.95亿美元,低于9.551亿美元的市场共识。调整后EBITDA预计为7000万至9000万美元,对应利润率为8%至10%。未提供每股收益指引。
• 2026年全年指引:营收指引由31.0至33.0亿美元收窄至31.3至31.5亿美元,中值下调。调整后EBITDA指引由2.75至3.25亿美元下调至2.57至2.77亿美元。
• 股息与回购:前九个月未派息或回购,剩余回购授权为2.25亿美元。季度自由现金流由7940万美元降至2600万美元。
• 短评:Hims & Hers营收增长近五成,但毛利率下降17个百分点,自由现金流减少约三分之二。美国业务需求有所增长,减重和皮肤科业务带动美国营收增长21%。受收购Eucalyptus等因素推动,国际营收增至上年同期的四倍以上。问题在于这些新增收入的盈利能力。部分减重产品的采购、包装和配送成本较高,尽管营收规模显著扩大,调整后EBITDA仅小幅上升。第四季度营收指引中值略低于第三季度实际营收,并明显低于市场共识。管理层还计划调整减重产品定价,并加大英国和德国等市场的营销投入,短期盈利可能进一步承压。需要观察降价和增加营销能否吸引留存时间足够长的客户,从而收回获客投入。11月9日股价下跌11.77%,收于22.94美元,盘后报22.16美元,较收盘再跌3.40%。后续重点是毛利率能否企稳、扩充减重产品线后的订阅留存率,以及国际增长能否开始贡献现金。在盈利预期和现金转化走弱期间,单靠营收增长对股价的支撑有限。2026年第四季度建议交易区间为18至27美元。负面前景。
Occidental Petroleum Corporation (OXY)
● 3Q26 Revenue: Continuing-operations revenue and other income of US$6.772bn versus US$5.613bn on the company’s recast basis, up 20.6% YoY and about US$40m above Zacks’ US$6.73bn consensus. Net sales were US$6.567bn versus US$5.519bn.
● 3Q26 EPS: Adjusted diluted EPS from continuing operations of US$1.91 versus US$0.51, US$0.48 above Zacks’ US$1.43 consensus. GAAP diluted EPS rose to US$1.61 from US$0.65. Derivative losses accounted for most of the adjustment.
● 4Q26 Guidance: No standalone revenue or EPS guidance in the 9 November release. A new quarterly production or capital spending range could not be verified.
● FY26 Guidance: The latest operating guidance verified was from August, at 1.423–1.453m barrels of oil equivalent per day and US$5.5–5.9bn in net capital expenditure. No full-year revenue or EPS guidance in the Q3 release.
● Dividend/Share Buyback: Quarterly dividend of US$0.28/share, payable 15 January 2027 to holders of record on 10 December. No purchases under the public buyback programme in the first nine months. US$1.223bn remains authorised. Principal debt fell US$1.8bn in Q3 to about US$10.0bn.
● Comment: The earnings beat was supported by operations as well as commodity prices. Permian and Rockies performance helped lift production above the guidance midpoint despite temporary offshore downtime, and adjusted midstream and marketing income exceeded the high end of guidance. There was still some sequential pressure. Worldwide realised crude prices fell 11% from Q2, and narrower gas spreads reduced midstream margins. Against that backdrop, US$4.1bn in continuing-operations operating cash flow and US$2.8bn in free cash flow before working capital were strong results. The reduction in principal debt to about US$10bn is the most durable improvement. OxyChem sale proceeds funded much of this year’s repayment, so operating cash after capital expenditure and dividends will be the better measure of how quickly Occidental can reduce debt further and increase shareholder returns. Management is targeting more than US$4bn in additional annual sustainable cash flow by 2030, with execution still to be demonstrated. Shares traded at US$56.00 post-market on 9 November, up 0.43% from the close. The modest reaction leaves the near-term outlook sensitive to realised oil prices, Permian well productivity, the capital budget and management’s plans for the next dollar of free cash flow. Sustained production at disciplined spending levels would support the case for higher returns to shareholders. 4Q26 recommended trading range of US$49–63. Positive Outlook.
西方石油公司(OXY)
• 2026年第三季度营收:按公司重列后的口径,持续经营业务营收及其他收入为67.72亿美元,上年同期为56.13亿美元,同比增长20.6%,较Zacks的67.3亿美元共识高约4000万美元。净销售额为65.67亿美元,上年同期为55.19亿美元。
• 2026年第三季度每股收益:持续经营业务调整后摊薄每股收益为1.91美元,上年同期为0.51美元,较Zacks的1.43美元共识高0.48美元。GAAP摊薄每股收益由0.65美元升至1.61美元。衍生品亏损是主要调整项。
• 2026年第四季度指引:11月9日的财报未单独提供季度营收或每股收益指引。未能核实新的季度产量或资本支出区间。
• 2026年全年指引:可核实的最新经营指引发布于8月,预计日均产量为142.3万至145.3万桶油当量,净资本支出为55至59亿美元。第三季度财报未提供全年营收或每股收益指引。
• 股息与回购:季度股息为每股0.28美元,股权登记日为12月10日,派息日为2027年1月15日。前九个月未依据公开回购计划购回股份,剩余授权为12.23亿美元。第三季度债务本金减少18亿美元,降至约100亿美元。
• 短评:经营表现和大宗商品价格共同推动盈利超预期。尽管海上设施一度停产,二叠纪盆地和落基山地区的表现仍带动产量超过指引中值,中游及营销业务的调整后利润也高于指引上限。部分指标环比承压。全球原油实际售价较第二季度下降11%,天然气价差收窄也压低了中游利润率。在这一背景下,持续经营业务录得41亿美元经营现金流,营运资本变动前自由现金流达28亿美元,表现依然强劲。债务本金降至约100亿美元是更具持续性的改善。出售OxyChem所得为今年大部分偿债提供了资金,后续应重点观察扣除资本支出和股息后的经营现金流,这更能反映公司进一步降债并提高股东回报的速度。管理层目标是在2030年前将可持续年度现金流提高逾40亿美元,仍需后续业绩验证。11月9日股价盘后报56.00美元,较收盘上涨0.43%。盘后反应温和,短期表现仍取决于原油实际售价、二叠纪盆地单井产出、资本预算及管理层如何分配新增自由现金流。若公司能在控制支出的同时维持产量,提高股东回报的基础将更扎实。2026年第四季度建议交易区间为49至63美元。正面前景。