DFI SP
Asian retail recovery play
KEY INSIGHTS #1
Improving Singapore retail spending supports health & beauty demand.
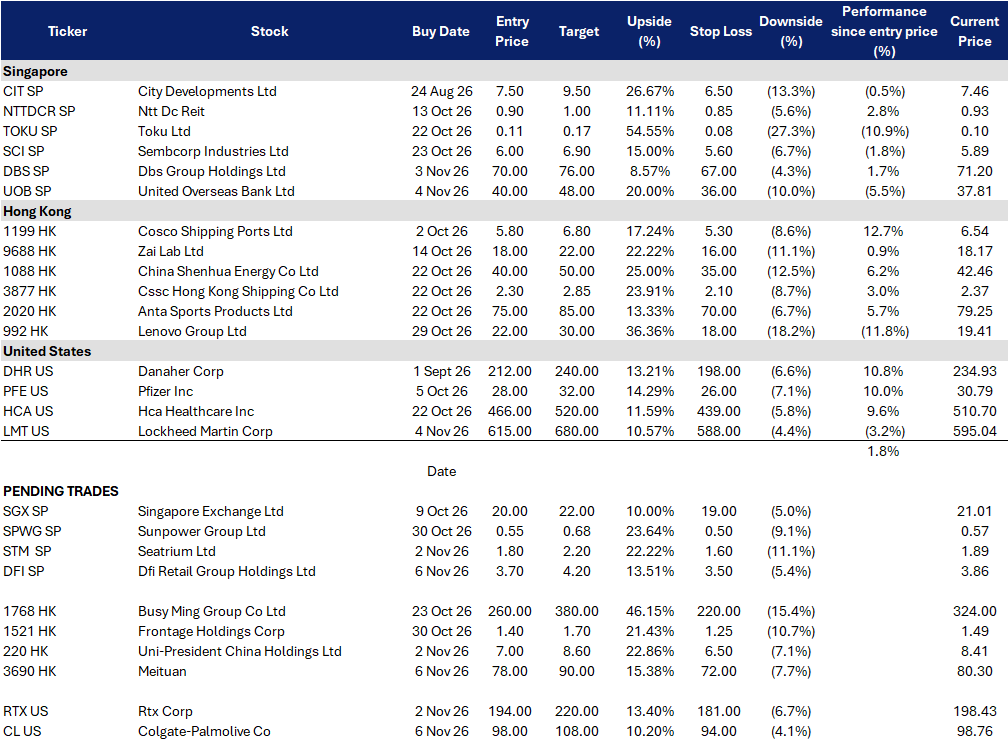
Singapore retail sales accelerated to +1.7% YoY in September 2026, from +0.8% in August, while sales excluding motor vehicles rose a stronger 2.5%. Importantly for DFI, cosmetics, toiletries and medical goods sales increased 6.0% YoY, providing a supportive backdrop for Guardian, while total online penetration rose to 17.7% of retail sales. Interestingly, Singapore mini-mart and convenience-store sales declined 5.6% YoY, yet DFI’s Singapore Convenience business delivered 11% LFL growth in 3Q26, suggesting DFI is gaining share through higher traffic and differentiated categories rather than relying purely on market growth.
KEY INSIGHTS #2
Stronger profit growth, digital scaling and Starbucks reshape the earnings profile.
DFI’s execution strengthened further in 3Q26, with underlying subsidiary sales from continuing operations rising 4% YoY and underlying profit increasing 17%, driven by stronger Health & Beauty and Home Furnishings profitability and lower administrative costs. Health & Beauty sales rose 7%, digital profitability nearly tripled YoY, and DFI raised FY26 underlying profit guidance to US$295–305mn; the acquisition of Starbucks operations across seven Asian markets adds another potential growth pillar, while the FY27 dividend payout ratio will rise to 80% from 70% in FY26.
STM SP
Order replenishment, margin recovery, and execution credibility rebuild
KEY INSIGHTS #1
October order wins materially reduce concerns around backlog replacement
Seatrium has entered a strong order-award cycle after backlog declined to S$13.3B at end-June from S$17.8B at end-2025. On 26 October, RigCo awarded more than S$500M of work to complete four offshore rigs, while on 30 October Seatrium secured another FPSO integration contract worth over S$200M from SBM Offshore for a South American project, with execution beginning in 4Q26 through 2029. This follows October awards for five Karpowership Whale Class Powership conversions and an Excelerate Energy FSRU conversion. The breadth of FPSO, drilling, LNG and floating-power wins suggests Seatrium is replenishing backlog beyond its large Petrobras contracts and reduces the risk that revenue falls sharply once the current FPSO programme matures.
KEY INSIGHTS #2
19 November business update and S$200M buyback create near-term rerating catalysts
Seatrium will release its 3Q26 business update before market open on 19 November, with investors likely focused on updated order book, margin progression and the conversion of its more than S$32B opportunity pipeline. Management has also doubled its share-repurchase programme to S$200M and continues buying stock around current levels, including purchases at approximately S$1.83 in October. With the shares now around S$1.84 versus above S$2.20 in September, expectations have reset substantially despite accelerating contract wins. A 3Q update demonstrating continued margin improvement and order-book stabilisation could support a recovery toward S$2.20.
3690 HK
Local-commerce leader combining resilient service consumption with AI-driven efficiency
KEY INSIGHTS #1
Service consumption remains more resilient than headline retail growth.
China’s overall consumption environment remains subdued, but services continue to outperform goods, providing a more favourable backdrop for Meituan. In 9M26, service retail sales rose 5.0% YoY and online service sales increased 5.3%, compared with much weaker headline retail growth, supporting continued demand across food delivery, in-store services, travel and instant retail as consumption increasingly shifts toward experiences and digitally enabled services.
KEY INSIGHTS #2
AI investment can deepen merchant monetisation and improve platform efficiency.
Meituan is increasingly using AI as an operating tool rather than simply pursuing standalone model development. Its newly launched LongCat-2.5, a 1.6tn-parameter multimodal model trained entirely on domestic chips, is designed for long-horizon agentic tasks and can help merchants analyse channel profitability, identify growth bottlenecks and recommend resource allocation, potentially improving merchant ROI and strengthening Meituan’s value proposition across its local-commerce ecosystem. This builds on Meituan’s already significant AI investment and provides another lever for improving recommendations, merchant operations and platform efficiency as competition becomes more rational.
220 HK
Premiumisation, margin resilience, and defensive yield
KEY INSIGHTS #1
Value conscious consumption is favouring affordable packaged food while noodle premiumisation remains resilient
China’s consumer environment remains subdued, but spending is increasingly shifting toward affordable quality and products offering clear value for money, which is comparatively supportive for Uni President’s mass market portfolio. In 1H26, food revenue increased 4.7% YoY to RMB5.63B, driven by continued strength in higher value noodle brands such as King of Tomato and Imperial Big Meal, while the latter delivered high double digit revenue growth. Beverage demand was softer, declining 0.3%, but the diversification between food and beverages provides greater defensiveness than a pure discretionary consumer name.
KEY INSIGHTS #2
Product mix is allowing profit to grow substantially faster than revenue
1H26 group revenue increased only 1.4% YoY to RMB17.32B, but gross margin expanded 0.7ppt to 35.0%, operating profit increased 9.5% to RMB1.80B and attributable profit rose 9.0% to RMB1.40B. The divergence reflects continued premiumisation in noodles, tighter product portfolio management and disciplined cost control. This is important because the investment case does not require a major Chinese consumption recovery. Even low single digit revenue growth can still translate into mid to high single digit earnings growth if mix improvement continues.
CL US
Defensive consumer-staples compounder anchored by global oral-care leadership
KEY INSIGHTS #1
Essential household categories offer resilience as consumer purchasing power weakens.
U.S. consumers remain under pressure, with the University of Michigan Consumer Sentiment Index at 48.0 in October, down 10% YoY, while one-year inflation expectations rose to 4.7% and purchasing power remained a key concern. Against this backdrop, everyday necessities such as toothpaste, personal care and pet nutrition should remain comparatively resilient because purchase frequency is less discretionary, supporting Colgate’s defensive earnings profile even as households become more selective elsewhere.
KEY INSIGHTS #2
Oral-care leadership, margin recovery and consistent dividends support defensive returns.
Colgate continues to combine category leadership with improving operating leverage: 3Q26 net sales rose 4.6% YoY, organic sales increased 3.6%, Base Business EPS grew 7%, and gross margin expanded 90bps to 60.3%. Its global toothpaste and manual-toothbrush shares remain dominant at 41.4% and 33.1%, respectively, while management continues to invest behind premium, science-based innovation and advertising; alongside this, Colgate has increased its dividend for 63 consecutive years, reinforcing the consistency of shareholder returns and its defensive investment profile.
RTX US
Diversified aerospace and defense platform benefiting from missile demand and commercial aftermarket growth
KEY INSIGHTS #1
Rearmament and aircraft scarcity support both sides of RTX’s portfolio.
RTX benefits from two structural spending cycles at once: rising defense budgets are supporting demand for Patriot, AMRAAM, Tomahawk and other missile systems, while persistent shortages of new aircraft and engines are forcing airlines to operate existing fleets at high utilisation rates and sustain maintenance spending. IATA estimates the industry is effectively short roughly 3,170 aircraft, while NATO’s higher spending commitment supports continued defense procurement, creating a favourable backdrop for both Raytheon and the commercial aftermarket businesses at Pratt & Whitney and Collins Aerospace.
KEY INSIGHTS #2
Record backlog and improving segment profitability support stronger cash flow.
RTX’s diversified model is translating this demand into stronger operating performance, with 3Q26 sales rising 11% YoY to US$25.0bn and backlog reaching a record US$340bn, split between US$176bn commercial and US$164bn defense. Raytheon sales grew 14% on stronger Patriot, Standard Missile and Tomahawk volumes, Pratt & Whitney commercial aftermarket revenue rose 21%, and Collins commercial aftermarket sales increased 9%; improving productivity helped RTX raise FY26 adjusted EPS and free-cash-flow guidance to US$7.65–7.75 and US$9.0–9.2bn, respectively.
STOCKS
STOCKS
STOCKS