PCPG SP
GPU pricing power, AI-server ramp, and valuation reset
KEY INSIGHTS #1
AI-driven component shortages continue to support GPU pricing despite weaker consumer volumes
Graphics-card supply remains exceptionally tight as AI infrastructure absorbs memory and semiconductor capacity. PC Partner previously guided that VGA availability would deteriorate further in 2H26, particularly at the entry level, while rising GDDR6/GDDR7 costs should continue pushing ASPs higher. That thesis remains intact in October: RTX 50-series retail prices remain materially above launch levels and industry checks continue to show severe memory constraints. In 1H26, PC Partner’s own-brand VGA ASP already increased 10.7% YoY, while ODM/OEM ASP surged 181%, allowing group revenue to grow despite sharply lower unit volumes.
KEY INSIGHTS #2
AI servers have moved from optionality into a meaningful 2H26 revenue contributor
Management now targets GPU servers at more than 15% of 2H26 revenue, a substantial upgrade from expectations earlier in the year that server contribution would remain minimal. PC Partner’s product portfolio includes the 6U ZRS-326SV2 eight-GPU server and 4U ZRS-MGX-R1 built around NVIDIA MGX, RTX PRO 6000 Blackwell Server Edition GPUs and ConnectX-8 networking. The opportunity is not yet equivalent to rack-scale HGX or NVL systems, but even moderate adoption among system integrators and enterprise customers materially expands PC Partner’s addressable market beyond consumer graphics cards and provides a growth bridge into FY27.
SCI SP
Alinta earnings uplift, AI-power demand, and India renewables value unlock
KEY INSIGHTS #1
AI and data-centre power demand are strengthening Sembcorp’s integrated energy proposition.
Electricity demand from data centres and AI infrastructure is increasingly becoming a structural growth driver across Singapore and the wider region, favouring generators capable of providing both reliable baseload power and low-carbon electricity. Sembcorp’s Singapore portfolio remains highly contracted, with around 80% of contracted load secured for five years or longer, reducing exposure to near-term power-price volatility. The group has also received conditional approval for a 300MW renewable-power import project from Malaysia, supported by a planned 2.2GWp floating-solar development and up to 4.3GWh of battery storage in Johor. This strengthens Sembcorp’s positioning as Singapore seeks more electricity supply for energy-intensive industries.
KEY INSIGHTS #2
A potential India renewables IPO could crystallise hidden portfolio value.
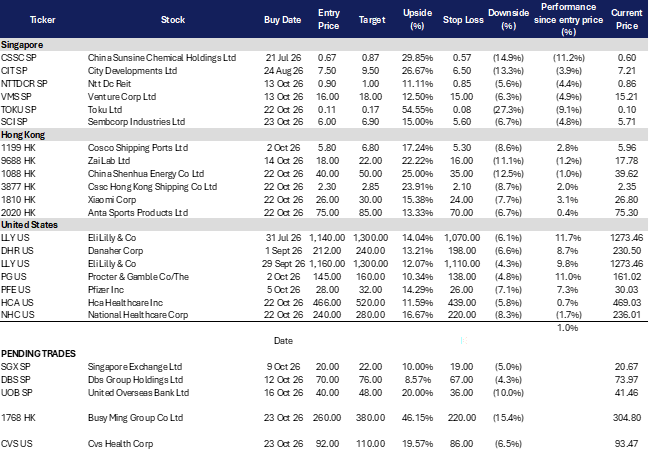
In August, wholly owned Sembcorp Green Infra filed a draft red herring prospectus with SEBI, NSE and BSE for a potential Indian IPO. The transaction is not guaranteed to proceed, but a listing could establish a transparent market valuation for Sembcorp’s sizeable Indian renewables platform while providing another avenue for capital recycling and growth funding. At around S$6.04, U96 trades near 10.4x forward earnings and well below its S$7.20 52-week high. A successful India value-unlock alongside stronger 2H26 earnings could support a rerating toward S$6.90.
992 HK
AI-server scale, margin transformation, and post-selloff earnings catalyst
KEY INSIGHTS #1
AI infrastructure is becoming a genuine second earnings engine beyond PCs
Lenovo’s Infrastructure Solutions Group is benefiting directly from accelerating AI training and inference investment. In 1QFY27, ISG revenue surged 98% YoY to a record US$8.5B, while operating profit reached US$777M and operating margin expanded to a record 9.1%. Its AI-server pipeline also increased 157% QoQ to US$54B. Product momentum remains strong, with Lenovo now supporting NVIDIA’s full Vera Rubin rack-scale platform and expanding its Hybrid AI Factory offering for enterprise and sovereign-AI workloads. This materially reduces the investment case’s historical dependence on the PC replacement cycle.
KEY INSIGHTS #2
The 25% October collapse has reset expectations ahead of 19 November earnings
Lenovo has fallen from HK$28.06 on 16 October to HK$22.40 on 23 October, including a 10.9% decline on 22 October. The selloff reflected broader Hong Kong tech weakness, concerns around a US$2B loan refinancing, weaker PC shipment data and Citi cutting its target to HK$40 because of potential dilution from outstanding convertible bonds and warrants, while retaining a Buy rating. The important point is that none of these developments currently represents an operational earnings downgrade. With 2QFY27 results due on 19 November, confirmation that ISG margins remain elevated and AI-server demand continues converting would be enough to drive a partial reversal of the recent de-rating toward HK$28.
1768 HK
Store-network expansion, margin scaling, and valuation reset
KEY INSIGHTS #1
Value-for-money consumption is supporting rapid expansion despite weak discretionary spending.
China’s consumer environment remains soft, but this is actually supportive for Busy Ming’s value-retail proposition as consumers trade down toward lower-priced snacks and beverages rather than eliminate consumption altogether. 1H26 revenue surged 60.0% YoY to RMB45.0B, while network GMV reached RMB63.9B. Store count increased from 21,948 at end-2025 to 26,405 by June, with 4,590 franchise stores opened against only 121 closures during the half. Around 60% of stores are already located in counties and townships, yet Busy Ming covers only around 79% of China’s counties, leaving further penetration potential in lower-tier markets.
KEY INSIGHTS #2
The sharp October correction has materially reset the valuation despite no corresponding earnings reset
Busy Ming closed at HK$305.40 on 21 October after falling almost 10% on 20 October alone and is now roughly 34% below its HK$465.60 post-listing high. The correction has occurred despite the strong 1H26 earnings trajectory, while published analyst targets remain substantially higher, with even the lower end of recent consensus around HK$430 and the median above HK$500. The key risk is that aggressive store expansion eventually cannibalises franchisee economics, so same-store productivity and store closures need monitoring. However, around HK$300, the valuation reset provides a much cleaner entry for a recovery toward HK$380 if 2H26 demonstrates that rapid network expansion can coexist with stable store economics and continued margin gains.
LEN US
Rate sensitivity, asset-light execution, and Berkshire accumulation
KEY INSIGHTS #1
Falling Treasury yields provide an immediate catalyst for a deeply rate-sensitive housing sector
US housing affordability remains difficult, with 30-year mortgage rates still above 7%, forcing builders to use price reductions, mortgage-rate buydowns and closing-cost incentives to maintain volumes. However, the 10-year Treasury yield fell 17bps to 4.95% on 22 October, triggering a 4.7% rally in the US home-construction ETF and an 8.7% jump in Lennar to US$84.45. Lennar is particularly leveraged to any sustained decline in financing costs because affordability, rather than underlying desire to purchase homes, remains the primary constraint on demand. Even modest mortgage-rate relief could reduce the approximately 12% incentives currently embedded in Lennar’s average selling price and eventually support margin recovery.
KEY INSIGHTS #2
Berkshire has built a 12.5% stake near current levels, creating unusually strong valuation support
Berkshire Hathaway accumulated Lennar aggressively through September and early October, reaching beneficial ownership of 26.0M Class A shares, or 12.5% of the class, as of 30 September. Purchases continued around US$79–82 even as housing conditions weakened, providing a meaningful external validation of long-term value around the current trading range.
CVS US
Aetna margin recovery, guidance upgrades, and 2027 earnings visibility
KEY INSIGHTS #1
Medicare Advantage economics are improving as pricing catches up with elevated medical costs.
The key industry concern has been elevated utilisation across Medicare Advantage, but CVS is showing increasingly convincing evidence that its Aetna remediation is working. Health Care Benefits adjusted operating income reached US$2.43B in 2Q26 versus US$1.31B a year earlier, while the medical benefit ratio improved 250bps to 87.4%. Management attributed the improvement partly to disciplined pricing and stronger Medicare medical-cost management. Quality remains supportive as well, with 69% of Aetna’s Medicare Advantage members enrolled in plans rated four stars or higher in the 2027 CMS ratings, helping protect future bonus economics and member retention.
KEY INSIGHTS #2
Management has already established a US$8.44 floor for 2027 EPS ahead of 3Q26 earnings.
CFO Brian Newman described US$8.44 of 2027 adjusted EPS as a reasonable floor, equivalent to roughly 13% growth from CVS’s underlying 2026 earnings baseline, while reaffirming confidence in its longer-term mid-teens EPS CAGR framework. The next catalyst is 3Q26 earnings on 4 November, where investors will focus on whether Aetna’s medical-cost improvement persists and whether management formalises a stronger 2027 outlook. At around US$94, CVS trades at roughly 11–12x forward earnings versus a current analyst target near US$115, leaving room for further rerating if the insurance turnaround proves sustainable.
STOCKS
–
STOCKS
STOCKS
–