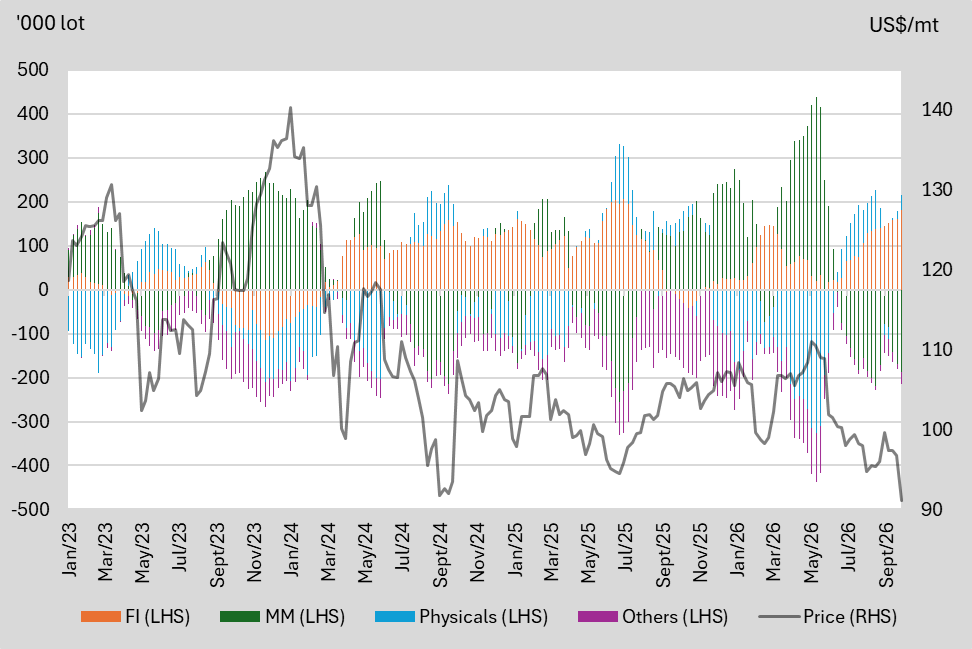
We highlight the key price levels that each participant switches their positions between net long and net short based on 2025 data.
| PARTICIPANT | NET LONG | NET SHORT |
|---|---|---|
| Financial Institution (FI) | Below US$108/mt | N/A |
| Managed Money (MM) | Above US$101/mt | Below US$101/mt |
| Physicals | Below US$100/mt | Above US$101/mt |
| Others | N/A | Below US$108/mt |
Figure 1: Net-positions by participant segment and price comparison | Source: SGX, KGI Research
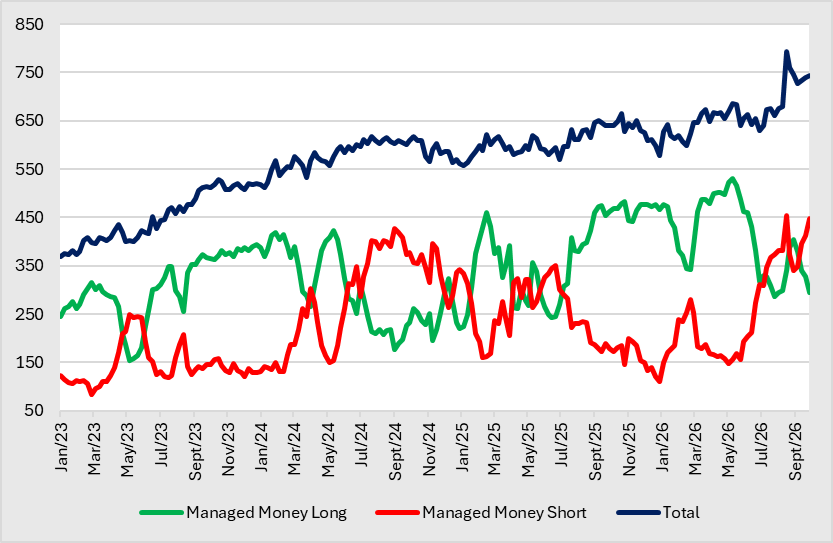
The number of MM with long positions decrease for four consecutive weeks to 295. Accordingly, the number MM with short positions increase for four consecutive weeks to 448. Seasonally, more MMs are prone to long in 1HQ4 and 2HQ2, and there are more MMs with short positions in 1HQ2 and 1HQ3.
| 2025 | 2024 | |||
|---|---|---|---|---|
| Long | Short | Long | Short | |
| High | 483 | 350 | 423 | 427 |
| Low | 219 | 121 | 176 | 131 |
Figure 2: Number of position holders iron ore | Source: SGX, KGI Research
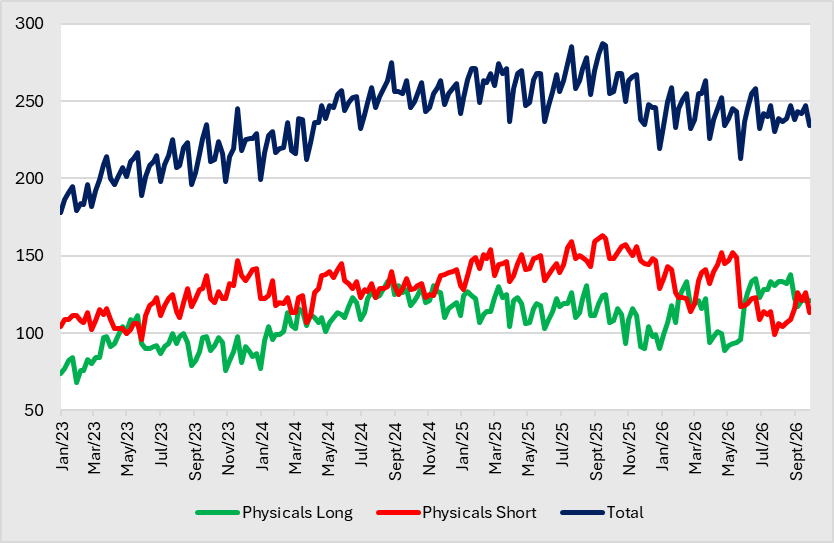
The number of physicals with long positions remain unchanged for two consecutive weeks at 121. Accordingly, the number of physicals with short positions decrease to 113 after last week’s rise. Seasonally, more physicals are prone to being long in 1Q, and there are more physicals with short positions in Q4.
| 2025 | 2024 | |||
|---|---|---|---|---|
| Long | Short | Long | Short | |
| High | 131 | 163 | 135 | 145 |
| Low | 90 | 128 | 77 | 107 |
Figure 3: Number of position holders iron ore | Source: SGX, KGI Research
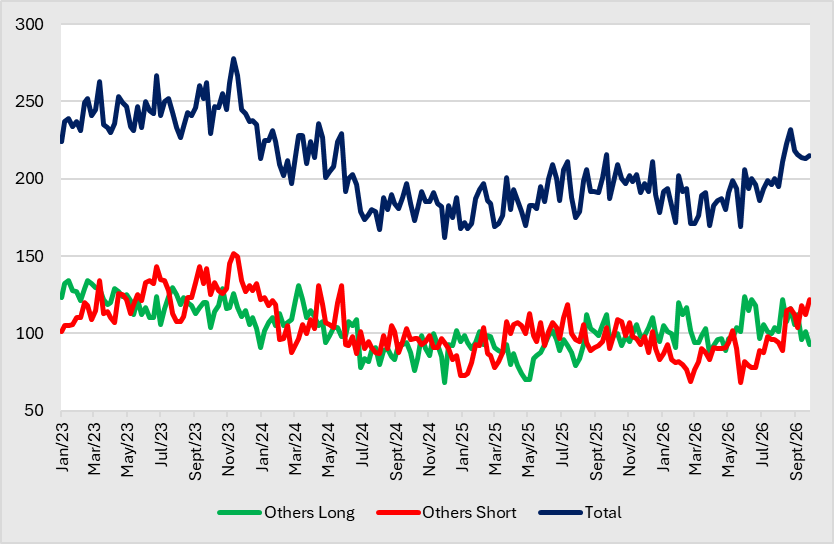
The number of others with long positions decrease to 93 after previous week’s rise. The number of others with short positions increase to 122 after previous week’s decline.
| 2025 | 2024 | |||
|---|---|---|---|---|
| Long | Short | Long | Short | |
| High | 112 | 119 | 131 | 131 |
| Low | 70 | 73 | 68 | 83 |
Figure 4: Number of position holders iron ore | Source: SGX, KGI Research
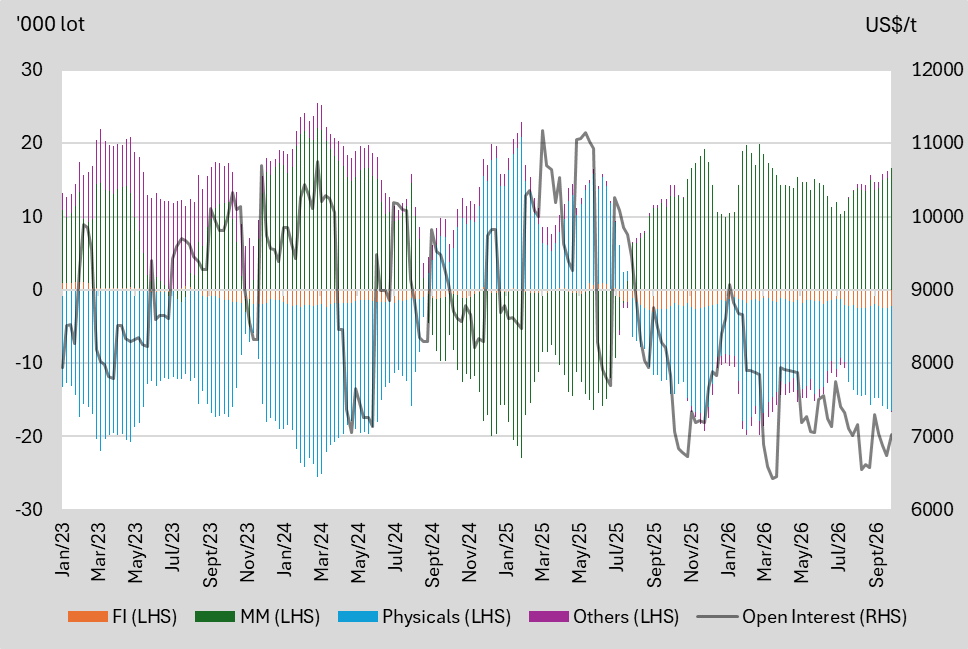
We highlight the key price levels at which each participant switches between net long and net short, based on 2025 data.
| PARTICIPANT | NET LONG | NET SHORT |
|---|---|---|
| Financial Institution (FI) | N/A | N/A |
| Managed Money (MM) | Above US$7,000/t | Below US$11,000/mt |
| Physicals | Below US$11,000/mt | Above US$7,000/t |
| Others | Below US$11,000/mt | Above US$7,000/t |
Figure 5: Net-positions by participant segment and price comparison | Source: SGX, KGI Research
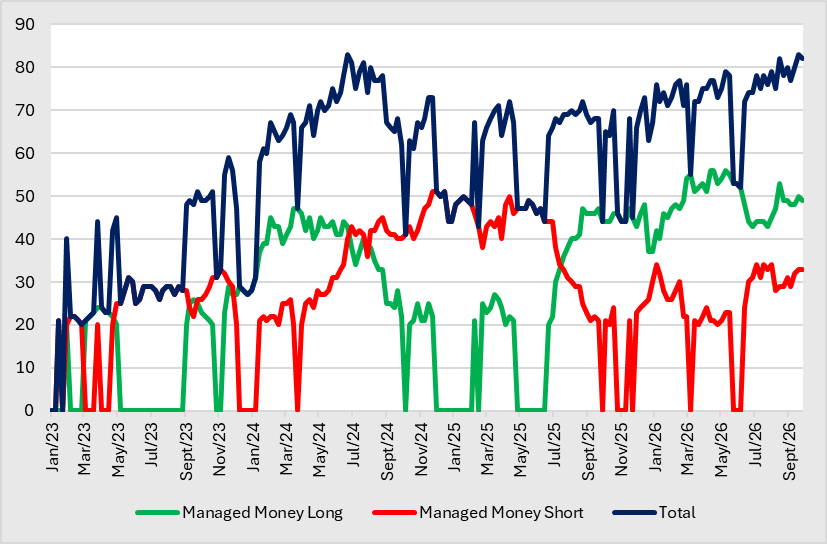
The number of MM with long positions decrease to 49 after previous week’s rise. Accordingly, the number of MM with short positions remain unchanged at 33 after increasing for two consecutive weeks. Seasonally, more MM are prone to long in 1H, and there are more MM with short positions in 2H.
| 2025 | 2024 | |||
|---|---|---|---|---|
| Long | Short | Long | Short | |
| High | 48 | 50 | 47 | 51 |
| Low | 20 | 20 | 20 | 20 |
Figure 6: Number of position holders freight futures | Source: SGX, KGI Research
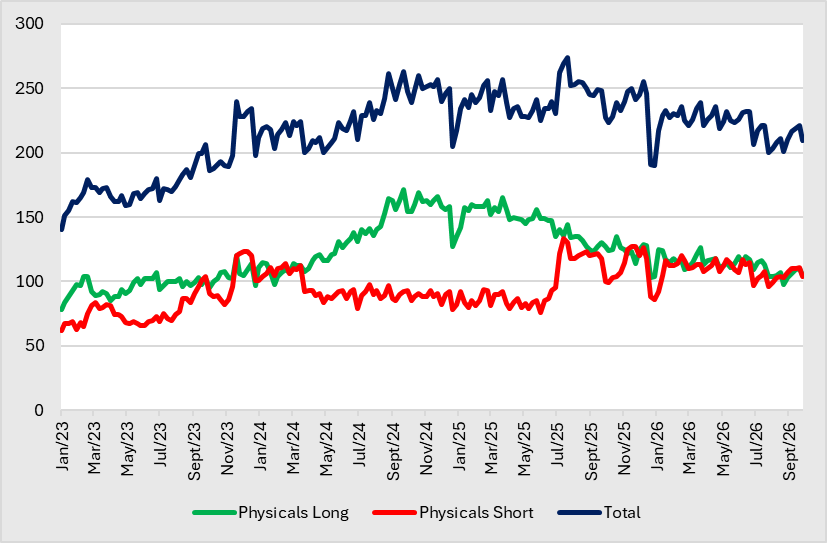
The number of physicals with long positions fell to 105 after increasing for four consecutive weeks. Accordingly, the number of physicals with short positions decrease to 104 after previous week’s rise. The number of physicals has been on a general upward trend since 2Q24, while physicals with short positions generally saw a downtrend since 2Q24.
| 2025 | 2024 | |||
|---|---|---|---|---|
| Long | Short | Long | Short | |
| High | 165 | 133 | 171 | 114 |
| Low | 103 | 76 | 98 | 78 |
Figure 7: Number of position holders freight futures | Source: SGX, KGI Research
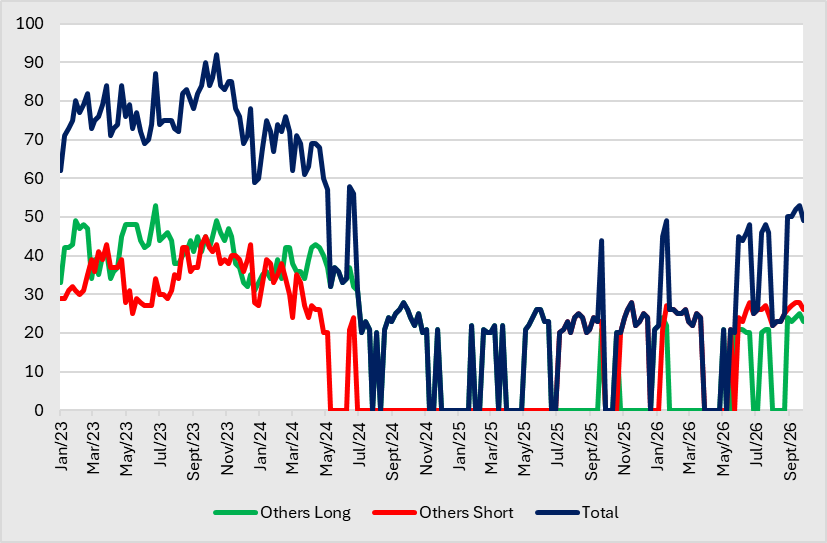
The number of others with long positions decrease to 23 after increasing for two consecutive weeks and the number of others with short positions decrease to 26 after last week’s consolidation.
| 2024 | 2023 | |||
|---|---|---|---|---|
| Long | Short | Long | Short | |
| High | 26 | 28 | 43 | 39 |
| Low | 20 | 20 | 20 | 20 |
Figure 8: Number of position holders freight futures | Source: SGX, KGI Research
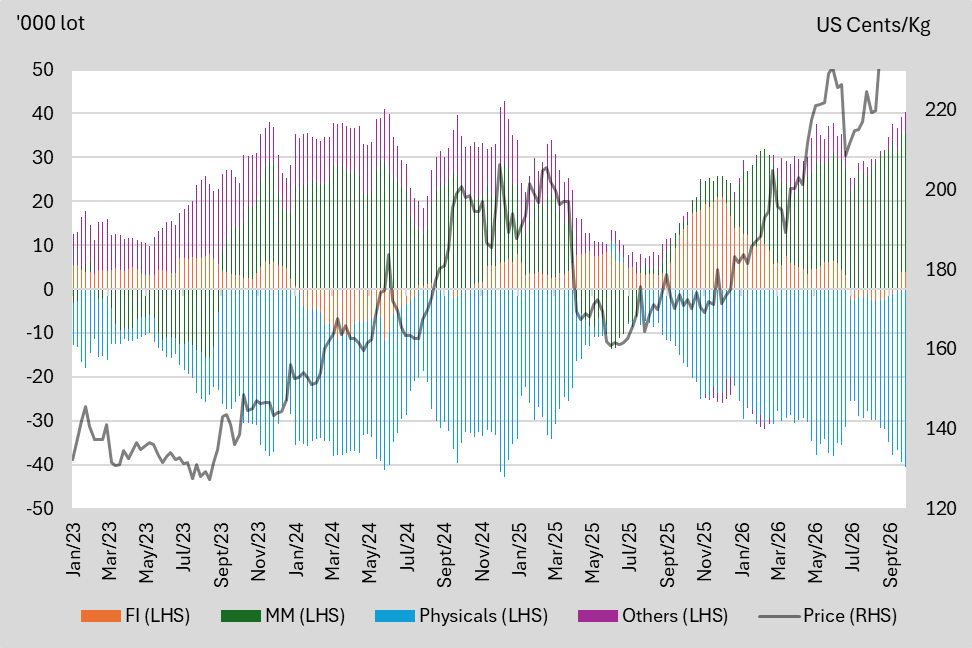
We highlight the key price levels at which each participant switches between net long and net short, based on 2025 data.
| PARTICPANT | NET LONG | NET SHORT |
|---|---|---|
| Financial Institution (FI) | Below US$2.05/kg | N/A |
| Managed Money (MM) | Above US$1.70/kg | Below US$1.70/kg |
| Physicals | Below US$1.65/kg | Above US$1.65/kg |
| Others | Below US$2.05/kg | N/A |
Figure 9: Net-positions by participant segment and price comparison | Source: SGX, KGI Research
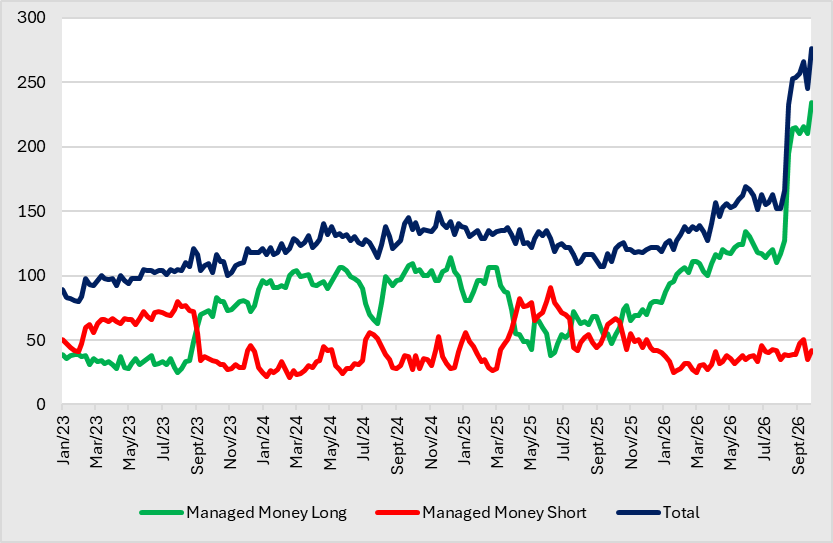
The number of MM with long positions increase to 234 after last week’s decline. Accordingly, the number of MM with short positions increase to 42 after last week’s decline.
| 2025 | 2024 | |||
|---|---|---|---|---|
| Long | Short | Long | Short | |
| High | 106 | 91 | 114 | 56 |
| Low | 38 | 26 | 63 | 21 |
Figure 10: Number of position holders rubber futures | Source: SGX, KGI Research
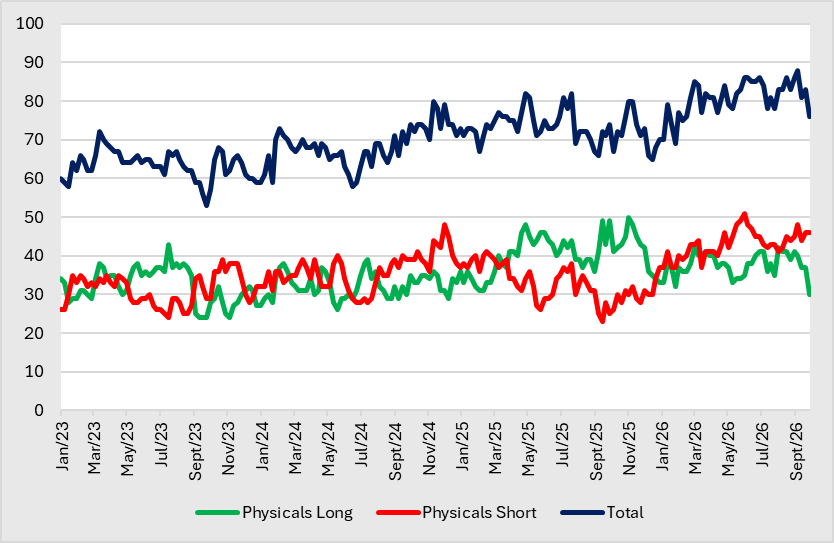
The number of physicals with long positions decrease to 30 after last week’s consolidation. Accordingly, the number of physicals with short positions remain unchanged at 46 after previous week’s rise. Seasonally, more physicals are prone to long in early Q3, and there are more physicals with short positions in Q4.
| 2025 | 2024 | |||
|---|---|---|---|---|
| Long | Short | Long | Short | |
| High | 50 | 41 | 39 | 48 |
| Low | 31 | 23 | 26 | 28 |
Figure 11: Number of position holders rubber futures | Source: SGX, KGI Research
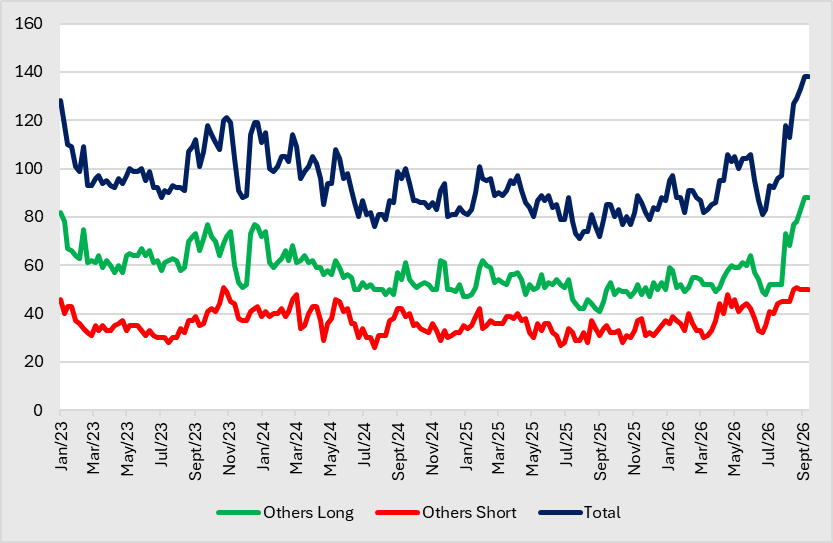
The number of long holders remain unchanged at 88 after increasing for four consecutive weeks. Accordingly, the number of short holders remain unchanged at 50 for two consecutive weeks.
| 2025 | 2024 | |||
|---|---|---|---|---|
| Long | Short | Long | Short | |
| High | 62 | 42 | 77 | 48 |
| Low | 41 | 27 | 48 | 26 |
Figure 12: Number of position holders rubber futures | Source: SGX, KGI Research
Source: SGX, KGI Research
| CATEGORY | DESCRIPTION |
|---|---|
| Financial Institutions | An entity, such as a broker trading desk, bank trading desk or swap dealer, that uses the futures markets to manage or hedge the risk. |
| Managed Money | An entity engaged in organised futures trading on behalf of funds or special investment vehicles — including pension funds, asset managers, hedge funds, proprietary trading groups and family offices. |
| Physicals | An entity that predominantly engages in the physical markets and uses futures to manage or hedge risks associated with production, processing, trading, packing, handling, transportation, warehousing or distribution of a physical commodity. |
| Others | Every other trader not placed into the other three categories. E.g., Broker Agency, Bank Agency, Inter-Dealer Brokers, etc. |