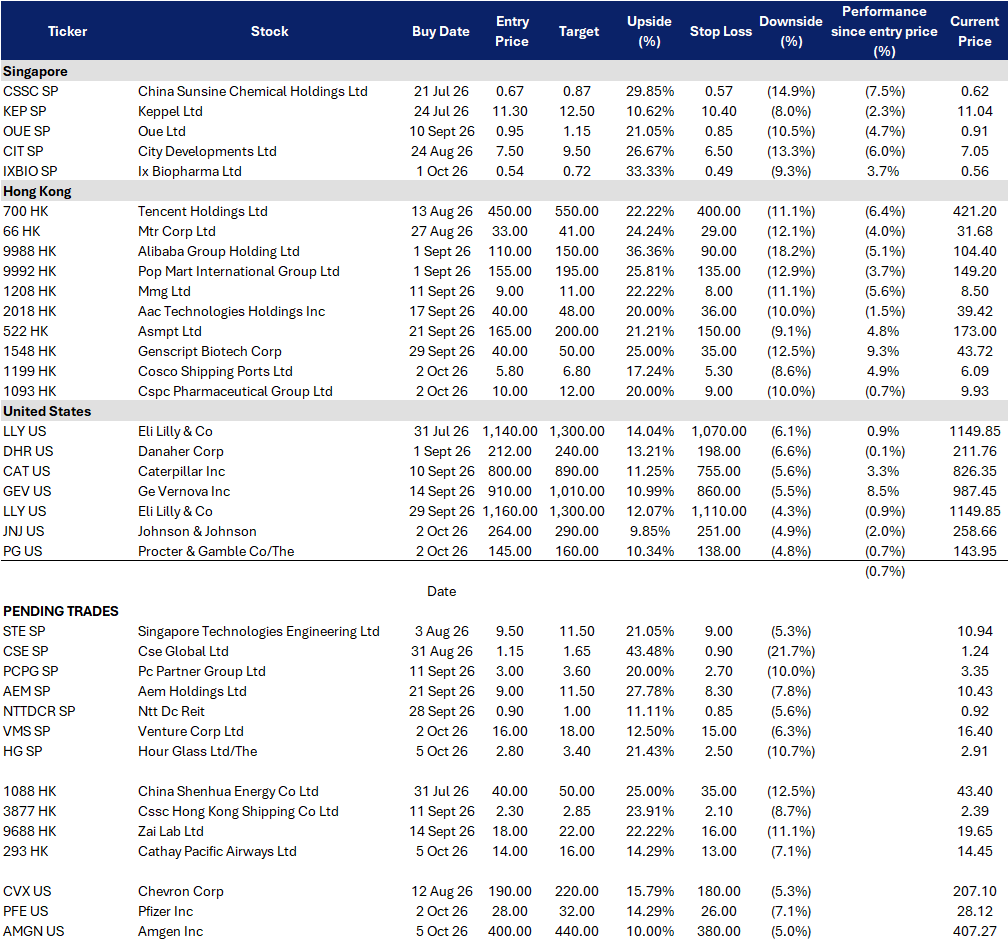

HG SP
Scarcity-brand resilience, balance-sheet strength, and buyback support
KEY INSIGHTS #1
High-end watch demand remains resilient despite a difficult broader luxury backdrop.
The luxury-watch industry continues to face a strong Swiss franc, elevated precious-metal prices and softer discretionary spending, but demand remains increasingly polarised toward scarce brands with strong collector ecosystems. The Hour Glass is positioned at the favourable end of this divide through long-standing allocations from Rolex, Patek Philippe and leading independents. FY26 revenue grew 15.1% YoY to a record S$1.34B despite these industry headwinds, while profit after tax increased 32% to S$179.5M. This suggests its brand mix, geographical diversification and allocation relationships are allowing it to outperform the broader luxury-watch cycle.
KEY INSIGHTS #2
Inventory and a debt-free balance sheet provide strategic flexibility rather than financial risk.
Inventories increased to S$362.2M at end-FY26 from S$328.3M a year earlier, but for The Hour Glass a portion of this inventory represents access to scarce high-value watches rather than conventional excess retail stock. More importantly, the group ended FY26 with S$157.5M of cash and bank balances and, for the first time in its history, no borrowings. Net asset value reached S$1.07B, or approximately S$1.67 per share. This allows management to continue investing in flagship boutiques and inventory while remaining insulated from higher financing costs and giving the group substantial flexibility to return capital.
VMS SP
AI infrastructure recovery, product-cycle inflection, and margin resilience
KEY INSIGHTS #1
AI infrastructure is pulling Venture back into growth after three years of contraction.
he recovery accelerated in 2Q26, with revenue rising 12.5% YoY and net profit increasing 10.3%. Portfolio B, which includes Test & Measurement, Networking & Communications and Semiconductor Related Equipment, grew 25.7% YoY as AI infrastructure spending drove stronger customer demand. For 1H26, Portfolio B revenue increased 18.6% to S$916M, more than offsetting weakness in consumer-facing businesses. Venture therefore offers a differentiated way to participate in AI capex through test, networking and semiconductor equipment without relying on a single chip architecture or customer.
KEY INSIGHTS #2
S$1.1B net cash provides downside protection while preserving upside from new programmes.
Venture ended June with around S$1.11B of net cash, equivalent to roughly 24% of its market capitalisation at the time, while maintaining an earnings model built around high-value engineering rather than commoditised manufacturing. This balance sheet gives management flexibility to invest in new programmes while supporting dividends through the recovery. With V03 closing at S$16.23 on 30 September versus DBS’s recently raised S$22.90 target, an entry around S$16.30 offers a cleaner risk-reward if AI-related demand remains strong and the 4Q26 consumer-product ramp provides the next earnings catalyst.
293 HK
Premium travel resilience, cargo strength, and capacity-driven earnings upside
KEY INSIGHTS #1
Passenger and cargo demand remain stronger than the broader airline-cycle slowdown suggests.
Cathay Pacific carried 15% more passengers YoY in the first eight months of 2026, while August passenger volumes increased another 5% despite only 3% ASK growth. Cathay Pacific and HK Express together carried a record 3.6M passengers in August, while Cathay Cargo tonnage rose 9% YoY to more than 150,000 tonnes. Premium travel demand remains resilient and cargo continues to benefit from semiconductor, pharmaceutical and time-sensitive shipments, helping offset industry-wide concerns around capacity normalisation and weaker yields.
KEY INSIGHTS #2
Capacity expansion and stronger shareholder returns provide the next rerating catalysts.
Cathay has committed around HK$150B to fleet, cabin, lounge and digital investments and targets 150 new aircraft and a 150-destination network over the next decade, creating a multi-year capacity-growth runway as Hong Kong’s three-runway system scales. Nearer term, stronger cash generation has already translated into a HK$0.26 interim dividend, +30% YoY, while DBS forecasts FY26 DPS of HK$0.90, implying roughly a 6% yield around current levels. With 0293 HK trading near HK$14.35 versus DBS’s HK$18.00 target, a pullback toward HK$14.30 offers attractive risk-reward if passenger demand remains firm and jet-fuel prices moderate.
1093 HK
Licensing monetisation, ADC pipeline acceleration, and metabolic optionality
KEY INSIGHTS #1
China biotech licensing momentum is becoming a material earnings driver.
CSPC’s 1H26 revenue surged 40.1% YoY to RMB18.59B, while underlying attributable profit rose 165.8% to RMB6.16B, largely reflecting the monetisation of its innovative pipeline. The standout transaction was the AstraZeneca strategic collaboration covering eight long-acting peptide programmes, which included a US$1.2B upfront payment and up to US$17.3B of potential milestones. CSPC also received another US$30M upfront payment from AstraZeneca in August for a separate siRNA collaboration. These deals validate the external value of CSPC’s R&D platforms and create a funding source that can support development without relying solely on domestic drug sales.
KEY INSIGHTS #2
The pipeline is moving from early-stage optionality toward registrational assets.
CSPC has multiple late-stage programmes capable of reducing dependence on legacy products. On 24 September, the Phase III trial of JMT101 plus osimertinib in first-line EGFR exon 20 insertion NSCLC delivered positive topline results, while SYS6010 has received multiple breakthrough-therapy designations in China across lung and oesophageal cancers. The company is also advancing albumin-bound docetaxel into Phase III breast-cancer studies and continues to broaden its ADC portfolio. The key rerating question is therefore whether these programmes can transition CSPC from a mature pharma franchise into a higher-growth innovative-drug platform.
AMGN US
Diversified biopharma growth platform with obesity and oncology optionality
KEY INSIGHTS #1
Multiple growth franchises are offsetting legacy-product erosion.
Amgen’s growth is increasingly diversified, with 2Q26 revenue up 10% YoY to US$10.1bn and its six key growth drivers increasing 26%, representing nearly 70% of product sales. Repatha and EVENITY grew 37% and 38% YoY, respectively, while small-cell lung cancer therapy IMDELLTRA surged 115% to US$288mn; ongoing development of extended and subcutaneous dosing could further improve convenience and broaden adoption, helping offset biosimilar pressure on mature products such as Prolia and XGEVA.
KEY INSIGHTS #2
Expanding obesity treatment market creates a major new growth opportunity.
More than 1bn people globally live with obesity, while the obesity-drug market is expected to exceed US$100bn annually over the coming decade as treatment penetration expands and next-generation therapies compete on efficacy and dosing convenience. Amgen’s MariTide is already in multiple Phase III programmes, including obesity, diabetes, cardiovascular outcomes and sleep apnoea, with its long-acting design supporting monthly or potentially less-frequent dosing and giving Amgen differentiated exposure to one of the fastest-growing pharmaceutical markets.
PFE US
Oncology-led earnings recovery supported by pipeline catalysts and cost discipline
KEY INSIGHTS #1
ADCEV growth and ESMO catalysts strengthen the post-COVID portfolio.
Pfizer’s underlying business is improving as newer products offset declining COVID revenues, with 2Q26 revenue excluding Comirnaty and Paxlovid up 5% operationally and launched/acquired products growing 18%. PADCEV was a key contributor, with revenue increasing 23% operationally, while its July FDA label expansion into perioperative muscle-invasive bladder cancer regardless of cisplatin eligibility broadens the addressable market; at ESMO 2026 on 23–27 October, Pfizer will present 45 oncology abstracts, including 11 oral presentations, spanning PADCEV and late-stage candidates such as atirmociclib and tivunatamig, providing several near-term pipeline catalysts.
KEY INSIGHTS #2
Sustained oncology innovation supports demand for next-generation cancer therapies.
Oncology remains the largest pharmaceutical therapeutic market, reaching approximately US$291bn in 2025, with IQVIA forecasting around 10% CAGR from 2026–30 as new treatment modalities increasingly reshape cancer care. Antibody-drug conjugates and bispecific antibodies are expected to become larger contributors to oncology spending, supporting Pfizer’s strategy following the Seagen acquisition and its focus on assets such as PADCEV and other next-generation oncology therapies.
STOCKS
STOCKS
STOCKS
–