TECHNICAL ANALYSIS

Technical Analysis: 1 October 2026

Singapore

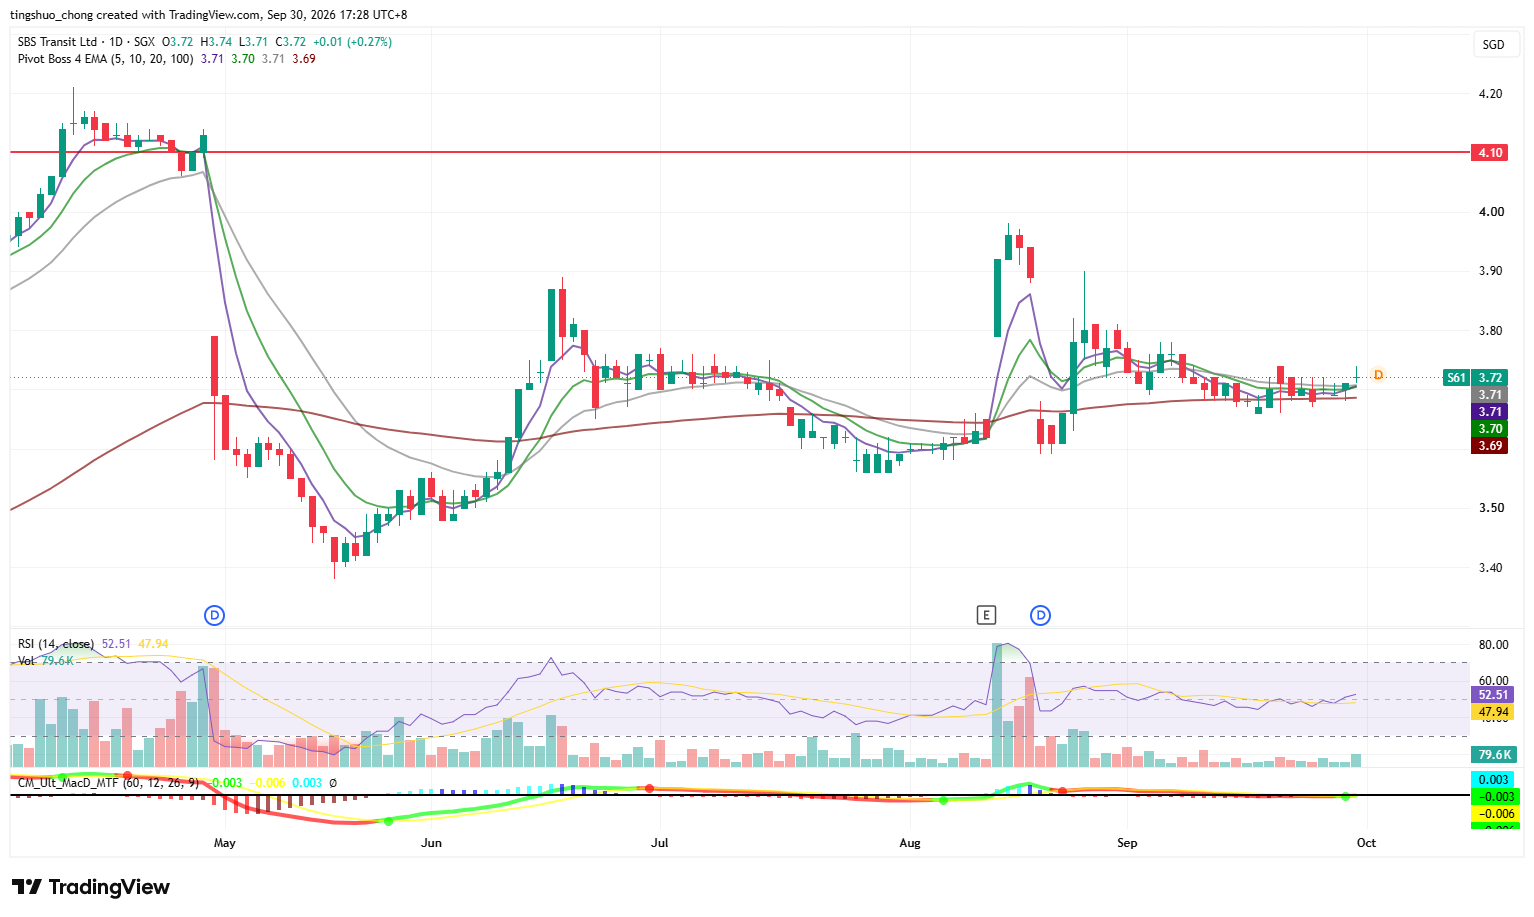
SBUS SP

SBS Transit Ltd.

  • Shares closed above the 5dEMA with rising volume. 
  • RSI is constructive and MACD is about to turn positive. 
  • Long – Entry 3.7, Target 4.1, Stop 3.5 

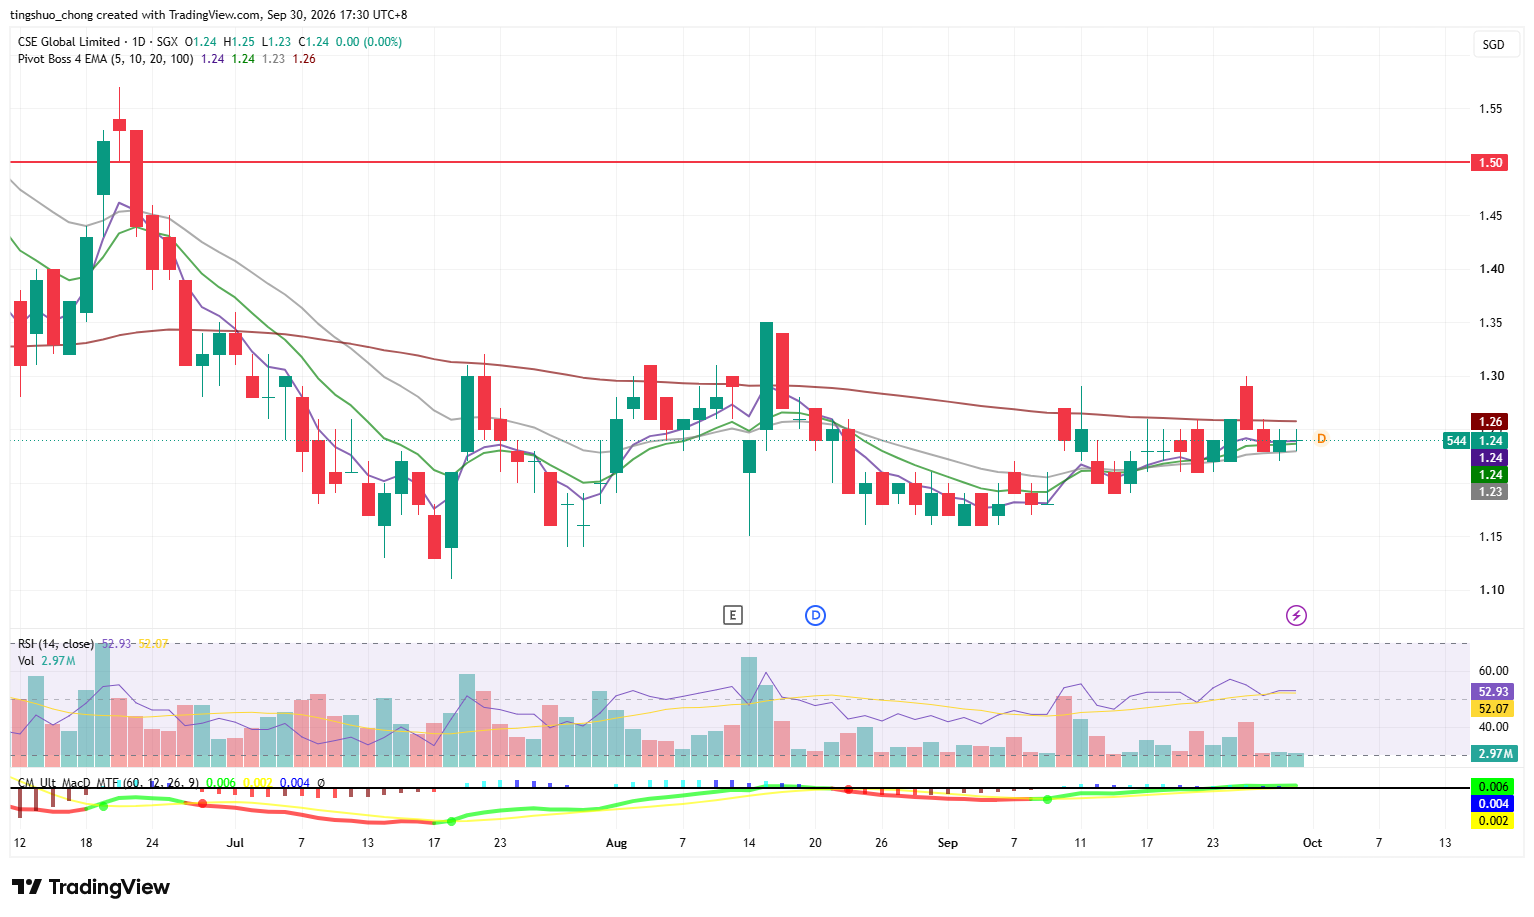
CSE SP

CSE Global Limited

  • Shares closed on the 5dEMA. 
  • Both RSI and MACD are constructive. 
  • Long – Entry 1.24, Target 1.50, Stop 1.11 

Hong Kong

The Hong Kong market is closed today in observance of a public holiday (National Day). Trading resumes on Friday, 2 October 2026.

United States

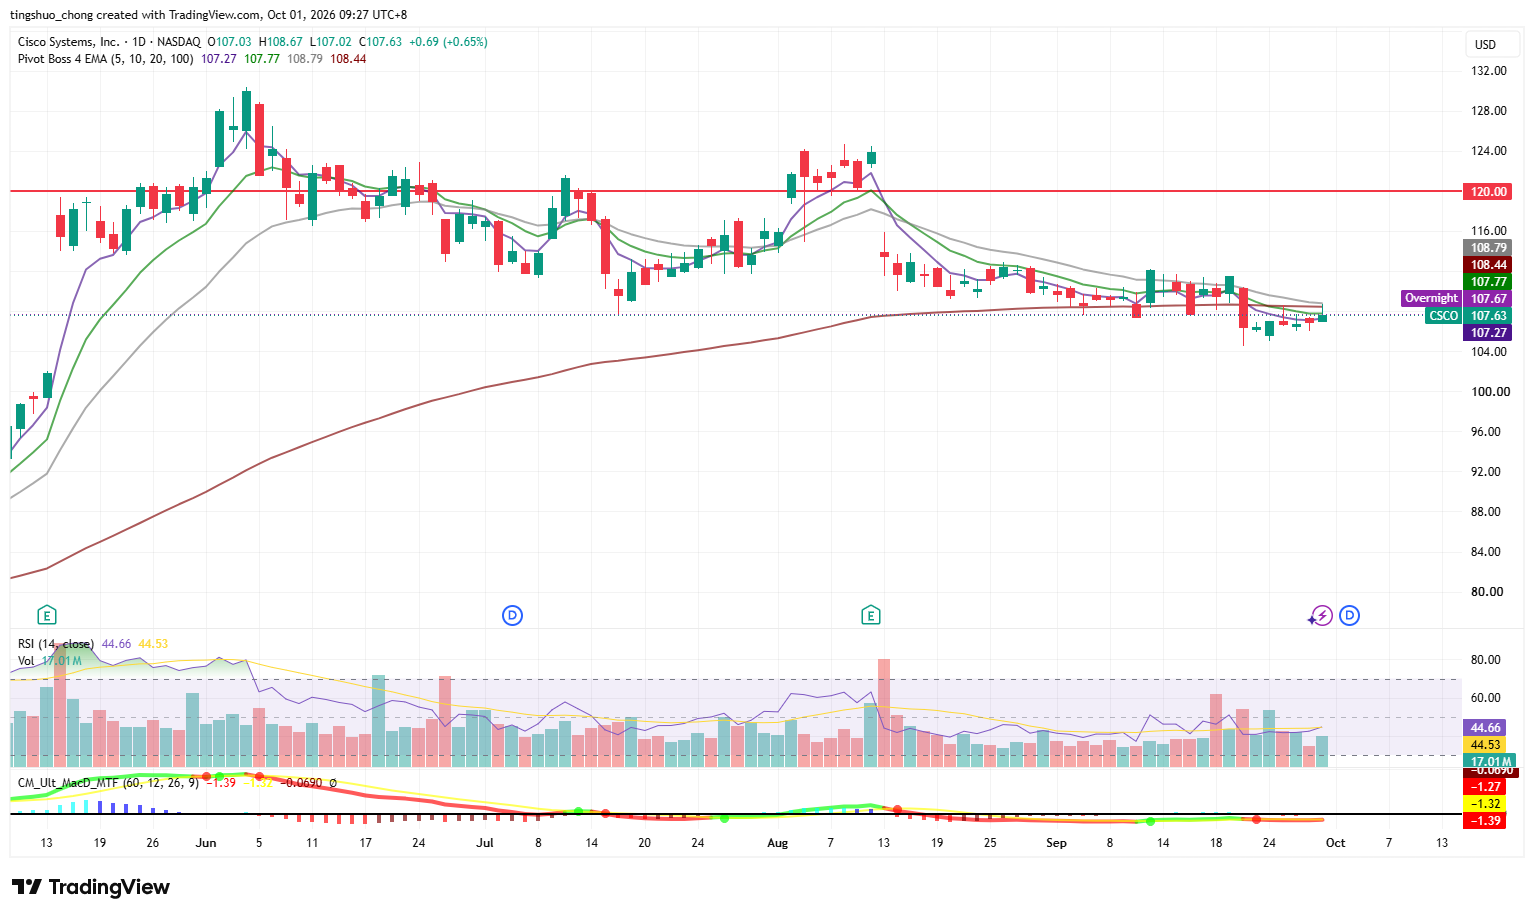
CSCO US

Cisco Systems, Inc

  • Shares closed on the 5dEMA with rising volume.
  • RSI is constructive and MACD is about to turn positive.
  • Long – Entry 106, Target 120, Stop 99

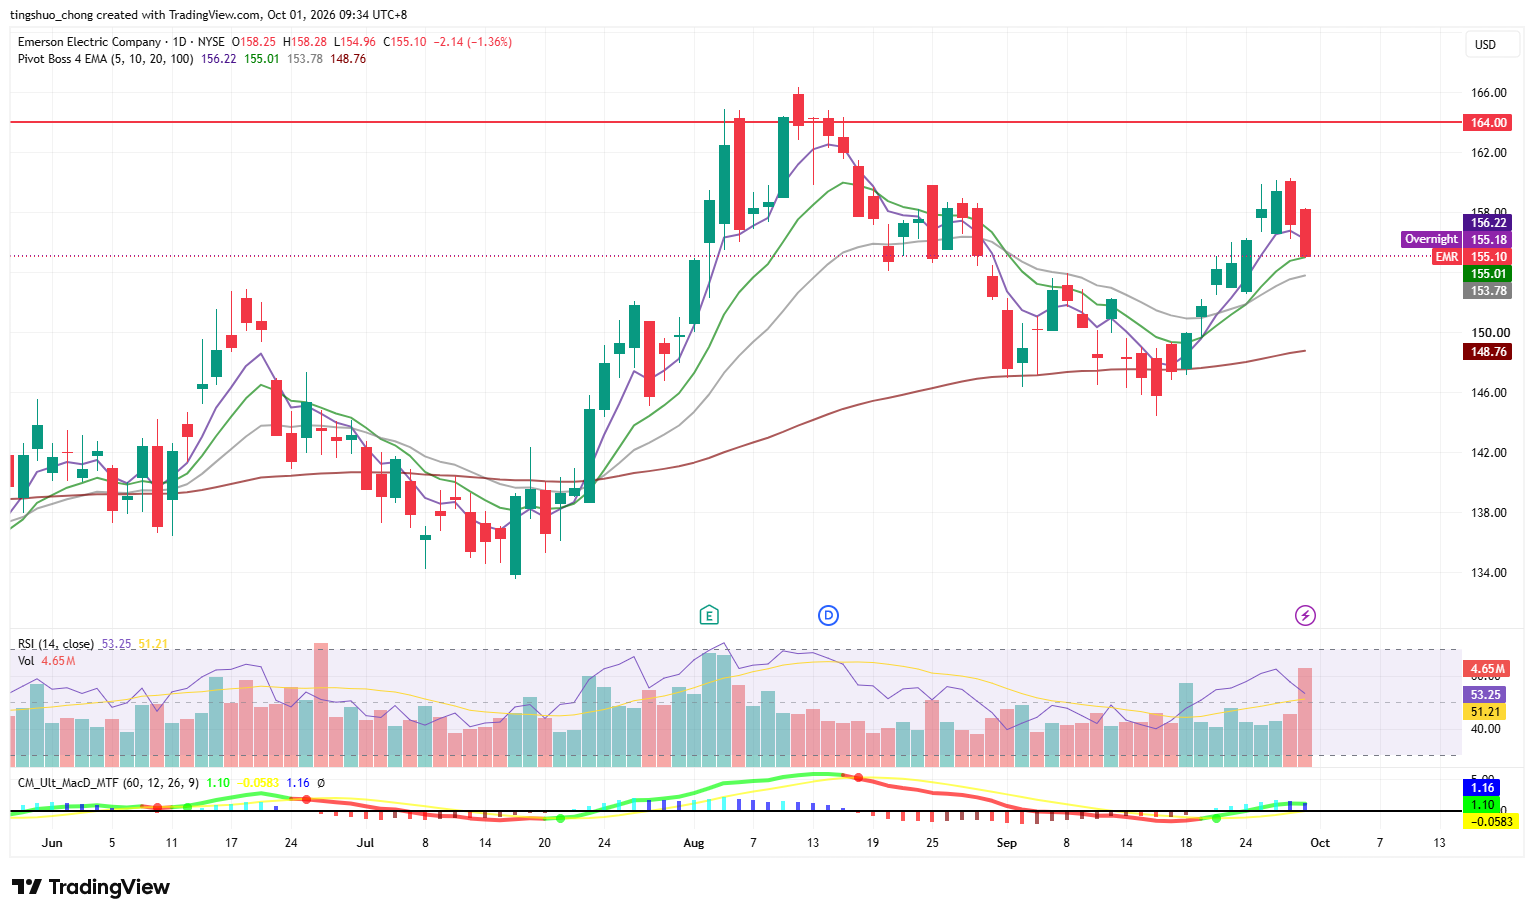
EMR US

Emerson Electric Company

  • Shares closed on the 20dEMA.
  • Both RSI and MACD are constructive.
  • Long – Entry 150, Target 164, Stop 143

^ Back to Top

Earnings

Jabil Inc. (JBL)

  • 4Q26 Revenue: $10.6B, +28.5% YoY, beat estimates by $880M
  • 4Q26 Non-GAAP EPS: $4.40, beat estimates by $0.32
  • 1Q27 Guidance: Revenue is guided to US$10.6–11.4B and adjusted EPS to US$3.80–4.20
  • FY27 Guidance: FY27 revenue is expected at US$44.5B, +24% YoY and above consensus of approximately US$42.79B. Adjusted EPS is guided to US$17.55, +34% and above consensus of approximately US$16.87, with core operating margin expanding to 6.1% and adjusted free cash flow of approximately US$1.6B.
  • Dividend/Share Buyback: Jabil maintains a US$0.08/share quarterly dividend and authorized a new US$1.5B share-repurchase programme in July.
  • Comment: This was an exceptionally strong beat-and-raise quarter. The most important datapoint is the acceleration in AI infrastructure: FY26 AI-related revenue reached approximately US$14.4B, and management expects this to grow 54% to US$22.1B in FY27. Semiconductor capital equipment is also expected to grow roughly 40% to US$4.2B. Importantly, Jabil’s growth is not exclusively AI-driven, with automotive, healthcare, energy infrastructure, defense/aerospace and automation providing additional growth vectors. The key issue is expectations and cash conversion rather than demand. Despite revenue beating consensus by roughly 9%, EPS beating by ~8% and FY27 guidance exceeding estimates, shares fell 10.0% to US$286.86. Investors appear focused on the substantial capacity buildout, the timing of margin realization and FY27 adjusted FCF of only US$1.6B despite 24% expected revenue growth. The stock had also already rerated substantially on AI expectations before earnings. At US$286.86, however, JBL now trades at only approximately 16.3x FY27 adjusted EPS guidance of US$17.55, despite management forecasting 34% EPS growth. That creates a substantially better risk/reward after the earnings reset. The principal variables to monitor are AI revenue conversion toward the US$22.1B FY27 target, utilization of new capacity, core operating margin progression toward 6.1%, adjusted FCF, customer concentration and whether AI growth remains above current expectations. 1Q27 recommended trading range: $265 to $335. Neutral Outlook.


捷普(JBL)

  • 26财年第四季度营收:106亿美元,同比增长28.5%,大幅超出预期8.8亿美元
  • 26财年第四季度非公认会计准则每股收益:4.40美元,显著超出预期0.32美元
  • 27财年第一季度指引:营收预计为106亿–114亿美元;调整后EPS预计为3.80–4.20美元。
  • 27财年全年指引:全年营收预计为445亿美元(同比+24%),高于市场共识的约427.9亿美元;调整后EPS预计为17.55美元(同比+34%),高于市场共识的约16.87美元;核心营业利润率预计扩张至6.1%,调整后自由现金流(FCF)预计约为16亿美元。
  • 股息与回购:维持每季度每股0.08美元的常规股息;7月份新增了15亿美元的股票回购授权。
  • 短评:本季度呈现极为强劲的“超预期+大幅上调指引”态势,基本面全面爆发。核心亮点(AI与多元化共振):最核心的数据在于AI基础设施业务的加速爆发。26财年AI相关营收达到约144亿美元,管理层预计27财年将大增54%至221亿美元。此外,半导体资本设备业务预计也将增长约40%至42亿美元。更重要的是,捷普的增长并非单一依赖AI,汽车、医疗、能源基础设施、国防/航空航天及自动化业务提供了极具韧性的多元化增长向量。核心隐忧(预期博弈与现金转化):尽管营收超预期约9%、EPS超预期约8%且全年指引大幅高于预期,财报后股价仍大跌10.0%至286.86美元。投资者主要担忧庞大的产能建设资本开支、利润率兑现的时间节点,以及在营收预期增长24%的背景下,27财年调整后FCF仅为16亿美元(现金转化率相对偏低)。此外,财报前股价已因AI预期经历了大幅估值重塑(rerated),导致资金在利好落地时选择获利了结。估值修复:在286.86美元的股价水位下,对应27财年17.55美元的调整后EPS指引,前瞻市盈率仅约16.3倍(且隐含34%的EPS高增速)。在经历了财报后的预期重置与估值消化后,其风险收益比已显著改善。后续关键变量包括:(1)AI营收向27财年221亿美元目标的实际转化进度;(2)新增产能的利用率与爬坡情况;(3)核心营业利润率向6.1%迈进的执行轨迹;(4)调整后自由现金流的改善与转化效率;(5)大客户集中度风险;(6)AI业务增速能否持续超越当前的高预期。捷普凭借在精密制造、先进封装与供应链管理领域的深厚壁垒,成功抓住了AI算力硬件与半导体设备扩张的历史性机遇,基本面与订单能见度极为强悍。尽管短期面临产能扩张期的资本开支压力与自由现金流的扰动,但其极具吸引力的前瞻估值与多元化的业务矩阵提供了极高的安全边际。27财年第一季度建议交易区间:265美元至335美元。中性前景。


Micron Technology, Inc. (MU)

  • 4Q26 Revenue: $54.23B, +379.1% YoY, beat estimates by $2.76B
  • 4Q26 Non-GAAP EPS: $33.42, beat estimates by $1.60
  • 1Q27 Guidance: 1Q27 revenue is expected at US$61.5B ± US$1.5B, materially above consensus of approximately US$57.4B, while adjusted EPS is guided to US$38.15 ± US$1.00, above consensus of approximately US$35.47. Non-GAAP gross margin is expected at approximately 86.25%
  • FY27 Guidance: Management expects memory supply-demand conditions to become even tighter in FY27 and FY28, with most FY27 output already committed.
  • Dividend/Share Buyback: Declared a quarterly dividend of US$0.15/share, payable October 29.
  • Comment: This was an exceptionally strong beat-and-raise quarter. The most important development is that the memory upcycle increasingly looks structurally different from prior commodity cycles. Micron’s long-term supply agreements increased from approximately US$22B in June to US$32B, many backed by customer deposits, while demand is already exceeding available capacity. AI infrastructure is making HBM and high-performance DRAM a critical bottleneck, giving Micron substantially greater pricing visibility than in historical memory cycles. The key issue is expectations and sustainability rather than current fundamentals. The stock has already rerated dramatically and is trading around US$1,065, near record highs, so even revenue guidance roughly US$4B above consensus produced only a muted initial share-price reaction. Investors are increasingly asking whether ~86–87% gross margins and extraordinary EPS growth represent a sustainable new earnings regime or peak-cycle economics. Micron also plans more than US$250B of U.S. manufacturing investment through 2035, meaning capital intensity will remain very high even though current free-cash-flow generation comfortably supports expansion. The principal variables to monitor are HBM4/HBM4E shipments, DRAM and NAND pricing, gross margin versus the 86.25% Q1 guide, long-term agreement growth, FY27 supply commitments, hyperscaler AI capex and whether competitors materially accelerate capacity additions. 1Q27 recommended trading range: $950 to $1300. Neutral Outlook.


美光科技(MU)

  • 26财年第四季度营收:542.3亿美元,同比暴增379.1%,大幅超出预期27.6亿美元
  • 26财年第四季度非公认会计准则每股收益:33.42美元,显著超出预期1.60美元
  • 27财年第一季度指引:营收预计为615亿美元(±15亿美元),大幅高于市场共识的约574亿美元;调整后EPS预计为38.15美元(±1.00美元),高于市场共识的约35.47美元;非GAAP毛利率预计高达约86.25%。
  • 27财年全年展望:管理层预计27和28财年的内存供需状况将变得更加紧张,27财年的大部分产出产能已被提前锁定。
  • 股息与回购:宣布每股0.15美元的季度常规股息,将于10月29日支付。
  • 短评:本季度呈现极为震撼的“超预期+大幅上调指引”态势,但市场的核心博弈点已从“基本面”转向“预期的极限与周期的可持续性”。核心亮点(结构性长周期):最重要的发展在于,本轮内存上升周期在结构上已与以往的大宗商品周期截然不同。公司的长期供应协议(LTSAs),且许多协议由客户预付款(押金)支持,当前需求已实质性地超过了可用产能。AI基础设施的爆发使HBM(高带宽内存)和高性能DRAM成为整个算力网络的关键瓶颈,这赋予了美光在历史周期中从未有过的极强定价权与盈利能见度。核心隐忧(估值透支与周期见顶担忧):尽管交出了炸裂的业绩且营收指引高出共识约40亿美元,股价初始反应却相对平淡。原因在于股价已提前经历了大幅重估,交投于1065美元的历史高位附近。投资者开始深刻反思:高达86%–87%的毛利率和非凡的EPS增速,究竟是代表了一种可持续的“新盈利常态”,还是仅仅反映了“周期见顶(peak-cycle) 此外,公司计划到2035年在美国本土制造业投资超过2500亿美元,这意味着即便当前强劲的自由现金流足以支撑扩张,未来的资本密集度依然会居高不下。后续关键变量包括:(1)HBM4及HBM4E等新一代产品的出货与良率表现;(2)DRAM与NAND的现货及合约价格走势;(3)实际毛利率能否稳住并匹配86.25%的极高指引;(4)长期供应协议(LTSAs);(5)27财年产能承诺的实际交付情况;(6)超大规模客户的AI资本开支趋势;(7)竞争对手(如三星、SK海力士)。美光科技凭借在HBM与先进DRAM领域的产能卡位,成功将传统的周期性存储芯片转化为AI算力时代的“稀缺战略资源”,基本面与定价权迎来了历史性的重估。然而,在近乎完美的盈利数据与极高的股价水位下,短期内进一步拔高估值需要证明这种超高利润率并非周期顶点,而是AI时代的新常态。27财年第一季度建议交易区间:950美元至1300美元。中性前景。

^ Back to Top