TECHNICAL ANALYSIS

Technical Analysis: 15 September 2026

Singapore

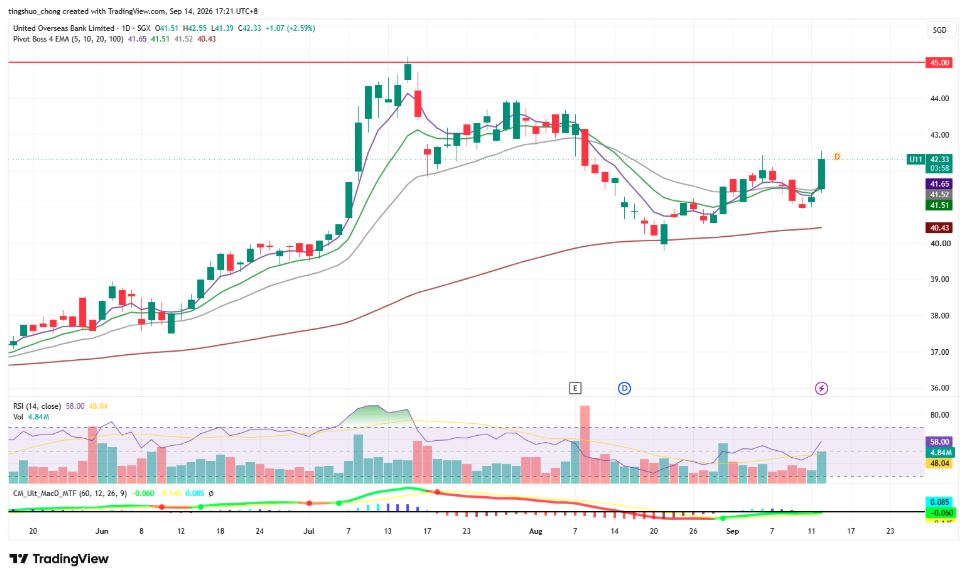
UOB SP

United Overseas Bank Limited.

  • Shares closed above the 5dEMA with rising volume. 
  • RSI is constructive and MACD is about to turn positive. 
  • Buy Entry 41.8, Target 45.0, Stop 40.2 

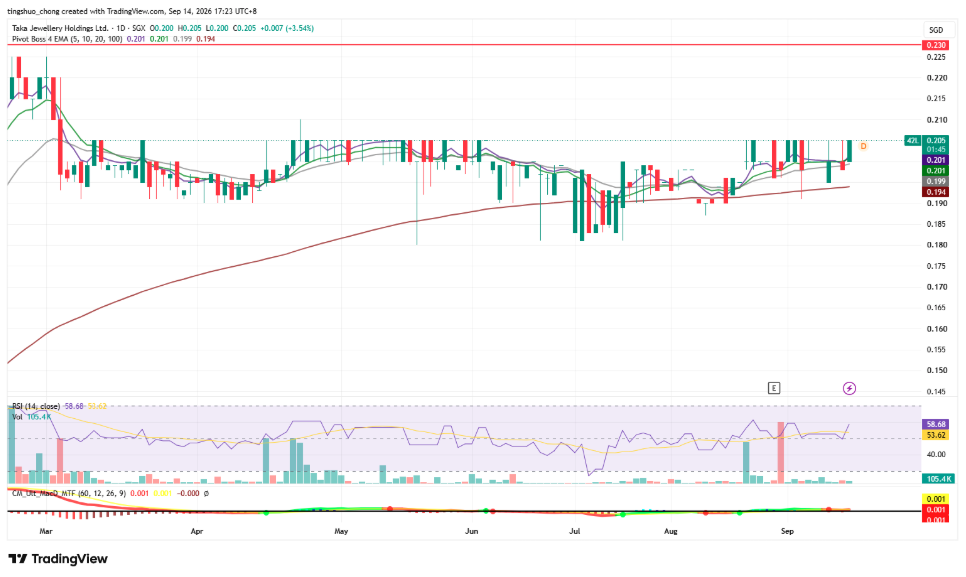
TAKA SP

Taka Jewellery Holdings Ltd.

  • Shares closed above the 5dEMA. 
  • Both RSI and MACD are constructive. 
  • Buy – Entry 0.200, Target 0.230, Stop 0.185 

Hong Kong

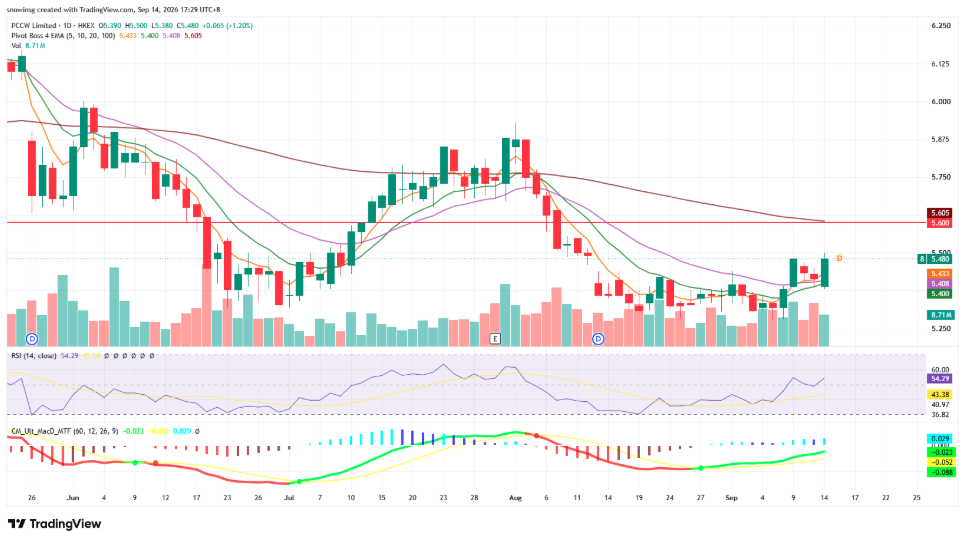
8 HK

PCCW Ltd

  • Shares closed above the 5dEMA.  
  • Both RSI and MACD are constructive. 
  • Long Entry 5.4, Target 5.6, Stop 5.3 

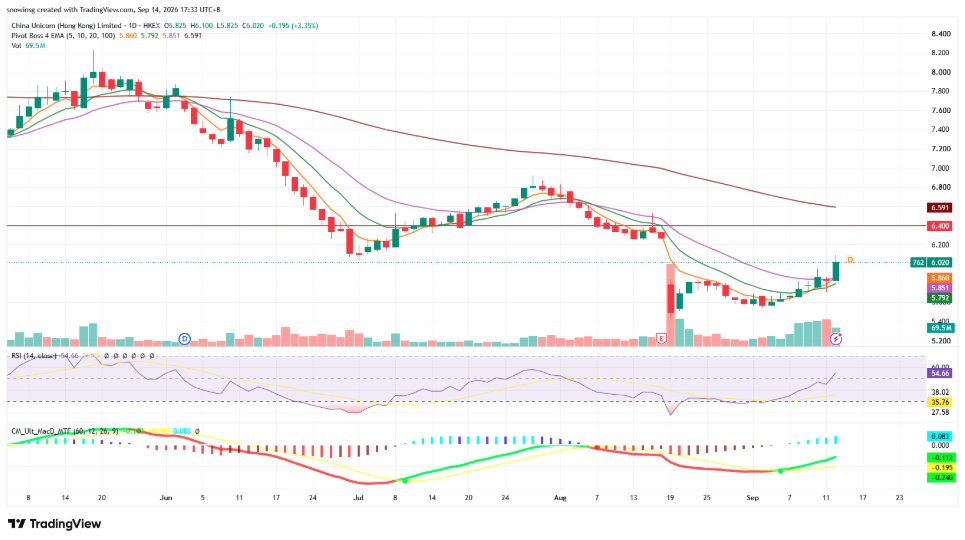
762 HK

China Unicom Hong Kong Ltd 

  • Shares closed above the 20dEMA. The 5dEMA crossed the 20dEMA. 
  • Both RSI and MACD are constructive. 
  • Long – Entry 5.9, Target 6.4, Stop 5.6 

United States

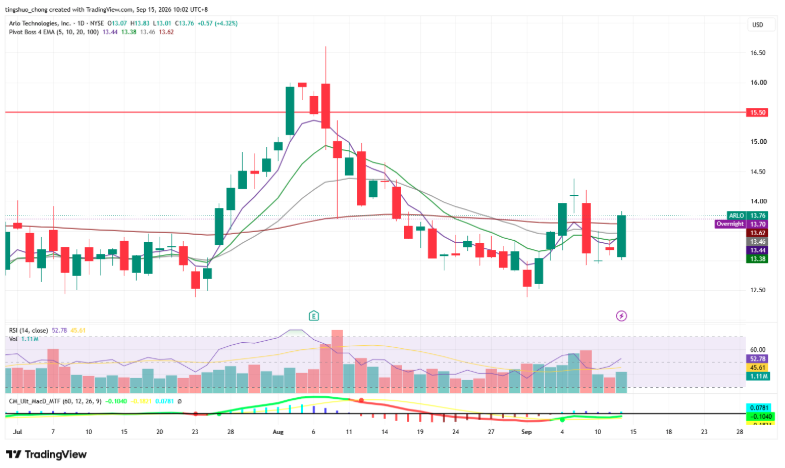
ARLO US

Arlo Technologies, Inc.

  • Shares closed above the 5dEMA with rising volume.  
  • RSI is constructive and MACD is about to turn positive. 
  • Long – Entry 13.5, Target 15.5, Stop 12.5 

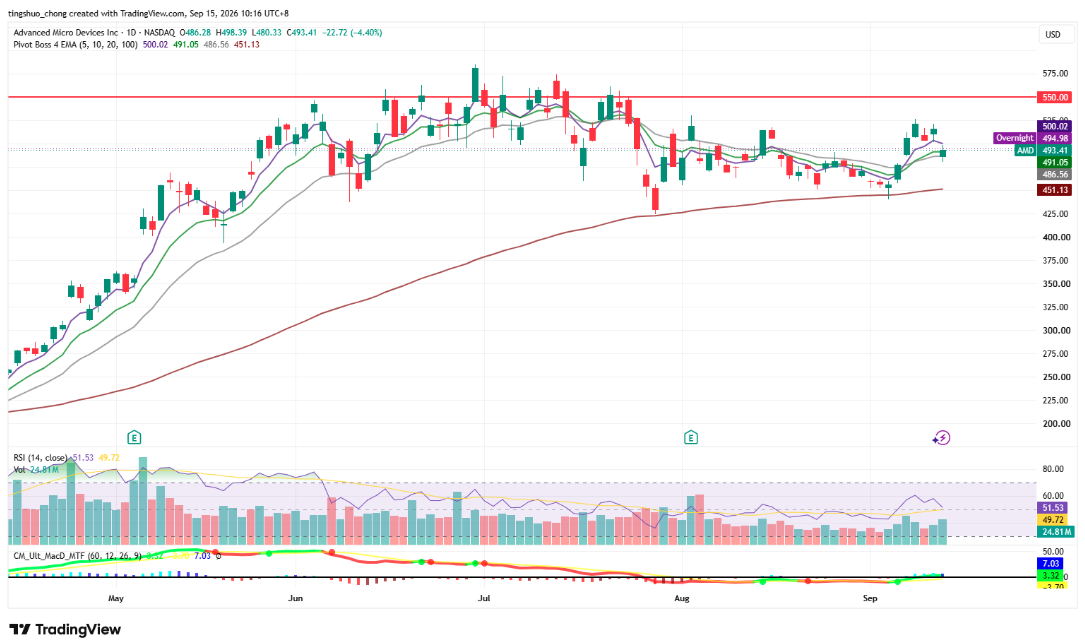
AMD US

Advanced Micro Devices Inc.

  • Shares closed above the 5dEMA with rising volume.  
  • Both RSI and MACD are constructive. 
  • Long – Entry 490, Target 550, Stop 460 

^ Back to Top

Earnings

The Kroger Co. (KR) 

  • 2Q26 Revenue: $34.6B, +2.1% YoY, beat estimates by $70M 
  • 2Q26 Non-GAAP EPS: $1.09, beat estimates by $0.04 
  • FY26 Guidance: Reaffirmed FY26 adjusted EPS guidance of US$5.10–US$5.30, but lowered identical-sales growth excluding fuel to 0.2–0.8% from 1–2% previously. Management cited roughly 140bps of pharmacy-related pressure from Medicare drug-pricing changes, weaker discretionary spending, lower egg prices and the Cyclospora outbreak as key sales headwinds.\ 
  • Dividends/Share Buybacks: Repurchased approximately US$1.0B of shares during the quarter and raised the dividend by 11%, marking Kroger’s 20th consecutive annual dividend increase 
  • Comment: This was a mixed quarter, but the earnings quality was better than the sales headline suggests. Adjusted EPS beat expectations despite identical sales of only 0.2%, indicating that productivity, cost control and higher-margin businesses such as eCommerce and retail media are offsetting weak core sales momentum. The market also appeared to focus on the fact that Kroger maintained its full-year EPS range despite cutting sales guidance, suggesting management still has enough cost and margin levers to defend profitability. The key issue is demand. Same-store sales growth has slowed materially and management highlighted pressure on middle- and lower-income consumers, smaller baskets and softer pharmacy revenue. Some of the weakness is transitory, particularly the Cyclospora impact and drug-pricing changes, but a sustained reacceleration in grocery traffic and basket size has not yet emerged. At the current US$58.49 share price, Kroger trades at a relatively modest multiple of roughly 11x the midpoint of FY26 adjusted EPS guidance, which provides valuation support despite sluggish sales growth. Shares rose approximately 2.6% following the results as investors prioritized profit resilience over the sales guidance cut. The principal variables to monitor are identical sales excluding fuel, traffic versus basket size, pharmacy revenue, eCommerce growth, Precision Marketing profitability, gross margin and the pace of share repurchases. 3Q26 recommended trading range: $54 to $64. Neutral Outlook. 
 

克罗格公司(KR) 

  • 26财年第二季度营收:346亿美元,同比增长2.1%,超出预期7000万美元 
  • 26财年第二季度非公认会计准则每股收益:1.09美元,超出预期0.04美元 
  • 26财年全年指引:重申全年调整后EPS指引为5.10–5.30美元;将剔除燃料后的同店销售增长预期从1%–2%下调至0.2%–0.8%。管理层指出,联邦医疗保险(Medicare)药品定价变化带来的约140个基点的药房业务压力、疲软的非必需品支出、较低的鸡蛋价格以及环孢子虫(Cyclospora)疫情爆发,是导致销售承压的主要逆风因素。 
  • 股息与回购:本季度回购约10亿美元股票,并将股息上调11%,这标志着克罗格连续第20年增加年度股息。 
  • 短评:本季度表现呈现混合态势,但盈利质量远好于表观的销售数据。核心亮点:尽管同店销售仅微增0.2%,调整后EPS依然超预期。这表明生产力提升、严格的成本管控以及电商和零售媒体(retail media),有效对冲了核心杂货销售动能的疲软。市场同样关注到,在下调销售指引的背景下,公司依然坚挺地维持了全年EPS区间,证明管理层仍掌握着充足的成本与利润率调节杠杆来捍卫盈利底线。核心隐忧(底层需求疲软):同店销售增速显著放缓,管理层强调了中低收入消费者面临的财务压力、购物篮缩小(smaller baskets)以及药房收入的疲软。虽然部分逆风(如环孢子虫疫情和药品定价政策)是暂时性的,但杂货店客流和客单价尚未出现实质性的持续重新加速。估值与市场反应:以约58.49美元的股价计算,对应26财年调整后EPS指引中值的前瞻市盈率仅约11倍。这一相对低廉的估值在销售增长乏力的情况下提供了较强的安全边际。财报后股价上涨约2.6%,表明投资者在当前宏观环境下,将“盈利的韧性”置于“销售指引的下调”之上。后续关键变量包括:(1)剔除燃料后的同店销售表现;(2)客流量与客单价(购物篮大小);(3)药房业务收入的修复情况;(4)电商业务的增长斜率;(5)精准营销(零售媒体广告);(6)整体毛利率的稳定性;(7)股票回购的执行节奏。克罗格凭借卓越的供应链效率、自有品牌渗透率以及高毛利的零售媒体业务,在消费降级与需求疲软的逆风中展现了极强的盈利防御性。尽管顶层收入增长面临宏观压制,但其稳健的现金流与极具吸引力的估值使其成为极佳的防御型底仓资产。26财年第三季度建议交易区间:54美元至64美元。中性前景 

^ Back to Top