PCPG SP
GPU pricing power, AI-server optionality, and margin normalization
KEY INSIGHTS #1
Tight GPU and graphics-memory supply is supporting ASPs even as unit volumes remain constrained.
The current memory shortage is creating an unusual earnings setup for graphics-card manufacturers. In 1H26, PC Partner’s own-brand graphics-card revenue fell 9.2% to HK$4.46B as shipment volume declined 18.4%, but average selling prices increased 10.7%. More importantly, ODM/OEM graphics-card revenue jumped 73.9% to HK$1.48B despite a 38.4% volume decline because ASP increased 181%. Group revenue therefore still rose 1.5% YoY to HK$6.45B, while gross margin expanded sharply to 16.5% from 10.5%. PC Partner has previously indicated that higher graphics-memory prices should continue supporting VGA pricing until supply improves, creating a near-term buffer against lower unit output.
KEY INSIGHTS #2
AI servers provide a credible second growth engine beyond consumer GPUs.
PC Partner is transitioning from primarily an add-in-board GPU manufacturer toward higher-value enterprise compute. At NVIDIA GTC 2026, the group showcased a 4U NVIDIA MGX server using RTX PRO 6000 Blackwell Server Edition GPUs and ConnectX-8 networking, alongside a 6U eight-GPU server targeted at on-premise AI and digital-twin workloads. The 4U platform supports up to eight GPUs with 96GB of GDDR7 memory per card. Management has also indicated that 6U systems have already started shipping, while the MGX 4U server is expected to become available from September. Initial volumes are unlikely to transform group earnings immediately, particularly where systems are sold as lower-margin barebones, but successful qualification with system integrators and data centres could materially expand PC Partner’s addressable market beyond gaming GPUs.
CIT SP
Singapore residential strength, capital recycling, and strategic-review optionality
KEY INSIGHTS #1
Singapore residential demand remains resilient despite high interest rates and policy constraints.
CDL’s Singapore residential franchise remains the clearest near-term earnings driver. In 1H26, the group and its JV associates sold 352 units worth S$892.2M, while Newport Residences achieved 83% take-up since its January launch. The development pipeline has also been replenished through the Tanjong Rhu Road and Peck Hay Road GLS sites, adding roughly 900 units and lifting the Singapore residential pipeline to about 2,200 units. This supports continued earnings visibility into 2027–28 despite a more mature property cycle.
KEY INSIGHTS #2
September strategic-review outcome could become the next major valuation catalyst.
Management has committed to announce the outcome of its strategic review by end-September 2026, including the group’s future strategic direction, capital-allocation framework and implementation roadmap. This is potentially more important for the stock than another strong property-sales quarter: credible asset disposals, lower leverage, clearer return hurdles or further shareholder distributions could narrow CDL’s persistent discount to underlying asset value. Nearer term, the 570-unit Lucerne Grand launch in October provides an additional operational catalyst if take-up remains strong.
1208 HK
Copper scarcity, record cash generation, and Khoemacau growth optionality
KEY INSIGHTS #1
Copper market tightness remains supportive, with AI and grid investment reinforcing structural demand.
Copper prices are trading near record levels as physical inventories outside the US tighten, concentrate availability remains constrained and potential US tariffs distort global trade flows. At the same time, electricity-grid upgrades, renewable deployment and AI data-centre buildouts continue to support structural copper demand. MMG is a direct beneficiary through Las Bambas and its expanding African copper portfolio. 1H26 marked MMG’s highest first-half copper production since 2018, while Las Bambas alone produced 210,195 tonnes of copper concentrate. With copper around US$14,000/t, the sensitivity of earnings and free cash flow to elevated pricing remains substantial.
KEY INSIGHTS #2
Khoemacau is evolving into a materially larger copper platform.
MMG’s Botswana operation offers the clearest medium-term production kicker. Khoemacau is targeting annual copper capacity of around 130,000 tonnes by 2028 versus 42,120 tonnes produced in 2025, with longer-term potential approaching 200,000 tonnes. The August discovery of the nearby Kgwebe deposit adds approximately 1.4Mt of contained copper and 90Moz of silver to Khoemacau’s Mineral Resources, strengthening the case for further mine-life and throughput expansion. If copper prices remain elevated while Khoemacau ramps as planned, MMG can transition from a primarily Las Bambas-driven story into a more diversified high-growth copper producer.
66 HK
Rail patronage resilience, property-profit crystallisation, and infrastructure optionality
KEY INSIGHTS #1
Hong Kong mobility remains resilient, with tourism and cross-border traffic supporting rail demand.
Hong Kong transport patronage exceeded 970M journeys in 1H26, while passenger journeys on-time remained at 99.9%. High Speed Rail traffic has been particularly strong, with patronage surpassing 16M passengers in 1H26, a record for the period. This matters because a gradual recovery in inbound tourism, cross-border travel and local mobility directly supports fare revenue while also feeding MTR’s higher-margin station retail and advertising businesses.
KEY INSIGHTS #2
New railway projects create long-duration asset growth despite near-term capex pressure.
MTR is entering a major infrastructure investment phase, including the Northern Link and other network extensions, with management previously indicating more than HK$100B of investment in new Hong Kong railway projects. The company was also invited in July to commence detailed planning and design for the Pak Shek Kok Station project, while securing long-dated green funding including more than HK$18.8B of HKD bonds and EUR3B of green bonds in 2026. Near-term leverage and financing costs rise, but successful execution expands MTR’s future passenger catchments and creates additional Rail + Property monetisation opportunities.
TWST US
DNA synthesis platform leveraged to AI-driven biotech discovery
KEY INSIGHTS #1
DNA synthesis is scaling with improving margins.
Twist is benefiting from rising demand across DNA synthesis, protein solutions and NGS, with 3Q26 revenue up 23% YoY to US$118.4mn, marking its 14th consecutive quarter of sequential growth. DNA Synthesis and Protein Solutions revenue grew 39% YoY to US$56.6mn, while gross margin improved to 52.8%, showing that higher utilisation and product mix are supporting both growth and operating leverage.
KEY INSIGHTS #2
AI drug discovery and personalised medicine increase demand for synthetic DNA.
AI-enabled drug discovery is accelerating the design of proteins, antibodies and therapeutic candidates, increasing the number of biological sequences that need to be physically synthesised and tested. The recent Phase III success of Moderna and Merck’s personalised mRNA cancer vaccine also highlights the broader shift toward genomics-driven and personalised therapies, where sequencing, mutation identification and rapid DNA synthesis become increasingly important research tools.
PANW US
Platformization, AI-security expansion, and M&A-driven TAM capture
KEY INSIGHTS #1
AI adoption is structurally increasing cybersecurity complexity and supporting platform consolidation.
Enterprise deployment of generative and agentic AI is creating additional identities, data flows and attack surfaces, while simultaneously making cyberattacks faster and more automated. This should keep security spending relatively resilient and favor vendors capable of securing multiple layers of the enterprise stack. Palo Alto’s 3Q26 revenue grew 31% YoY to US$3.0B, while Next-Generation Security ARR reached US$8.1B, +60% YoY including CyberArk and Chronosphere. Management specifically cited accelerating organic bookings as customers increase spending to secure AI deployments, supporting the view that cybersecurity remains one of the more durable enterprise IT spending categories.
KEY INSIGHTS #2
FY26 year-end execution can demonstrate that M&A growth is not coming at the expense of cash-flow quality.
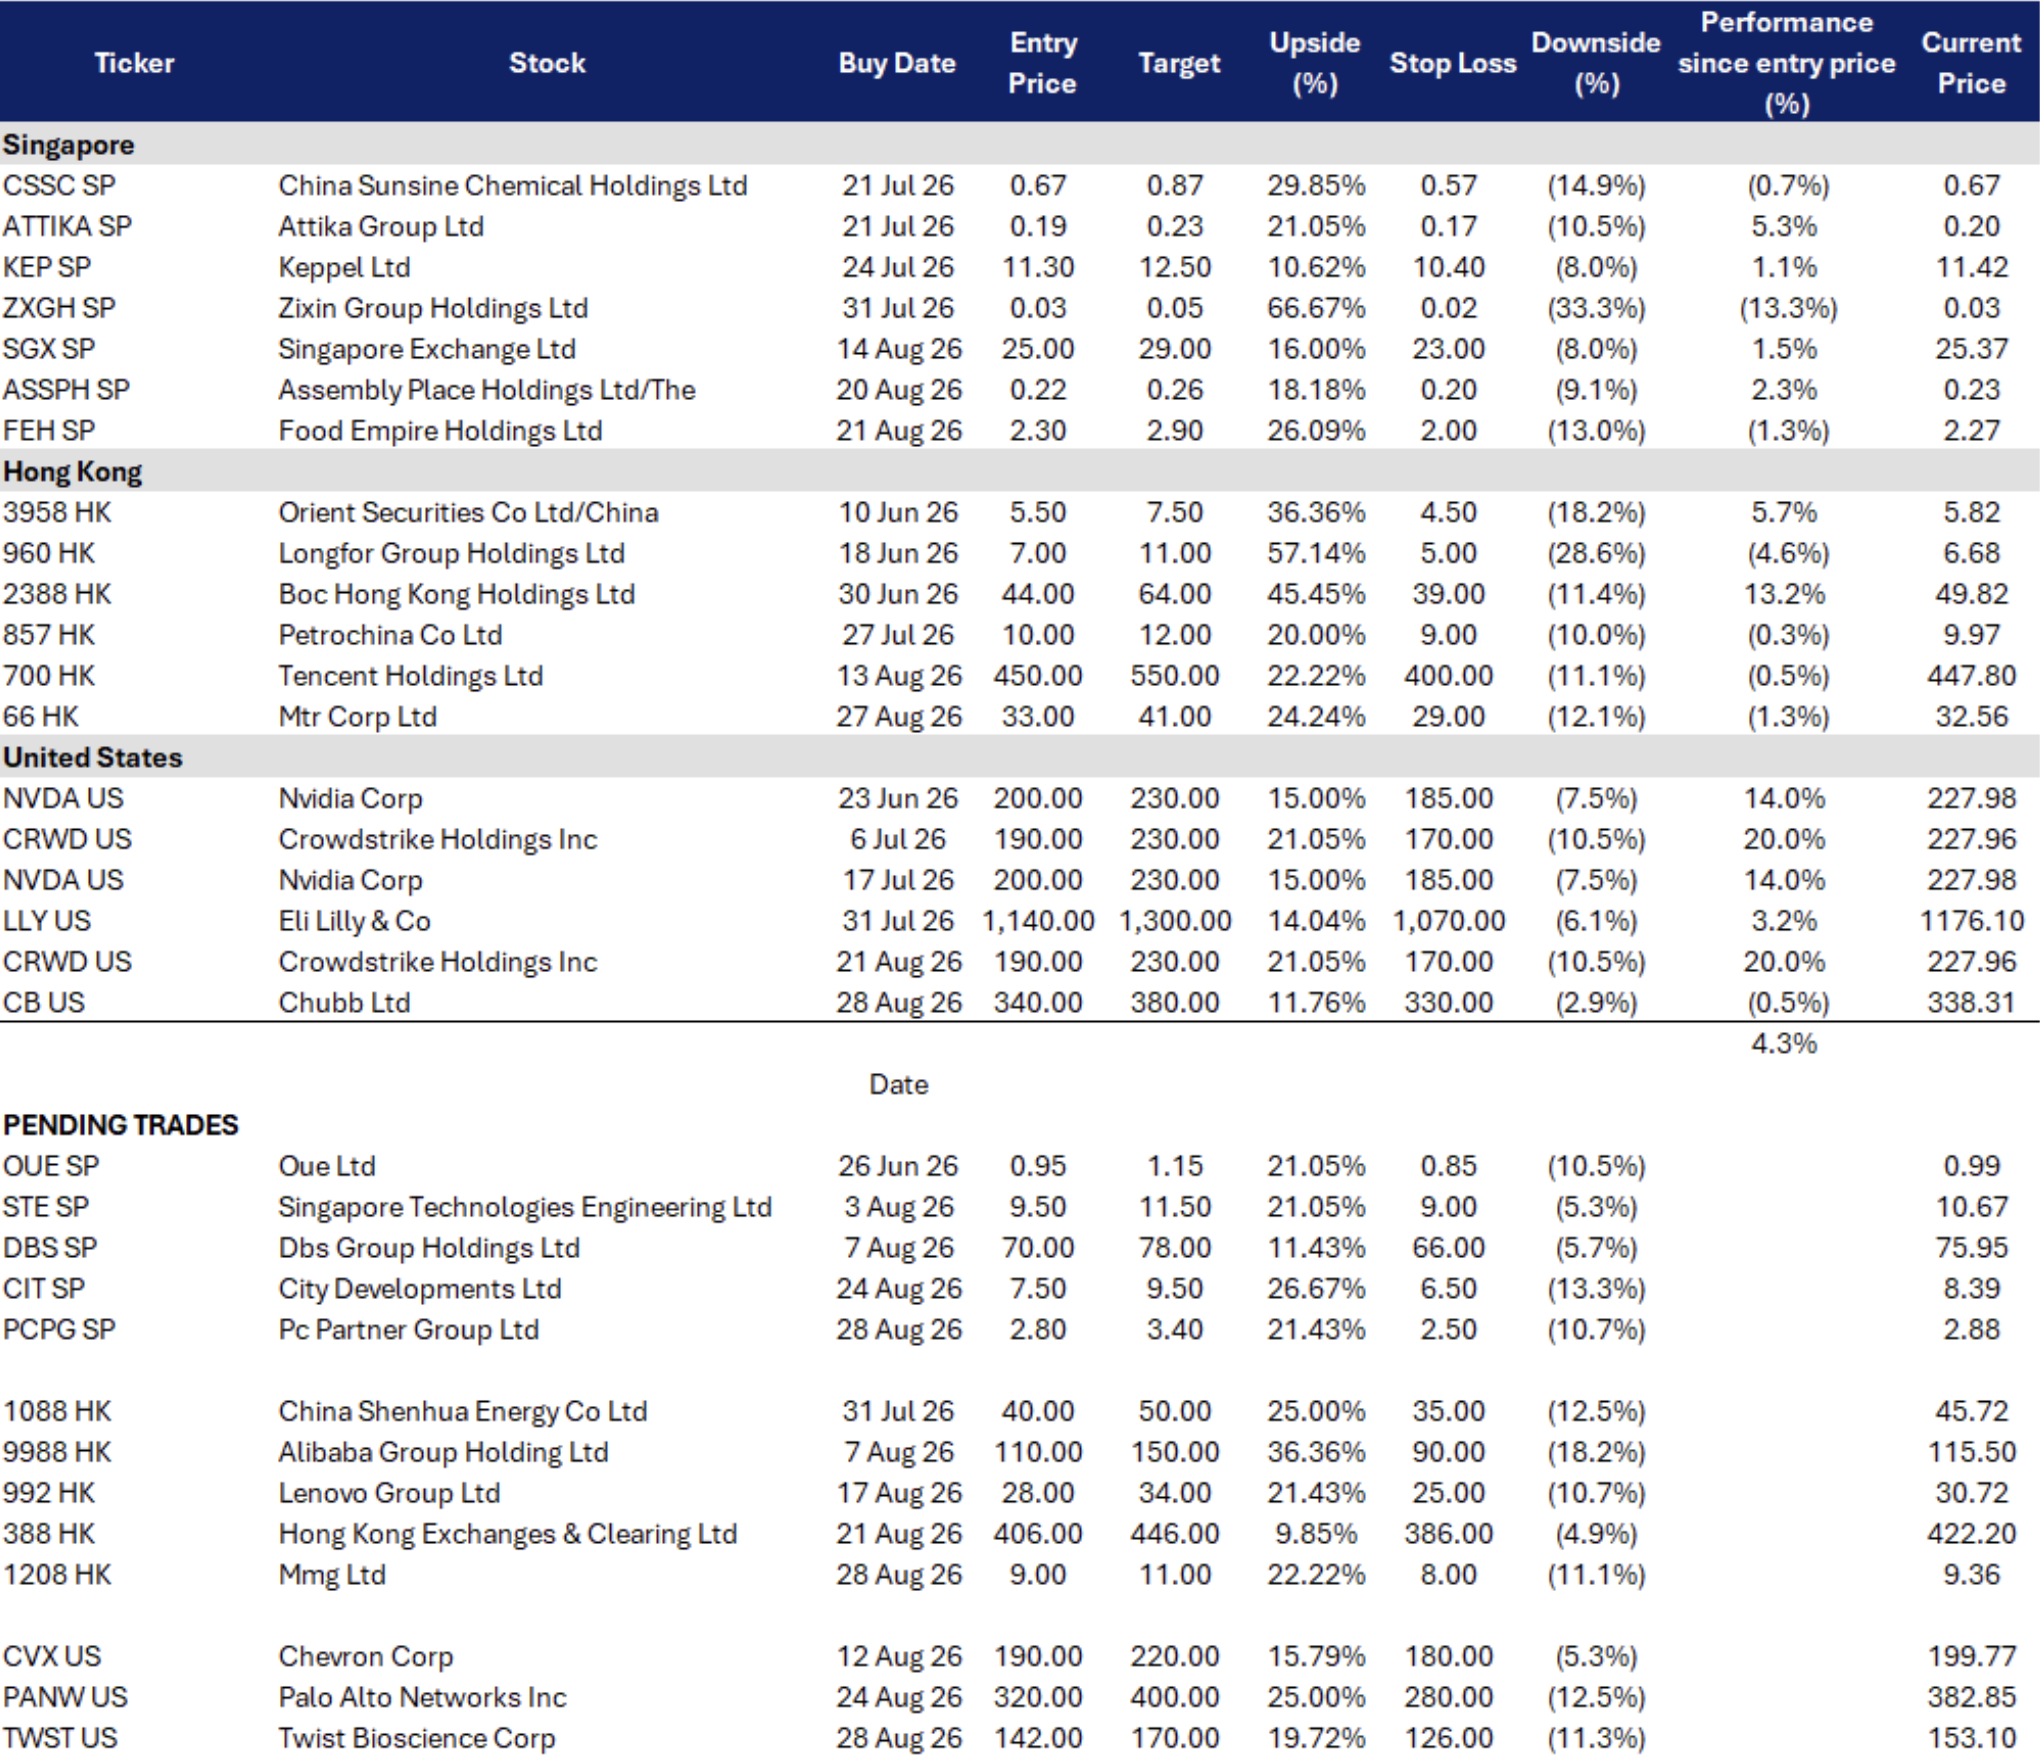
Management guided 4Q26 NGS ARR to US$8.90–8.95B, representing 59–60% YoY growth, revenue to US$3.345–3.355B, +32%, and RPO to US$20.9–21.0B. Despite acquisition-related costs pushing GAAP operating income negative in 3Q26, trailing 12-month adjusted FCF margin reached 38.5%, +430bps YoY, and management continues to target at least 40% adjusted FCF margin in FY28. With PANW closing around US$349.56 on 20 August after pulling back from recent highs, another quarter of strong organic bookings alongside stable FCF margins would help rebuild confidence that the enlarged platform can sustain both growth and profitability.
STOCKS
STOCKS
STOCKS
–